Europe Healthcare IT Market (2025-2032)
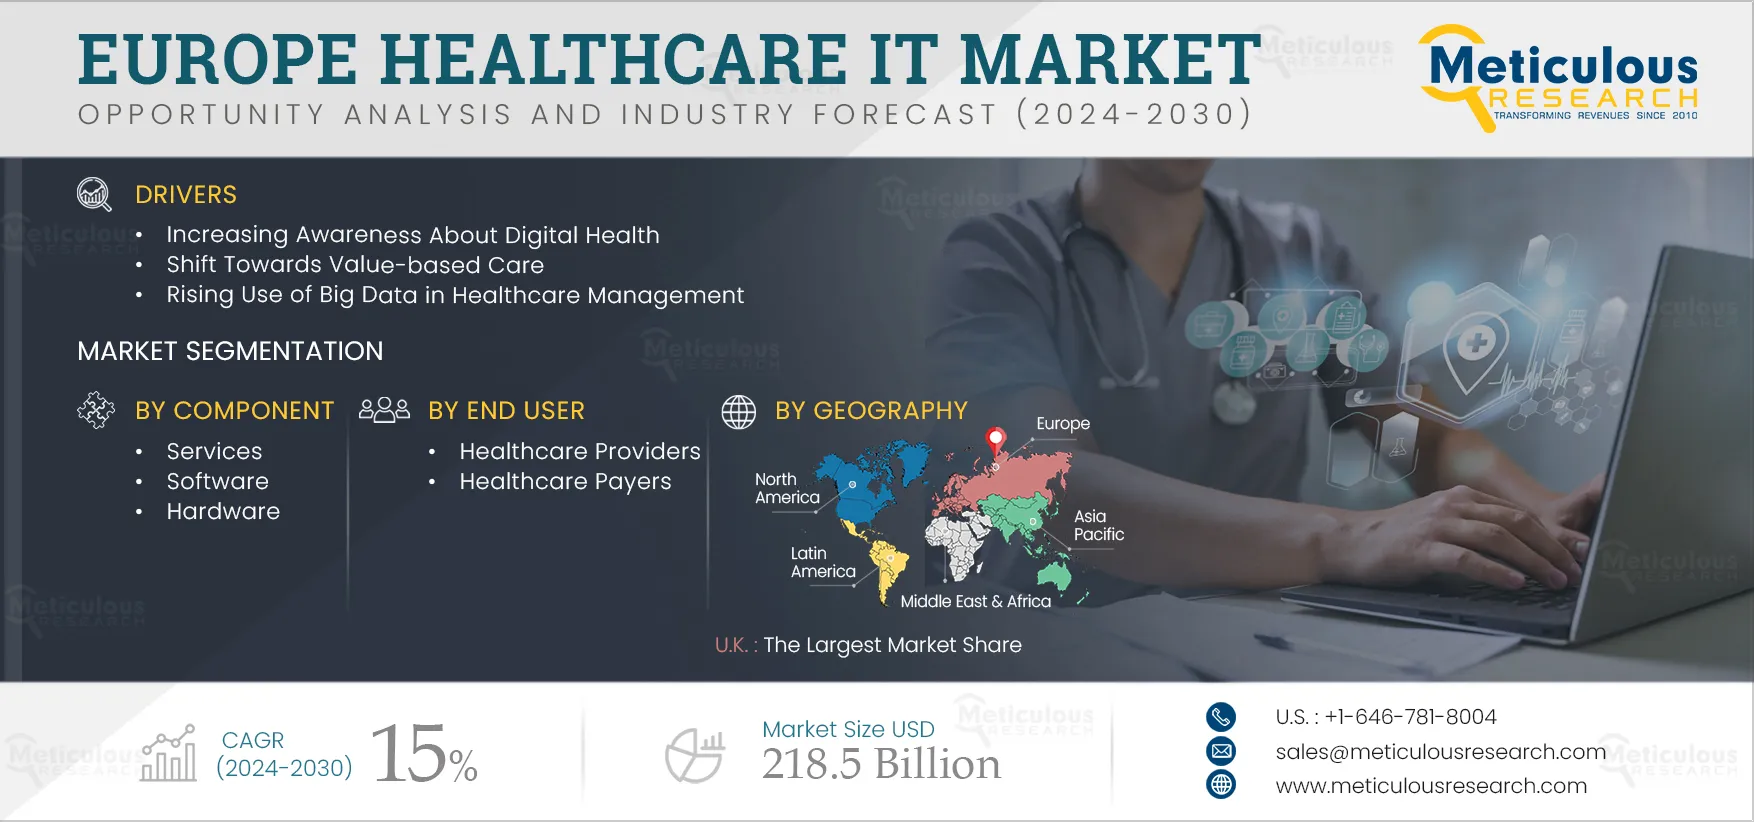
The Europe Healthcare IT Market is expected to reach $218.5 billion by 2032, at a CAGR of 15% from 2025 to 2032.
- Published
- Jan 2025
- Pages
- 350
- Format
- PDF + Excel
- Report ID
- MRHC - 1041003
- Base year
- 2024
- 2032 · FORECAST
- $218.5B
- 2032
- $218.5B
- CAGR 2025–2032
- 15%
2024 baseline · 2025–2032 forecast at 15% CAGR · hover a bar for the value
Key highlights
In 2025, the Healthcare IT Provider Solutions Segment is Expected to Account for the Largest Share of the Market
Among the Components, in 2025, the Services Segment is Expected to Account for the Largest Share of Europe Healthcare IT Market
In 2025, the Web/Cloud-based Segment is Expected to Account for the Largest Share of the Europe Healthcare IT Market
In 2025, the Healthcare Providers Segment is Expected to Account for the Largest Share of the Europe Healthcare IT Market
Among the Countries, the U.K. Expected to Account for the Largest Market Share in 2025
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2024 |
| Estimated Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size (2032) | USD 218.50 billion |
| CAGR (2025–2032) | 15% |
| Format | PDF, Excel & Cloud Portal · 350 pages |
| Segments Covered | By Product: PACS & VNA, Computerized Physician Order Entry (CPOE) Solutions, Population Health Management Solutions, Specialty Information Management Systems, mHealth Solutions, Healthcare Integration Solutions, Telehealth Solutions, Medical Image Analysis Systems, Laboratory Information Systems (LIS), Practice Management Systems, Clinical Decision Support Systems (CDSS), E-Prescribing Systems, Radiology Information Systems (RIS), Radiation Dose Management (RDM) Solutions · By Delivery Mode: Web/Cloud-based, On-premise · By Component: Services, Software, Hardware · By End User: Healthcare Providers Hospitals, Ambulatory Centers, Home Healthcare & Assisted Living Centers, Diagnostic & Imaging Centers, Pharmacies, Private payers, Public Payers |
| Countries Covered | Europe (U.K., Germany, France, Italy, Spain, Switzerland, Sweden, Denmark, Belgium, Netherlands, Rest of Europe) |
| Key Companies | McKesson Corporation, International Business Machine Corporation, Allscripts Healthcare Solutions, Inc., Epic Systems Corporation, Dell Technologies Inc., Cerner Corporation, Oracle Corporation, Cognizant Technology Solutions Corporation, Nuance Communications, Inc., NextGen Healthcare, Inc., Systems, Inc., Conifer Health Solutions, LLC, Koninklijke Philips N.V., Infor, Inc. |
Report overview
Segments covered: product, delivery mode, component, end user. Regions: Europe.
Healthcare IT comprises various technologies that gather, store, analyze, and represent information for various areas in the healthcare industry. Over the years, the Europe healthcare IT industry has transitioned from applying IT solutions for basic administrative functions to core clinical tasks. The increased amount of data gathered through patient records has resulted in the need for advanced IT solutions in the healthcare industry. This includes deploying advanced analytics solutions, population health management solutions, and AI solutions for various clinical and non-clinical applications.
The key factors driving the growth of the Europe healthcare IT market are the increasing awareness about digital health, government mandates and financial incentives for the adoption of HCIT solutions, the shift towards value-based care, the rising use of big data in healthcare management, the high returns on IT investment in the healthcare industry, and the rising incidence of chronic diseases. However, high installation and maintenance costs are restraining the market’s growth.
Furthermore, the growing focus on cloud-based solutions and the rising adoption of AI and IoT in healthcare are creating opportunities for market growth. However, interoperability issues and data security and privacy concerns are challenging market growth.
Report infographic
Market dynamics
1 factors across 1 forceBenefits Offered by e-health Apps Support the Adoption of Healthcare IT Solutions
eHealth apps provide a new, innovative way to deliver healthcare services outside traditional care settings, enhancing healthcare professionals’ productivity and improving patients’ health outcomes.
Conventionally, patients visit healthcare facilities regularly for their regular checkups, diagnoses, or treatment. Following are some of the benefits offered by the eHealth apps:
- These apps offer electronic health records via health-smart wearables, enabling faster and easy access to patient’s health data. Doctors can collect and retrieve patients’ clinical data in just one click. This feature allows them to make more comprehensive, informed, and timely medical decisions.
- Through mobile health apps, healthcare professionals, including doctors and nurses, can gain swift access to medical databases, drug information, and laboratory results, all within a matter of minutes. Additionally, these mobile devices and apps provide valuable resources such as drug reference guides, medical calculators, clinical guidelines, and other decision-support tools. These functionalities play a pivotal role in enhancing the accuracy of disease diagnosis and treatment decisions, thereby reducing the error rate and improving overall practice efficiency and knowledge.
- eHealth apps decrease unnecessary procedures and reduce the cost of care by lowering the risk of getting preventable chronic illnesses and hospital readmission rates.
- eHealth apps close this communication gap by offering variable tools to keep communication channels between patients and doctors open 24/7. In other words, patient-doctor communication apps can provide a more efficient medical workflow by keeping doctors connected with patients remotely and effortlessly.
In European countries, eHealth adoption is high in primary healthcare. According to the European Commission, countries such as Denmark, Estonia, Finland, Spain, Sweden, and the U.K. have the highest levels of eHealth adoption. The study also showed that EHR is currently available across all EU countries, and nearly 96% of general practitioners (GPs) use it in their practice.
On the other hand, countries such as Greece, Lithuania, Luxembourg, Malta, Romania, and Slovakia have the lowest levels of adoption. According to an eHealth survey by the Healthcare Information and Management Systems Society (HIMSS), EMR implementation is a top priority in Germany (24%) and Switzerland (23%) but plays a minor role in more EMR-mature countries like the Nordics (8%), Spain (6%), and the Netherlands (3%).
Table of contents
12 chapters · 169 sections · 350 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Product | Healthcare IT Provider Solutions | — |
| By Component | Services | — |
| By Delivery Mode | Web/Cloud-based | — |
| By End User | Healthcare Providers | — |
| By Country | Expected | — |
By Product
- The healthcare IT provider solutions segment is expected to account for the largest share of the market.
- The large market share of this segment is attributed to various factors, including a heightened focus on patient safety and care, the well-established healthcare infrastructure in Europe, the increasing demand for high-quality healthcare services, the growing investments and regulatory mandates for the adoption of e-health solutions, the rising adoption of Electronic Health Records (EHRs), and the growing population of elderly individuals with chronic illnesses.
- For instance, in Germany, the e-health law enacted in 2015 outlined a roadmap for the integration of digital applications into the healthcare system.
- According to this law, all medical practices and hospitals were expected to be connected to the telematic infrastructure by the end of 2018.
- The framework and objectives established by this legislation have significantly boosted the growth of the e-Health sector in the country.
By Component
- The Services Segment is Expected to Account for the Largest Share of Europe Healthcare IT Market
- The services segment is estimated to account for the largest share of the Europe healthcare IT market.
- This is primarily due to factors such as a shortage of physicians and specialists, the shift towards cloud-based services, and the growing burden of chronic diseases.
- For instance, according to the IDF Diabetes Atlas, the number of people with diabetes aged 20-79 years was 61.4 million in 2021, and it is projected to increase to 67.0 million by 2032 and further to 69.0 million by 2045.
By Delivery Mode
- The web/cloud-based segment is estimated to account for the largest share of the Europe healthcare IT market.
- The large market share of this segment is attributed to the benefits offered by private cloud solutions, such as lower upfront costs, absence of maintenance expenses, and flexible storage options.
- Cloud and web-based software eliminate the need for physical servers, reducing the costs associated with maintaining on-premises servers.
- They are more cost-effective than on-premise solutions, resulting in cost savings, are platform-agnostic and user-friendly, and can be accessed at any time, all of which contribute to their widespread adoption.
By End User
- The healthcare providers segment is estimated to account for the largest share of the Europe Healthcare IT market.
- This segment's significant market share can be attributed to several factors, including the increasing demand for convenient healthcare services due to the high prevalence of chronic diseases, the shortage of medical professionals, advanced healthcare IT infrastructure in hospitals, and the growing focus on and availability of provider-specific healthcare IT solutions.
- Healthcare IT solutions are known to enhance patient care, reduce hospital administrative costs, and streamline workflows in healthcare settings, contributing to their widespread adoption among healthcare providers.
By Country
- The U.K. Expected to Account for the Largest Market Share in 2025
- This significant market share can be primarily attributed to government-sponsored programs aimed at enhancing the quality of healthcare in the country through improved infrastructure and data storage facilities.
- In England, the National Health Service (NHS) has made significant commitments to an informatics strategy aimed at transforming healthcare service delivery through the use of technology, both at the national and local levels.
- For instance, the formation of the National Advisory Group on Health Information Technology in late 2015 was a significant step, providing guidance to the Department of Health and NHS England in their efforts to digitize the secondary care system.
- Various incentive schemes such as reimbursement schemes, provision of free computers and software, grants, and pay-for-performance mechanisms like the quality and outcomes framework (QOF) and Personalized Health Care (PHC) 2020 have all played a role in driving strong incentives for HIT adoption.
Geographic analysis
Europe
Over the years, the Europe healthcare IT industry has transitioned from applying IT solutions for basic administrative functions to core clinical tasks.
Competitive landscape
- McKesson Corporation
- International Business Machine Corporation
- Allscripts Healthcare Solutions, Inc.
- Epic Systems Corporation
- Dell Technologies Inc.
- Cerner Corporation
- Oracle Corporation
- Cognizant Technology Solutions Corporation
- Nuance Communications, Inc.
- NextGen Healthcare, Inc.
- Systems, Inc.
- Conifer Health Solutions, LLC
- Koninklijke Philips N.V.
- Infor, Inc.
Frequently asked questions
Europe Healthcare IT market report covers the market sizes and forecasts for various products, components, delivery modes, end users, and countries. The report also provides the value analysis of various segments and sub-segments of Europe healthcare IT at the country level.
Cite this report
Meticulous Research. (2025). Europe Healthcare IT Market - Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041003). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/europe-healthcare-it-market-5686