Europe Electric Scooter Market (2026-2036)
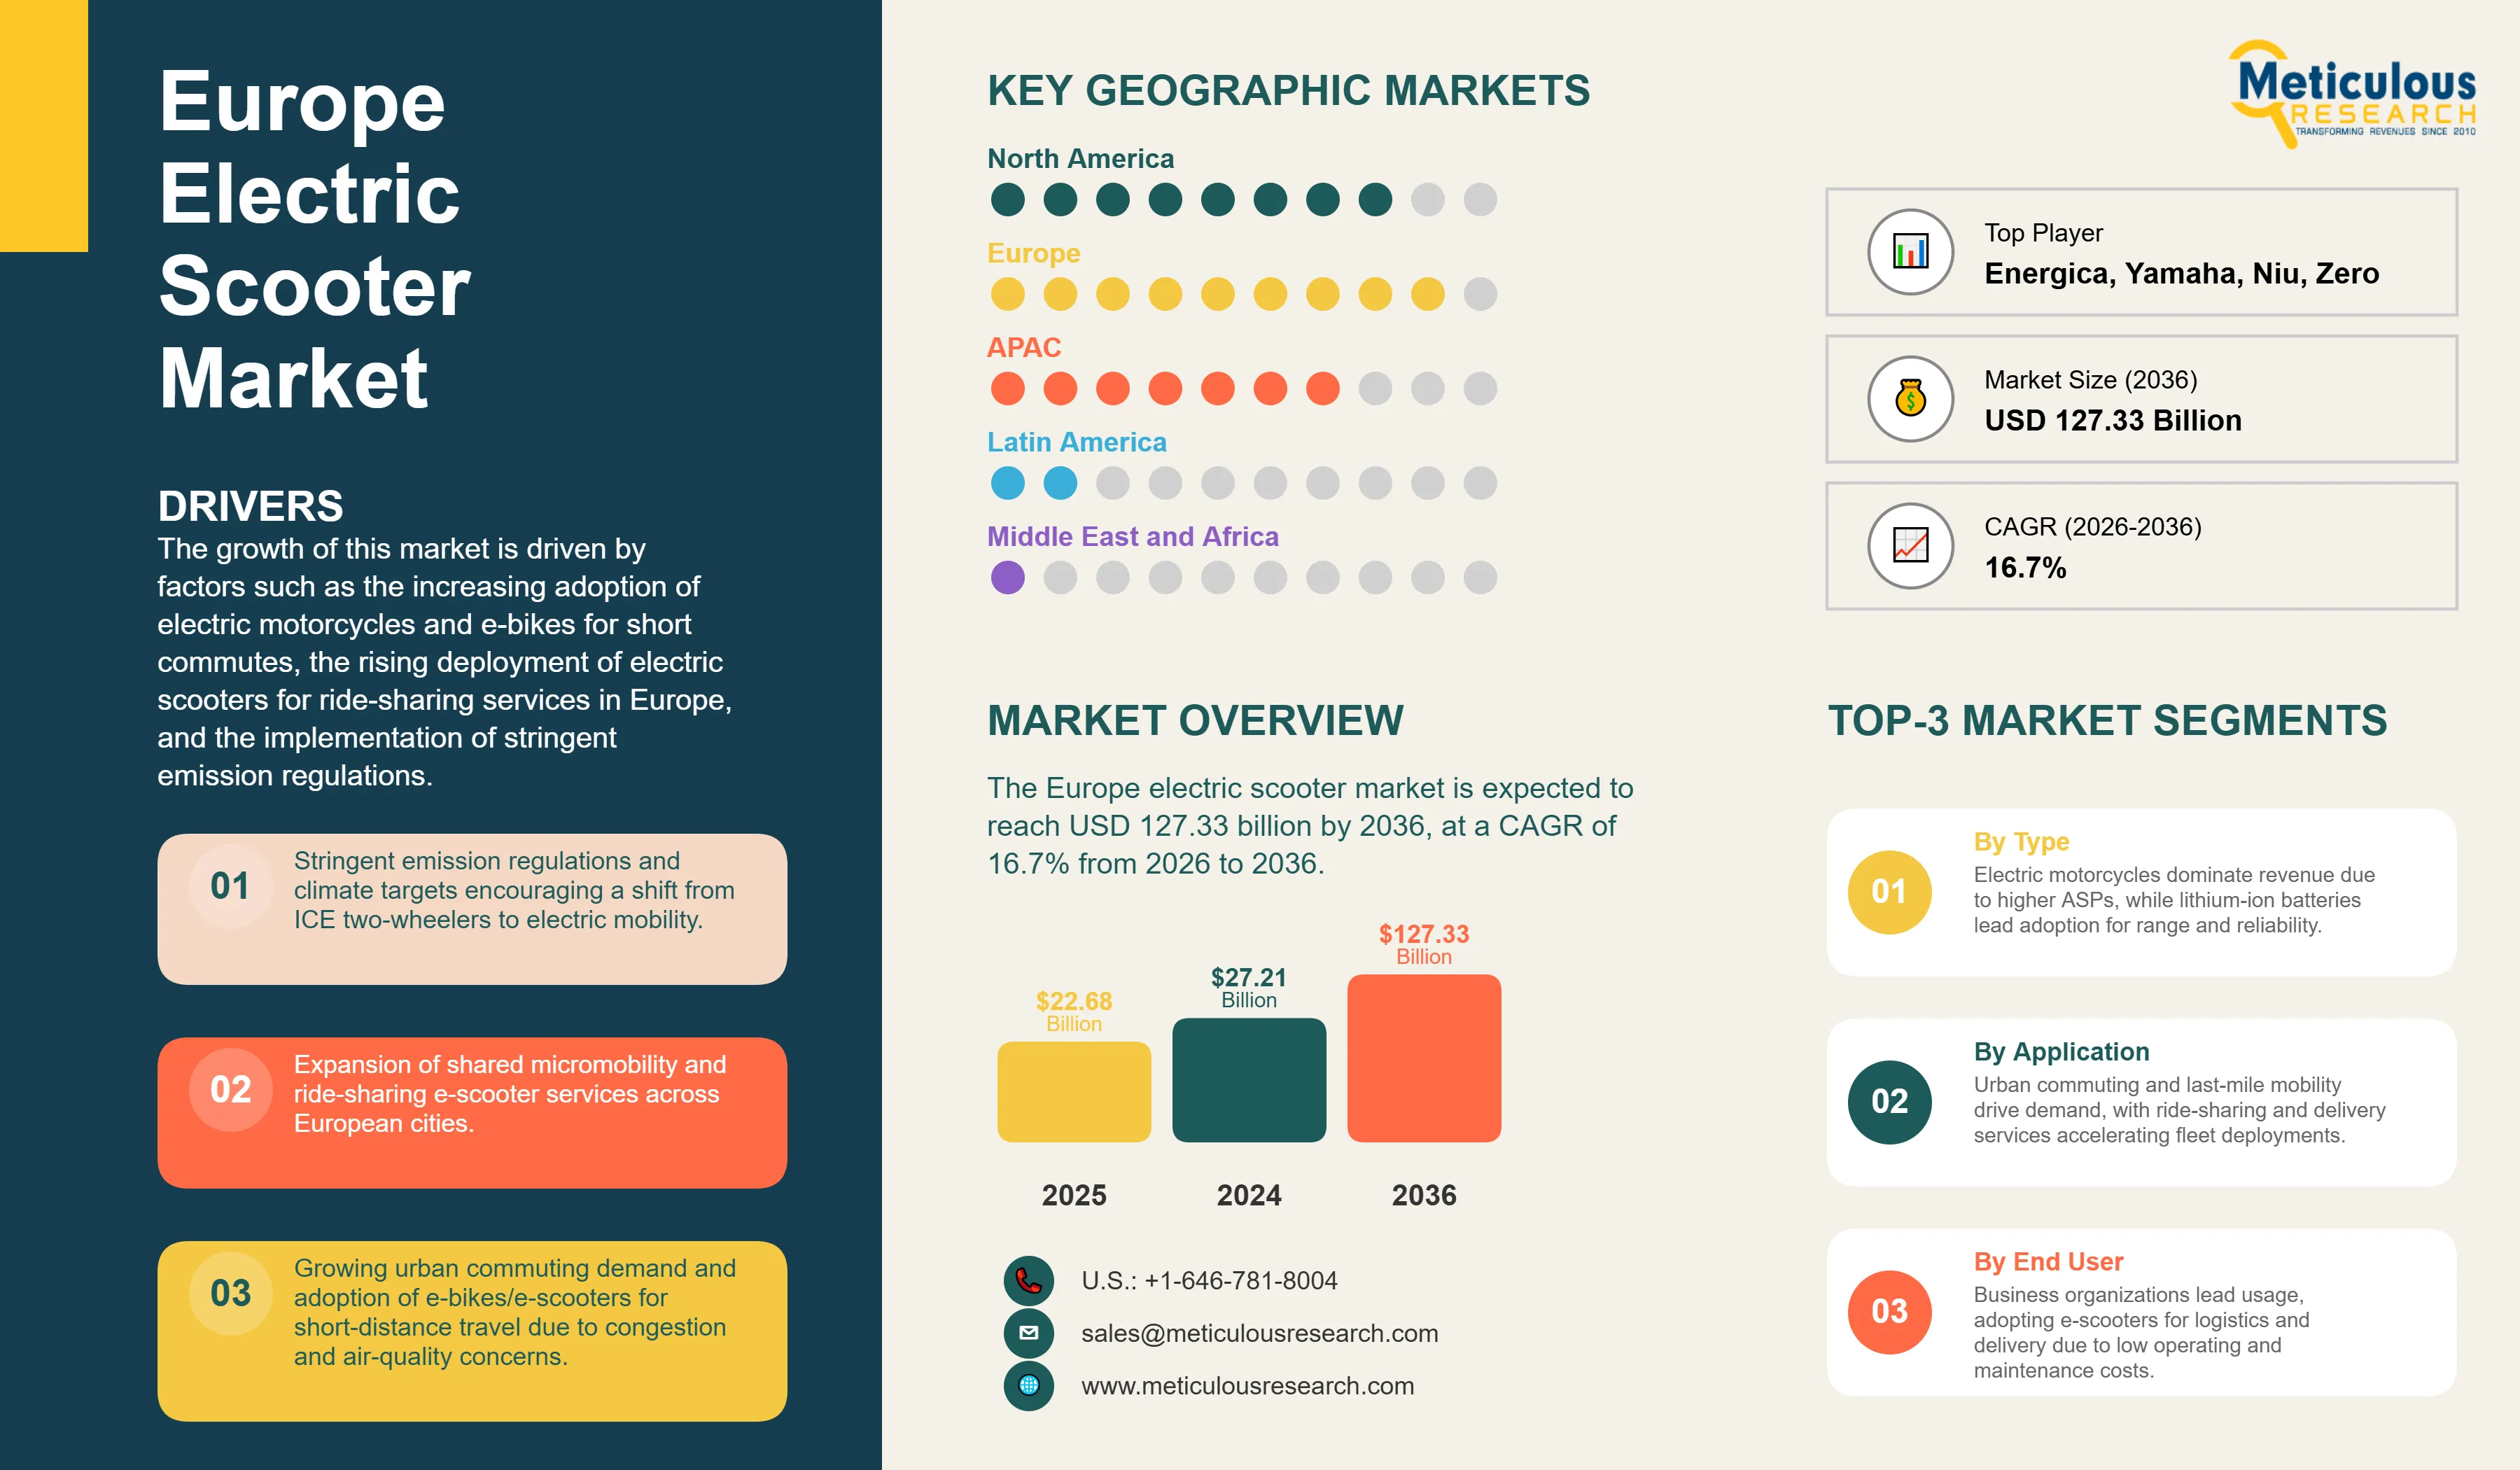
The Europe electric scooters market was valued at USD 22.68 billion in 2025. This market is expected to reach USD 127.33 billion by 2036 from USD 27.21 billion in 2026, at a CAGR of 16.7% from 2026 to 2036. By volume, this market is expected to reach 45.31 million units by 2036 from 10.69 billion in 2026, at a CAGR of 15.5% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 220
- Format
- PDF + Excel
- Report ID
- MRAUTO - 104552
- Base year
- 2025
- 2025 · BASELINE
- $22.68B
- 2036
- $127.3B
- CAGR 2026–2036
- 16.7%
2025 baseline · 2026–2036 forecast at 16.7% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the Europe electric scooter market is projected to reach USD 127.33 billion by 2036, at a CAGR of 16.7% from 2026 to 2036.
By volume, the Europe electric scooter market is projected to reach 45.31 million units by 2036, at a CAGR of 15.5% from 2026 to 2036.
By vehicle type, in 2026, the electric motorcycles segment is expected to account for the largest share of the Europe electric scooter market.
By vehicle type, the electric motorcycles segment is expected to register the highest CAGR during the forecast period.
By power output, in 2026, the less than 3.6 kW segment is expected to account for the largest share of the Europe electric scooter market.
By power output, the 20 kW to 100 kW segment is expected to register the highest CAGR during the forecast period.
By battery technology, in 2026, the lithium-ion battery segment is expected to account for the largest share of the Europe electric scooter market.
By battery technology, the lithium-ion polymer battery segment is expected to register the highest CAGR during the forecast period.
By motor type, in 2026, the hub motors segment is expected to account for the largest share of the Europe electric scooter market.
By end user, in 2026, the business organizations segment is expected to account for the largest share of the Europe electric scooter market.
Hungary is expected to register the highest growth rate among all European countries during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Report Coverage | Details |
| Market Size by 2036 | USD 127.33 Billion |
| Market Volume by 2036 | 45.31 Million Units |
| Revenue CAGR from 2026 to 2036 | 16.7% |
| Format | PDF, Excel & Cloud Portal · 220 pages |
| Volume CAGR from 2026 to 2036 | 15.5% |
| Largest Vehicle Type Segment (2025) | Electric Motorcycles |
| Fastest Growing Power Output Segment | 20 kW to 100 kW |
| Fastest Growing Country | Hungary |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Vehicle Type, Power Output, Battery Technology, Motor Type, Charging Type, End User, and Country |
| Countries Covered | Netherlands, France, Belgium, Spain, Italy, Germany, U.K., Poland, Denmark, Sweden, Norway, Switzerland, Finland, Austria, Croatia, Greece, Slovakia, Romania, Portugal, Hungary, Ireland, Rest of Europe |
Report overview
Segments covered: vehicle type, power output, battery technology, motor type, charging type, end user. Regions: Europe.
The growth of this market is driven by factors such as the increasing adoption of electric motorcycles and e-bikes for short commutes, the rising deployment of electric scooters for ride-sharing services in Europe, and the implementation of stringent emission regulations. Furthermore, rising health awareness among millennials is expected to offer lucrative opportunities for players operating in the Europe electric scooter market. However, the high costs of electric two-wheelers, e-scooters, and bikes and the short lifespan of batteries are expected to restrain the growth of this market. In addition, the lack of regulations in the electric two-wheelers and micromobility space poses a challenge to the growth of this market.
The Europe electric scooter market includes electric two-wheeled vehicles used for personal transportation and shared mobility across the continent, including e-kick scooters and e-bikes suitable for urban short-range commutes, electric mopeds for medium-range urban transport, and electric motorcycles used for both commuting and leisure. The factors such as the ambitious climate neutrality targets of Europe under the European Green Deal, the widespread expansion of urban cycling and micromobility infrastructure, growing consumer awareness of air quality and emissions-related health impacts, and the accelerating maturation of battery technology that is extending range and reducing total cost of ownership for electric two-wheelers are expected to drive the growth of the overall European electric scooters market during the forecast period.
The Europe electric scooter market is one of the most dynamic segments within the broader electric vehicle transition of the continent, driven by the urban mobility transformation, stringent emissions regulations, and rapidly improving electric powertrain technology. The market includes a wide spectrum of electric two-wheeled vehicles: lightweight e-kick scooters and e-bikes used for last-mile connectivity and active commuting, electric mopeds offering speed-assisted urban transport, and fully capable electric motorcycles serving both daily commuting and recreational use cases.
As a form of shared micromobility in cities, e-scooter sharing systems were first introduced in the U.S. in 2017 and arrived in Europe with the first providers entering Paris in 2018. While shared deployments initially accelerated consumer awareness and trial, the broader European electric scooter market, including E-kick Scooters, Electric Mopeds, and Electric Motorcycles for both personal ownership and commercial fleet use, has since evolved amid maturing regulatory frameworks and growing adoption across diverse end-user segments. Following a municipal referendum in April 2023, Paris removed shared e-scooters from its streets in September 2023, reflecting growing municipal scrutiny of free-floating operations; however, private ownership of type-approved electric scooters remains permitted under French national rules, underscoring the structural distinction between shared micromobility services and the personal electric two-wheeler market.
Across Europe, regulatory requirements for electric scooters continue to diverge by jurisdiction: Germany plans to align e-scooter rules with bicycle traffic regulations during 2025; Italy implemented new mandatory helmet and insurance requirements for e-scooter users effective December 2024; and the Netherlands introduced registration, license plate, and liability insurance requirements for type-approved models from July 2025. The EU Motor Insurance Directive, applicable since January 2024, requires third-party liability insurance for electric two-wheelers exceeding 25 km/h design speed or 25 kg weight with speeds above 14 km/h, while lighter personal mobility devices remain subject to national implementation frameworks. Notably, Regulation (EU) 2025/14 on non-road mobile machinery explicitly excludes personal stand-up e-scooters from its scope, meaning type-approval and market access for privately owned units continue to be governed by national frameworks and existing EU product safety directives.
The key players operating in the overall European electric scooter market include manufacturers serving the personal ownership and commercial fleet segments such as Energica Motor Company S.p.A. (Italy), Yamaha Motor Co., Ltd. (Japan), Niu Technologies (China), Govecs AG (Germany), Zero Motorcycles, Inc. (U.S.), and emco electroroller GmbH (Germany), among others. These manufacturers increasingly differentiate through premium performance specifications, design, battery range, and direct-to-consumer digital sales channels, while also supplying fleet-ready units to micromobility service providers.
The Europe electric scooters market was valued at USD 22.68 billion in 2025. This market is expected to reach USD 127.33 billion by 2036 from USD 27.21 billion in 2026, at a CAGR of 16.7% from 2026 to 2036. By volume, this market is expected to reach 45.31 million units by 2036 from 10.69 billion in 2026, at a CAGR of 15.5% from 2026 to 2036.
Report infographic
Market dynamics
2 factors across 1 forceRising Deployment of Electric Scooters for Ride-sharing Services
The rapid growth of shared e-scooter services across European cities has emerged as one of the most significant drivers of market growth across the E-kick Scooter and Electric Moped segments. Shared micromobility companies including Dott (formed through the 2024 merger of TIER and Dott), Voi Technology, Lime, and Bolt have deployed tens of thousands of e-scooters across hundreds of European cities, creating a new urban transportation layer that complements public transit, reduces short-distance car trips, and generates high-frequency utilization that drives repeat procurement of fleet-ready vehicles. Germany is one of the largest shared micromobility markets with an estimated 40,000–60,000 shared e-scooters in operation, while Nordic markets including Denmark, Norway, and Sweden continue to scale deployments amid evolving municipal permitting frameworks. Following Paris's removal of shared e-scooters in September 2023, operators have increasingly focused on markets with stable regulatory environments, including Germany, Italy, Spain, and the Benelux region.
The business model for shared e-scooter services has matured significantly since 2018, shifting from largely unregulated dockless deployments to increasingly regulated franchise-based permit systems that city governments use to control fleet sizes, enforce parking compliance through geofencing, and mandate data sharing with municipal transport authorities. This regulatory maturation is creating more stable and predictable market conditions for both operators and their hardware suppliers, driving higher-quality and longer-lasting vehicle purchases that differ substantially from the first generation of shared e-scooters.
Stringent Emission Regulations and Evolving Two-wheeler Standards
The implementation of stringent vehicle emissions regulations across the European Union is creating incentives for the adoption of electric two-wheelers at the expense of conventional combustion-engine scooters and motorcycles. While the Euro 5 standard for L-category vehicles (including electric mopeds and motorcycles) entered into force for new type approvals in 2020 and for all new registrations in 2021, ongoing national implementations and city-level low-emission policies are effectively driving the transition toward zero-emission alternatives. The EU's Fit for 55 package and proposed Zero Emission Vehicle mandates for urban logistics are further reinforcing policy support for electric two-wheeler adoption across both personal and commercial use cases.
Several major European cities have implemented or expanded low-emission zones (LEZ) and ultra-low emission zones (ULEZ) that restrict or prohibit older combustion-engine vehicles in city centers. London's ULEZ, which expanded to cover all of Greater London in August 2023, directly incentivizes the replacement of non-compliant combustion-engine motorcycles and mopeds with electric alternatives. Similar measures are being implemented or strengthened in Paris, Amsterdam, Brussels, Milan, and Barcelona. These regulatory developments are increasing the replacement cycle of the existing European two-wheeler fleet and creating a substantial addressable market for electric alternatives across the Electric Moped and Electric Motorcycle segments.
Table of contents
15 chapters · 136 sections · 220 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Vehicle Type | Electric Motorcycles | Electric motorcycles |
| By Power Output | Less than 3.6 kW power output | 20 kW |
| By Battery Technology | Lithium-ion Battery Segment Maintain Market | Lithium-ion polymer (LiPo) battery |
| By End User | Business Organizations | Electric scooter market in Hungary |
By Vehicle Type
- The electric motorcycles segment is expected to account for the largest share of the Europe electric scooter market in 2026 by revenue, driven by the higher unit average selling prices of electric motorcycles relative to e-kick scooters and electric mopeds.
- The segment is simultaneously expected to grow at the fastest CAGR during the forecast period.
- The key factors driving the growth of the electric motorcycle market include increasing government policies aimed at promoting electric mobility, growing awareness regarding the need to reduce greenhouse gas emissions, rising gasoline prices that improve the economics of electric alternatives, and stringent Euro 5+ emission norms that raise the cost of compliant ICE motorcycle development.
By Power Output
- The 20 kW to 100 kW power output segment is expected to grow at the fastest CAGR from 2026 to 2036.
- This segment corresponds primarily to electric motorcycles capable of competing with mid-to-large-displacement ICE motorcycles in terms of performance, acceleration, and highway cruising capability.
- The growth of this segment is primarily attributed to the increasing adoption of high-performance electric motorcycles in Europe, the high growth of the electric two-wheelers market in Europe spurred by pandemic-related shifts in mobility preferences, favorable incentives and tax benefits for zero-emission vehicles in multiple European countries, and growing demand for fast and powerful electric two-wheelers among younger consumers.
- The less than 3.6 kW power output segment accounts for the largest share of the overall European market in 2026.
- This segment includes the vast majority of personal consumer e-scooter purchases and shared mobility fleet deployments.
- The 3.6 kW to 7.2 kW segment covers electric mopeds and lightweight electric motorcycles, serving urban commuters who require speeds above the 25 km/h limit of pedelecs but below the highway capability of full-power electric motorcycles.
By Battery Technology
- The lithium-ion battery segment accounts for the largest share of the Europe electric scooter market by battery technology in 2026.
- Lithium-ion batteries offer a well-established combination of energy density, cycle life, safety, and cost that has made them the dominant energy storage technology for electric two-wheelers across all vehicle types and price points.
- The extensive supply chain ecosystem for lithium-ion cells, the availability of standardized charging infrastructure, and the mature battery management system technology that protects lithium-ion packs from overcharge, deep discharge, and thermal events have collectively made lithium-ion the default choice for electric scooter manufacturers.
- However, the lithium-ion polymer (LiPo) battery segment is expected to grow at the fastest CAGR during the forecast period.
- LiPo batteries offer advantages including large capacity, fast charging capabilities, and high power output delivered quickly, making them particularly suitable for applications like e-bikes where immediate power assistance during startup is required.
By End User
- The business organizations segment is expected to account for the largest share of the Europe electric scooter market by end user in 2026.
- Business organizations use e-scooters primarily for logistics, courier, and delivery services, representing a high-volume, commercially-driven demand center that purchases or leases vehicles in fleet quantities with defined performance and reliability requirements.
- Companies such as emco electroroller GmbH provide delivery e-scooters supplemented with practical transport boxes for pizza services, pharmacies, florists, and craftsmen.
- The benefits of using e-scooters for urban delivery include the ability to deliver in sensitive pedestrianized areas without noise pollution, significantly lower fuel and maintenance operating costs compared to conventional delivery motorcycles, and positive environmental credentials that align with corporate sustainability commitments.
- The micromobility service providers segment is a significant and rapidly growing end user category, driven by the ongoing expansion of shared e-scooter fleets across European cities.
- The individuals segment is also growing as improving price-to-performance ratios and growing product awareness drive personal purchase decisions, particularly in the e-bike and electric motorcycle categories.
- Hungary Electric Scooter Market Size and Growth 2026 to 2036
- The electric scooter market in Hungary is expected to register the highest growth rate among all European countries during the forecast period.
- The growth of this market is attributed to growing consumer interest in electric vehicles and micromobility solutions, the increasing number of projects undertaken by companies operating in the electric mobility industry, and growing government support for enhancing EV sales across the country.
- Hungary's government has introduced subsidy programs for electric vehicle purchases, developed national EV charging infrastructure, and set ambitious targets for electrification of the transport sector as part of its commitments under EU climate and energy policy frameworks.
- Key Electric Scooter Markets in Europe
- The Netherlands, Germany, France, and Belgium are the largest and most mature individual country markets within the Europe electric scooter market, driven by extensive cycling infrastructure, well-established micromobility sharing ecosystems, and high consumer awareness of and receptiveness to electric two-wheelers.
- Italy and Spain are significant markets for electric mopeds and low-power electric motorcycles, reflecting the established scooter culture in Southern European urban environments.
- The Nordic countries are among the highest per-capita adoption markets for e-bikes, driven by national subsidy programs, flat terrain suitable for cycling, and high environmental awareness among the population.
- Central and Eastern European markets, including Poland, Romania, Slovakia, Croatia, and Hungary, are the fastest-growing country group within the Europe electric scooter market, driven by rapidly rising urban incomes, growing consumer awareness of electric mobility, expanding EV incentive programs supported by EU cohesion funding, and the deployment of shared micromobility services by major European operators expanding into new geographies
Geographic analysis
Europe
In terms of revenue, the Europe electric scooter market is projected to reach USD 127.33 billion by 2036, at a CAGR of 16.7% from 2026 to 2036. The Europe electric scooter market includes electric two-wheeled vehicles used for personal transportation and shared mobility across the continent, including e-kick scooters and e-bikes suitable for urban short-range commutes, electric mopeds for medium-range urban transport, and electric motorcycles used for both commuting and leisure. The Europe electric scooter market is one of the most dynamic segments within the broader electric vehicle transition of the continent, driven by the urban mobility transformation, stringent emissions regulations, and rapidly improving electric powertrain technology. Across Europe, regulatory requirements for electric scooters continue to diverge by jurisdiction: Germany plans to align e-scooter rules with bicycle traffic regulations during 2025; Italy implemented new mandatory helmet and insurance requirements for e-scooter users effective December 2024; and the Netherlands introduced registration, license plate, and liability insurance requirements for type-approved models from July 2025. The Europe electric scooters market was valued at USD 22.68 billion in 2025.
Frequently asked questions
The Europe electric scooter market report provides insights into the market based on vehicle type, power output, battery technology, motor type, charging type, end user, and country. The study also evaluates industry competitors and analyses the country-level markets.
Cite this report
Meticulous Research. (2026). Europe Electric Scooter Market - Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MRAUTO - 104552). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/europe-electric-scooter-market-5239