Dental 3D Printing Market (2026-2036)
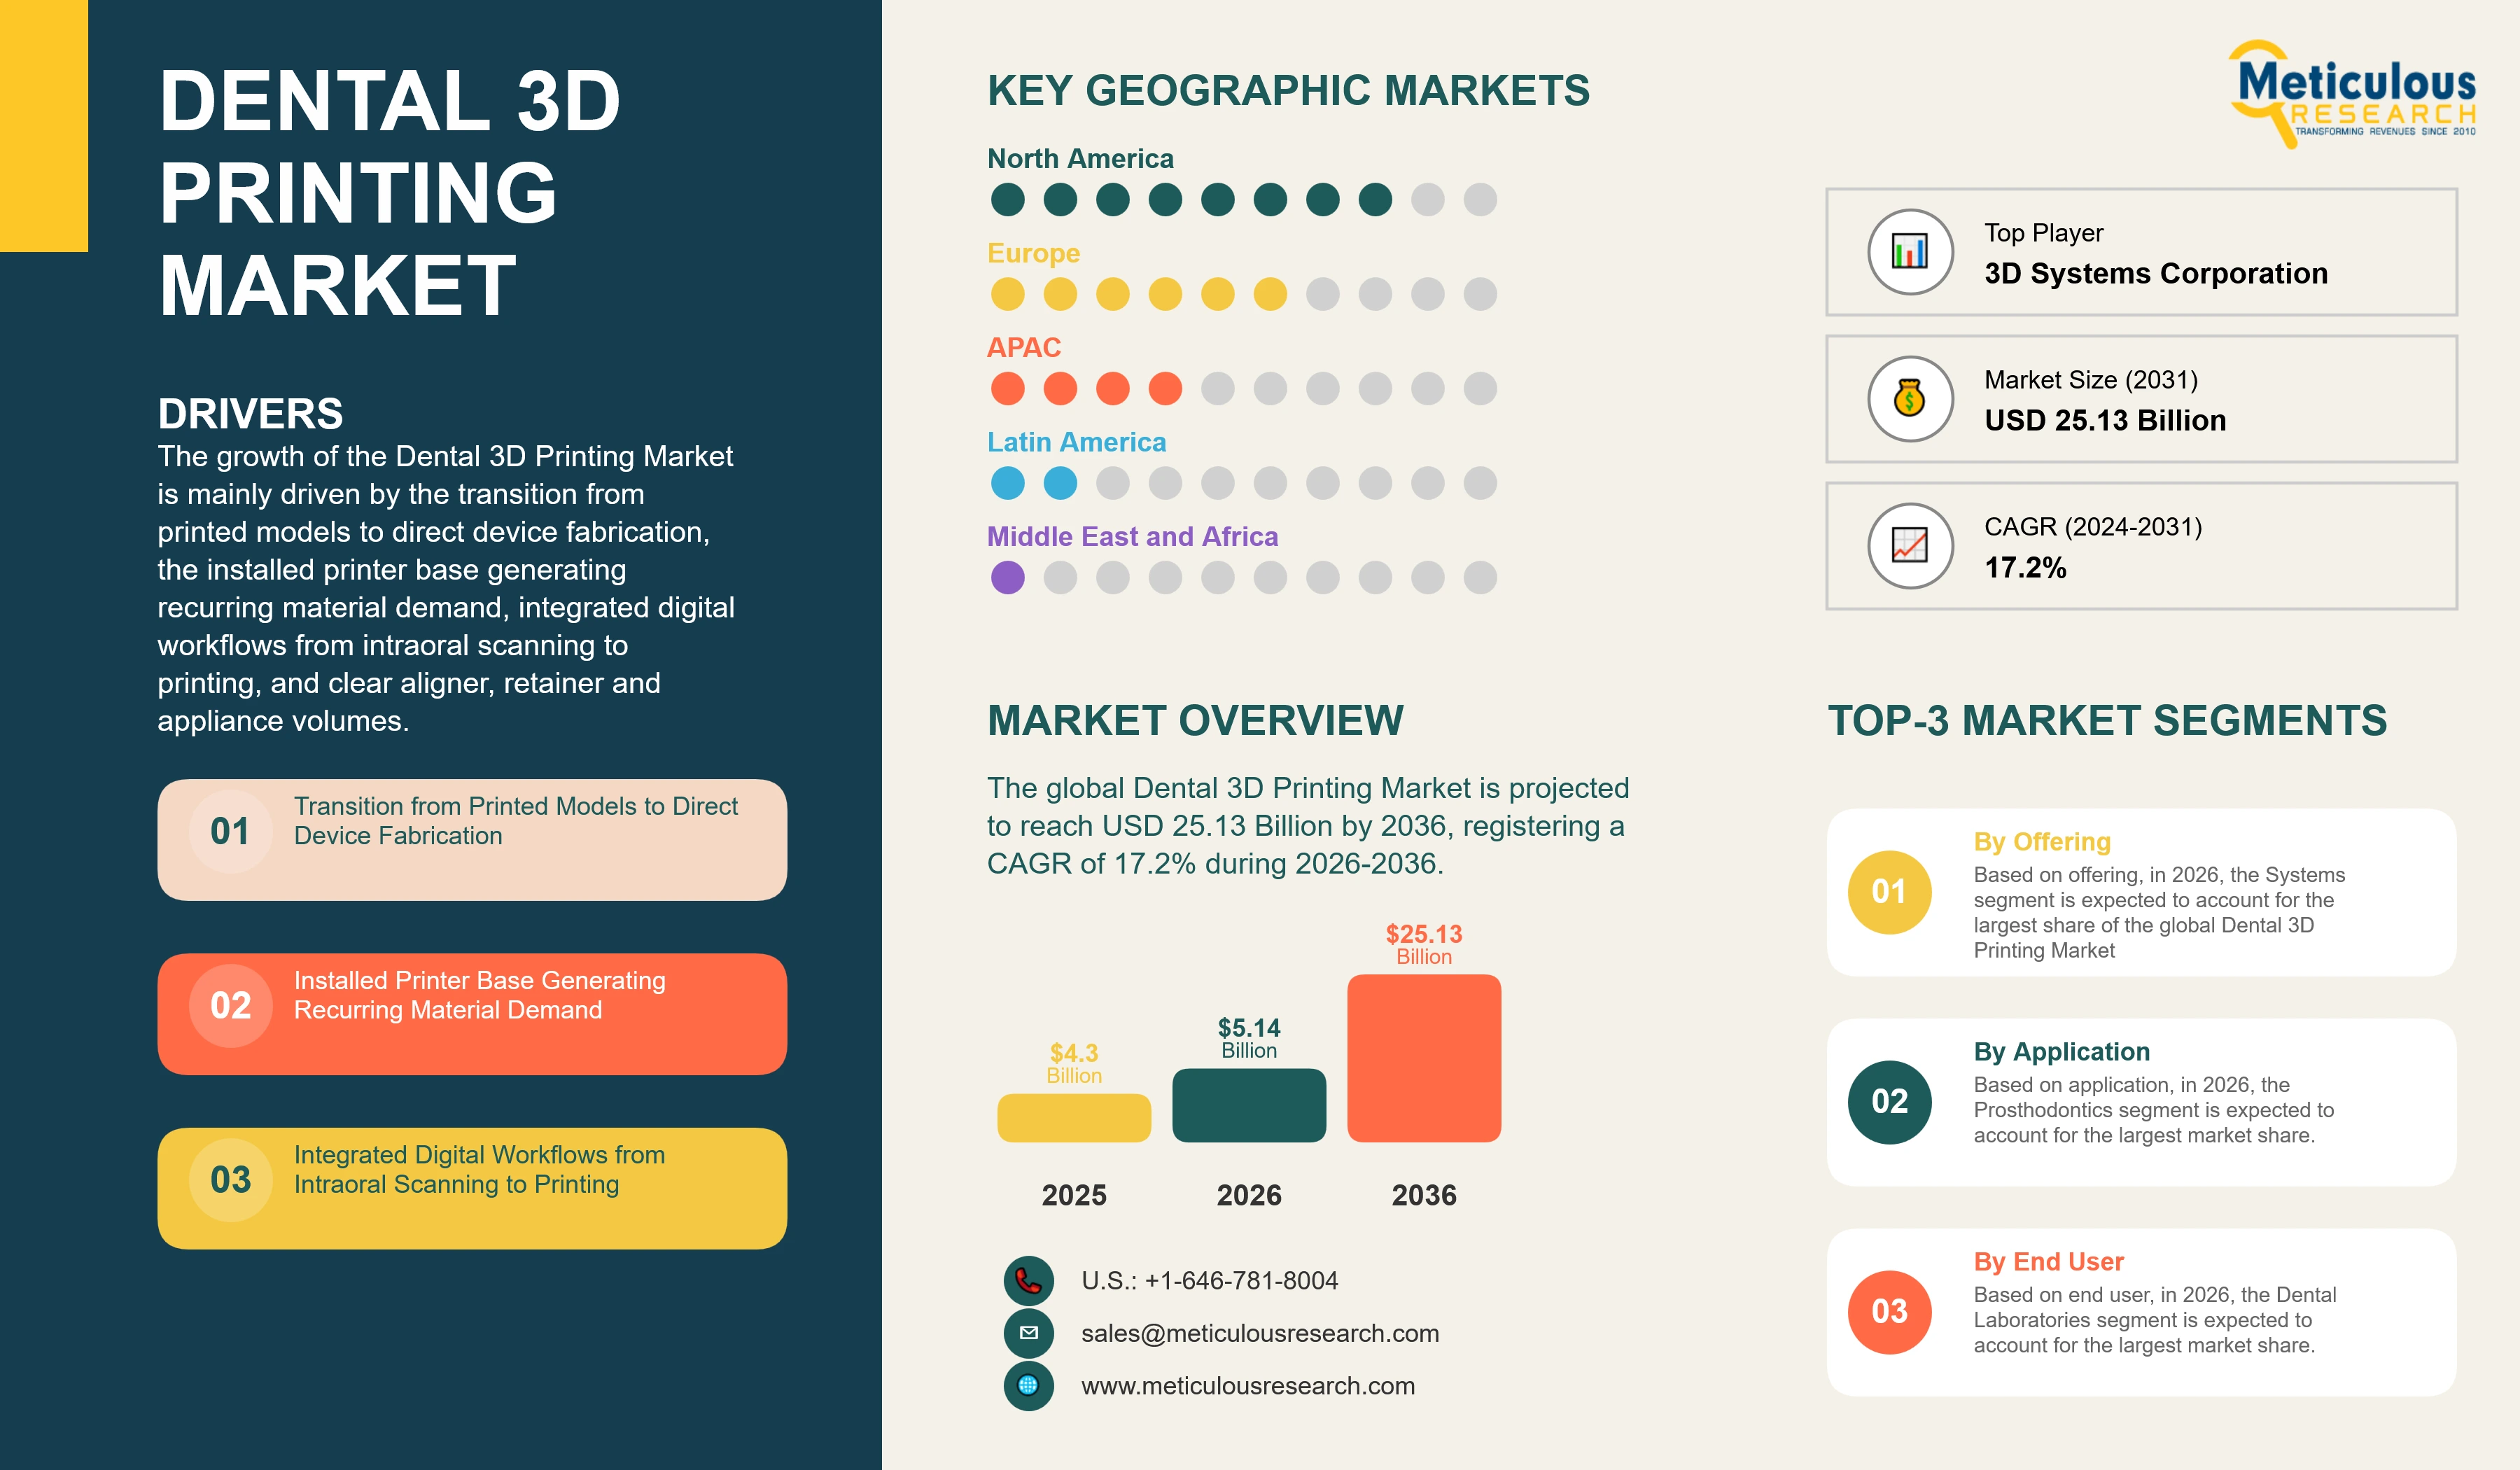
The global Dental 3D Printing Market was valued at USD 4.30 billion in 2025. This market is expected to reach USD 25.13 billion by 2036 from an estimated USD 5.14 billion in 2026, registering a CAGR of 17.2% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 175
- Format
- PDF + Excel
- Report ID
- MRHC - 104803
- Base year
- 2025
- 2025 · BASELINE
- $4.30B
- 2036
- $25.13B
- CAGR 2026–2036
- 17.2%
2025 baseline · 2026–2036 forecast at 17.2% CAGR · hover a bar for the value
Key highlights
The global Dental 3D Printing Market is projected to reach USD 25.13 billion by 2036, driven by the transition to direct device fabrication, the installed printer base generating recurring resin demand, integrated digital workflows and clear aligner volumes.
Materials are growing while equipment is not. For the second quarter of 2026, reported on 13 August 2026, Stratasys Ltd. recorded total revenue of USD 137.6 million against USD 138.1 million a year earlier, with products revenue of USD 92.7 million against USD 94.8 million, services revenue of USD 44.9 million against USD 43.3 million, and record quarterly consumables revenue of USD 66.3 million.
Equipment-led revenue has flattened at the listed system suppliers. Stratasys reported a GAAP gross margin of 42.3% against 43.1% a year earlier and a non-GAAP gross margin of 47.2% against 47.7%, and reaffirmed full-year 2026 revenue guidance of USD 565 million to USD 575 million with adjusted EBITDA of USD 25 million to USD 30 million.
Direct fabrication is the decisive transition and it is not yet margin-neutral. At an investor conference in May 2026, Align Technology stated that direct fabrication is dilutive to gross margins in the current year and is expected to become more neutral as volume scales, that reaching more than 10% to 15% of volume in directly fabricated products could offset the initial margin drag, and that its principal focus is scaling resin and manufacturing processes.
The sequence and the gating condition are stated. Align Technology described a rollout sequence beginning with attachments and specialty retainers, followed by broader retention products and then aligners, with direct fabrication of aligners requiring approval from the United States Food and Drug Administration, which the company stated it is pursuing and for which biocompatibility requirements are well along.
Digital dentistry demand itself remains strong. For the first half of 2026, reported on 19 August 2026, Straumann Holding AG recorded revenue from continuing operations of CHF 1,379.5 million with organic growth of 7.8%, and second-quarter revenue of CHF 707.0 million with organic growth of 8.5%, delivering a core EBIT margin of 26.9% at constant 2025 exchange rates.
Scanning and milling continue to attract investment alongside printing. Straumann Holding AG reported double-digit growth in digital solutions in North America and Latin America with strong growth in Asia-Pacific, strong intraoral scanner sales led by the SIRIOS X3, and a one-off charge relating to a CNC milling technology upgrade that affected gross profit, while iEXCEL accounted for close to 40% of premium implant volumes in the first half.
North America is expected to account for the largest market share in 2026, while Asia-Pacific is projected to register the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 17.2% |
| Format | PDF, Excel & Cloud Portal · 175 pages |
| Market Size (Value) in 2026 | USD 5.14 Billion |
| Market Size (Value) in 2036 | USD 25.13 Billion |
| Segments Covered | By Offering: Systems (By Type: Dental 3D Printers [Metal, Ceramic, Polymer], Dental 3D Scanners; By Technology: Vat Photopolymerization, PolyJet, Fused Deposition Modeling, Selective Laser Sintering, Other Technologies), Materials (Dental Polymers [Resins, Thermoplastics, Other Polymers], Metals, Composites, Ceramics [Zirconia, Alumina, Other Ceramics]), Services, Accessories. By Application: Prosthodontics, Orthodontics, Implantology, Other Applications (Surgical Guides, Anatomical Replicas & Models, Casting Patterns). By End User: Dental Laboratories, Dental Hospitals & Clinics, Academic & Research Institutes. |
| Countries Covered | North America: U.S., Canada. Europe: Germany, France, U.K., Spain, Italy, Switzerland, Sweden, Netherlands, Rest of Europe. Asia-Pacific: China, Japan, India, Australia, South Korea, Rest of Asia-Pacific. Latin America: Brazil, Mexico, Rest of Latin America. Middle East & Africa. |
| Key Companies | 3D Systems Corporation, Stratasys Ltd., Dentsply Sirona Inc., Straumann Holding AG, Align Technology, Inc., SprintRay Inc., Formlabs Inc., Carbon, Inc., Asiga, Rapid Shape GmbH, DWS S.r.l., Ivoclar Vivadent AG, BEGO GmbH & Co. KG, Kulzer GmbH, GC Corporation, Keystone Industries, 3M Company, and Shandong Huge Dental Material Corporation. |
Report overview
Segments covered: offering, technology, material, application, end user.
The growth of this market is mainly driven by the transition from printing models and moulds toward direct fabrication of the finished dental device, which multiplies the quantity of material consumed per case; the installed base of chairside and laboratory printers that has accumulated over successive equipment cycles and now generates recurring resin demand; the integration of intraoral scanning, design software and printing into a single digital workflow that removes impression taking and manual model work; and the growth of clear aligner and retainer volumes, which are produced in quantities no conventional laboratory process can match.
In addition, the qualification of printable resins for intraoral use as finished appliances, the shift of production from centralised laboratories toward the point of care, and the extension of printing from polymers into ceramics and metals for definitive restorations are further supporting the growth of this market. The composition of that growth is shifting from equipment toward materials, which is where recurring revenue in this market now accumulates.
The Dental 3D Printing Market comprises the systems, materials, services and accessories through which dental devices and the intermediate parts used to make them are produced by additive manufacturing. The market includes dental 3D printers configured for polymer, ceramic and metal fabrication, the dental 3D scanners that capture the intraoral or model geometry on which printing depends, the printable materials comprising dental polymers, metals, composites and ceramics, the printing and design services supplied by laboratories and service bureaux, and the accessories, post-processing equipment and consumable components that complete a workflow. The market ecosystem extends from resin and powder formulators, printer manufacturers and software developers through dental laboratories, group practices and service providers to dentists, orthodontists, prosthodontists and oral surgeons, and the regulatory authorities whose clearance determines whether a printed object may be placed in a patient.
The development that matters most in this market is the move from indirect to direct fabrication. For most of the history of dental additive manufacturing, the printed object was a model, a mould or a casting pattern from which the appliance was subsequently thermoformed, pressed or cast, which meant that printing substituted for a laboratory step rather than for the device itself. Printing the finished appliance changes both the quantity of material consumed per case and the regulatory basis on which it is supplied.
The economics of that transition are now disclosed rather than inferred. At an investor conference in May 2026, Align Technology stated that direct fabrication is dilutive to gross margins in the current year and is expected to become more neutral as volume scales, that reaching more than 10% to 15% of volume in directly fabricated products could offset the initial margin drag, and that its principal focus is scaling resin and manufacturing processes. A statement that direct fabrication is currently margin-dilutive, with a stated volume threshold of more than 10% to 15% at which the drag is offset, establishes that this transition is a scale problem rather than a capability problem, and it identifies resin and process scale-up rather than printer performance as the constraint.
The sequence in which the transition is being made is equally informative. Align Technology described a rollout sequence beginning with attachments and specialty retainers, followed by broader retention products and then aligners, with direct fabrication of aligners requiring approval from the United States Food and Drug Administration, which the company stated it is pursuing and for which biocompatibility requirements are well along. Beginning with attachments and specialty retainers, progressing to broader retention products and only then to aligners, with regulatory approval required for the final step, describes a graduated path in which the simplest devices and the least demanding regulatory classifications are addressed first. Any assessment of this market that assumes direct fabrication of the principal appliance within the near term misreads both the engineering and the regulatory position.
Meanwhile the equipment side of this market has stopped growing at the listed suppliers. For the second quarter of 2026, reported on 13 August 2026, Stratasys Ltd. recorded total revenue of USD 137.6 million against USD 138.1 million a year earlier, with products revenue of USD 92.7 million against USD 94.8 million, services revenue of USD 44.9 million against USD 43.3 million, and record quarterly consumables revenue of USD 66.3 million. Total revenue broadly flat, products revenue down against a year earlier and consumables revenue at a record in the same quarter is the clearest available evidence that demand has shifted from the printer to the resin, and it is the pattern that an installed base reaching maturity produces.
Profitability has tightened along with that mix. Stratasys reported a GAAP gross margin of 42.3% against 43.1% a year earlier and a non-GAAP gross margin of 47.2% against 47.7%, and reaffirmed full-year 2026 revenue guidance of USD 565 million to USD 575 million with adjusted EBITDA of USD 25 million to USD 30 million. Gross margin lower on both measures and full-year guidance implying revenue close to the prior year indicate that the equipment market is being served from an installed base that is replaced rather than expanded, and that the growth in this market is accruing to whoever supplies the material consumed by printers already in place.
That mix shift is the central commercial fact for suppliers. A printer is purchased once and amortised over several years, while a resin is purchased for every case, so a market transitioning from indirect to direct fabrication consumes materially more material per printer installed. The suppliers positioned for this are those holding qualified resin formulations and the regulatory clearances attached to them, rather than those whose revenue depends on placing new hardware.
Demand for digital dentistry as a whole remains robust, which distinguishes the equipment slowdown from a demand problem. For the first half of 2026, reported on 19 August 2026, Straumann Holding AG recorded revenue from continuing operations of CHF 1,379.5 million with organic growth of 7.8%, and second-quarter revenue of CHF 707.0 million with organic growth of 8.5%, delivering a core EBIT margin of 26.9% at constant 2025 exchange rates. Organic growth approaching 8% with a core EBIT margin near 27% at the largest implant and digital dentistry group indicates that practices and laboratories continue to invest in digital workflows, and that the flattening of printer revenue reflects the maturity of the installed base rather than any reduction in clinical adoption.
The same disclosure also qualifies the assumption that printing is displacing subtractive manufacture. Straumann Holding AG reported double-digit growth in digital solutions in North America and Latin America with strong growth in Asia-Pacific, strong intraoral scanner sales led by the SIRIOS X3, and a one-off charge relating to a CNC milling technology upgrade that affected gross profit, while iEXCEL accounted for close to 40% of premium implant volumes in the first half. Strong intraoral scanner sales alongside a charge relating to a CNC milling technology upgrade shows that milling continues to attract capital investment in parallel with printing, which is consistent with clinical practice, since zirconia and lithium disilicate restorations are still predominantly milled while printing dominates models, guides, trays, dentures and retainers.
The market includes printer and system manufacturers, dental materials companies, dental groups and clear aligner producers, among them 3D Systems, Stratasys, Dentsply Sirona, Straumann Holding, Align Technology, SprintRay, Formlabs, Carbon, Asiga, Rapid Shape, DWS, Ivoclar Vivadent, BEGO, Kulzer, GC Corporation, Keystone Industries, 3M and Shandong Huge Dental Material. Participants compete on regulatory clearance of printable materials for their intended intraoral use, accuracy and dimensional stability through printing and post-processing, throughput and cost per unit at laboratory and chairside scale, validation of the complete workflow from scan to finished device, breadth of qualified material portfolio on a given platform, and the service, training and support that determine whether a practice uses an installed printer.
At the same time, the market faces challenges, including the regulatory burden attached to materials placed in the mouth as definitive devices; the margin dilution that direct fabrication carries until volume is achieved; the dependence of printed accuracy on post-processing steps that are difficult to control outside a laboratory; the underutilisation of printers installed in practices without the workflow or trained staff to use them; and the persistence of milling for the highest-strength ceramic restorations. As a result, suppliers combining cleared material portfolios, validated end-to-end workflows and recurring resin revenue are expected to capture the largest share of growth over the forecast period.
Report infographic
Market dynamics
15 factors across 5 forcesTransition from Printed Models to Direct Device Fabrication
The transition from printed models to direct device fabrication is a major factor driving the Dental 3D Printing Market, because it changes what is printed and therefore how much material each case consumes. Printing a model from which an appliance is thermoformed uses material once for a tool that is then discarded, whereas printing the appliance itself places the printed object in the patient and consumes qualified material for every unit delivered.
The transition is under way at scale and its economics are stated. At an investor conference in May 2026, Align Technology stated that direct fabrication is dilutive to gross margins in the current year and is expected to become more neutral as volume scales, that reaching more than 10% to 15% of volume in directly fabricated products could offset the initial margin drag, and that its principal focus is scaling resin and manufacturing processes. A volume threshold of more than 10% to 15% of directly fabricated products, identified as the point at which initial margin dilution is offset, indicates both the seriousness of the commitment and the magnitude of the material volume that this market will absorb as that threshold is approached.
Installed Printer Base Generating Recurring Material Demand
The installed printer base generating recurring material demand is significantly driving market growth, and it is now the principal source of revenue expansion in this market. Printers placed in laboratories and practices across successive equipment cycles consume resin for every case produced, so material demand accumulates with utilisation rather than with new placements.
The effect is visible in supplier reporting. For the second quarter of 2026, reported on 13 August 2026, Stratasys Ltd. recorded total revenue of USD 137.6 million against USD 138.1 million a year earlier, with products revenue of USD 92.7 million against USD 94.8 million, services revenue of USD 44.9 million against USD 43.3 million, and record quarterly consumables revenue of USD 66.3 million. Record consumables revenue recorded in a quarter in which products revenue declined against a year earlier demonstrates that the growth in this market is being generated by printers already installed, and it means that material portfolio breadth and clearance status now matter more to a supplier than hardware placement volume.
Integrated Digital Workflows from Intraoral Scanning to Printing
Integrated digital workflows from intraoral scanning to printing are an important driver because printing cannot be adopted without the digital geometry that precedes it. An intraoral scan removes physical impression taking, design software converts that scan into a manufacturable file, and printing produces the model, guide, tray or appliance without the manual model work that previously connected the two.
Investment in the upstream part of that workflow continues to be strong. Straumann Holding AG reported double-digit growth in digital solutions in North America and Latin America with strong growth in Asia-Pacific, strong intraoral scanner sales led by the SIRIOS X3, and a one-off charge relating to a CNC milling technology upgrade that affected gross profit, while iEXCEL accounted for close to 40% of premium implant volumes in the first half. Strong intraoral scanner sales and double-digit growth in digital solutions across North America and Latin America establish that the scanning base from which printing demand arises is still expanding, and each additional scanner installed enlarges the population of practices for which chairside or laboratory printing becomes practical.
Clear Aligner, Retainer and Appliance Volumes
Clear aligner, retainer and appliance volumes support market growth by creating production quantities that no conventional laboratory process can serve. Each aligner case requires a series of individually shaped appliances, retainers are replaced periodically, and the resulting unit counts are produced through mass additive manufacturing rather than through bench work.
That volume is also the route through which direct fabrication reaches scale. Align Technology described a rollout sequence beginning with attachments and specialty retainers, followed by broader retention products and then aligners, with direct fabrication of aligners requiring approval from the United States Food and Drug Administration, which the company stated it is pursuing and for which biocompatibility requirements are well along. A rollout beginning with attachments and specialty retainers and progressing through retention products to aligners places the highest-volume product category at the end of the sequence, which means the material demand associated with direct fabrication grows through the forecast period rather than arriving at its start.
Table of contents
11 chapters · 158 sections · 175 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Offering | Systems | Materials |
| By Technology | Dental 3D Printers | Large share and rapid growth of this |
| By Material | Dental Polymers | Large share and rapid growth of this |
| By Application | Prosthodontics | Orthodontics |
| By End User | Dental Laboratories | Dental Hospitals & Clinics |
By Offering
- Dental 3D Printing Market Analysis by Offering
- Systems are further segmented by type into Dental 3D Printers, comprising Metal, Ceramic and Polymer printers, and Dental 3D Scanners, and by technology into Vat Photopolymerization, PolyJet, Fused Deposition Modeling, Selective Laser Sintering, and Other Technologies.
- Materials are further segmented into Dental Polymers, comprising Resins, Thermoplastics and Other Polymers, Metals, Composites, and Ceramics, comprising Zirconia, Alumina and Other Ceramics.
- The Systems segment is expected to account for the largest share of the global Dental 3D Printing Market.
- The large share of this segment is mainly due to the capital value of printers and scanners relative to the material consumed per case, the continuing placement of chairside units into practices holding intraoral scanners, and the inclusion of scanning hardware whose sales remain strong, led by new intraoral scanner platforms.
- However, the Materials segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the consumption of material in every case produced on an installed printer rather than only at the point of placement, and to the transition toward direct fabrication, which places the printed object in the patient and raises qualified material consumption per case.
- Record quarterly consumables revenue of USD 66.3 million reported alongside a decline in products revenue to USD 92.7 million at a leading system supplier in the second quarter of 2026 illustrates the mix shift under way.
- The Services segment is also expected to grow strongly as group practices consolidate production, while Accessories grow with the installed base and its post-processing requirements.
By Technology
- Dental 3D Printing Market Analysis by System Type and Technology
- Within systems, Dental 3D Printers are expected to account for the largest share in 2026, and within printers the Polymer category is expected to account for the largest share, reflecting the dominance of resin-based production of models, surgical guides, trays, splints, denture bases and retainers, which constitute the great majority of printed dental output.
- The Vat Photopolymerization segment is expected to account for the largest share of the market in 2026, and it is also projected to register the higher growth rate during the forecast period.
- The large share and rapid growth of this segment are mainly due to the surface finish and accuracy that layer-wise photopolymerisation delivers at the dimensional tolerances dentistry requires, the low capital cost of digital light processing and liquid crystal display engines that has made chairside placement viable, the breadth of dental resins qualified on these platforms, and the suitability of the process to the small build volumes that dental devices require.
- The PolyJet segment is expected to retain a position in multi-material models and anatomical replicas where simultaneous deposition of materials with different properties is valuable, while Selective Laser Sintering is expected to grow in metal frameworks and partial denture structures, and Fused Deposition Modeling is expected to remain confined to thermoplastic aids and non-definitive applications where surface finish requirements are lower.
By Material
- Dental 3D Printing Market Analysis by Material
- Within materials, the Dental Polymers segment is expected to account for the largest share of the market in 2026, and it is also projected to register the higher growth rate during the forecast period.
- The large share and rapid growth of this segment are mainly due to the use of resins across the full range of printed dental output, the qualification of resin formulations for intraoral use as denture bases, denture teeth, splints, trays and retainers, and the position of resin as the material consumed when printing substitutes directly for a laboratory-made appliance.
- Within polymers, Resins are expected to account for the largest share, with Thermoplastics and Other Polymers including polycarbonate, acrylonitrile butadiene styrene, polyether ether ketone and nylon serving structural and specialist applications.
- The Ceramics segment is expected to grow strongly from a smaller base, with Zirconia accounting for the largest share within it, as printed ceramic processes advance toward the strength, fit and translucency that definitive restorations require and offer material utilisation far higher than milling from a blank.
- The Metals segment is expected to grow steadily in frameworks and partial denture structures where casting remains labour intensive, and the Composites segment is expected to grow in provisional and definitive restorative applications as filled resin systems are qualified.
By Application
- Dental 3D Printing Market Analysis by Application
- The Prosthodontics segment is expected to account for the largest share of the global Dental 3D Printing Market.
- The large share of this segment is mainly due to the production of denture bases, denture teeth, provisional and definitive crowns, bridges and the models on which they are constructed, the volume of removable and fixed prosthetic work undertaken in dental laboratories, and the maturity of resin formulations qualified for these indications.
- However, the Orthodontics segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to clear aligner and retainer volumes that no conventional laboratory process can serve, and to the transition from thermoforming over printed models toward direct fabrication of the appliance itself.
- A rollout sequence beginning with attachments and specialty retainers, progressing to broader retention products and then to aligners subject to regulatory approval, indicates that orthodontic material consumption will increase progressively through the forecast period.
- The Implantology segment is expected to grow strongly on surgical guide production and on printed frameworks for implant-supported prostheses.
By End User
- Dental 3D Printing Market Analysis by End User
- The Dental Laboratories segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the concentration of prosthetic and orthodontic production in laboratories, the standardised post-processing equipment and trained technicians on which printed accuracy depends, and the utilisation levels that justify higher capital equipment and a broad qualified material inventory.
- However, the Dental Hospitals & Clinics segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to chairside production of surgical guides, splints, provisional restorations and retainers within a single appointment, to the growing installed base of intraoral scanners that supplies the digital geometry chairside printing requires, and to the retention of margin that was previously paid to a laboratory.
- Realising that growth depends on validated workflows and trained staff, without which an installed printer generates no material consumption.
- The Academic & Research Institutes segment is expected to grow steadily, supporting material qualification, workflow validation and clinical training.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global Dental 3D Printing Market. The large share of this region is mainly attributed to the concentration of clear aligner production and of direct fabrication development, the scale of group practice and corporate dental organisations that consolidate digital production, high per capita spending on elective and cosmetic dentistry, the regulatory pathway through which printed intraoral devices are cleared, and the presence of 3D Systems, Dentsply Sirona, Align Technology, SprintRay, Formlabs, Carbon, Keystone Industries and 3M. At an investor conference in May 2026, Align Technology stated that direct fabrication is dilutive to gross margins in the current year and is expected to become more neutral as volume scales, that reaching more than 10% to 15% of volume in directly fabricated products could offset the initial margin drag, and that its principal focus is scaling resin and manufacturing processes.
Europe
Europe is expected to account for the second largest share of the market, supported by a dense laboratory sector, early adoption of digital workflows in Germany, Switzerland and the Nordic countries, established dental materials companies and printer manufacturers, and the presence of Straumann Holding, Ivoclar Vivadent, BEGO, Kulzer, Rapid Shape, DWS and Stratasys through its European operations. For the first half of 2026, reported on 19 August 2026, Straumann Holding AG recorded revenue from continuing operations of CHF 1,379.5 million with organic growth of 7.8%, and second-quarter revenue of CHF 707.0 million with organic growth of 8.5%, delivering a core EBIT margin of 26.9% at constant 2025 exchange rates. Straumann Holding AG reported double-digit growth in digital solutions in North America and Latin America with strong growth in Asia-Pacific, strong intraoral scanner sales led by the SIRIOS X3, and a one-off charge relating to a CNC milling technology upgrade that affected gross profit, while iEXCEL accounted for close to 40% of premium implant volumes in the first half.
Asia-Pacific
Fastest growthAsia-Pacific is projected to register the highest CAGR during the forecast period. The growth of this region is driven by the expansion of private dental care in China, India and Southeast Asia, the scale of laboratory production undertaken in the region for domestic and export markets, local manufacture of printers and resins that reduces system and material cost, rising orthodontic treatment volumes, and the presence of GC Corporation and Shandong Huge Dental Material alongside regional printer and resin manufacturers. Second-quarter organic growth of 25.0% in Asia-Pacific excluding China at a leading digital dentistry group indicates the pace of adoption across the wider region.
Latin America
Latin America is expected to account for a smaller share of the market while growing strongly, with first-half 2026 organic growth of 15.4% at a leading digital dentistry group and double-digit growth in digital solutions, supported by large private dental sectors in Brazil and Mexico and by cost-sensitive adoption of chairside printing.
Middle East & Africa
The Middle East & Africa is expected to account for a limited share, with demand concentrated in private clinics and specialist centres in the Gulf states and South Africa.
Competitive landscape
The global Dental 3D Printing Market is moderately consolidated in systems, where a group of printer manufacturers and dental equipment companies holds the majority of placements, and more fragmented in materials, where dental materials companies, printer manufacturers and specialist resin formulators compete across indications. Market participants compete on regulatory clearance of printable materials for their intended intraoral use, accuracy and dimensional stability through printing and post-processing, throughput and cost per unit at laboratory and chairside scale, validation of the complete workflow from scan to finished device, breadth of qualified material portfolio on a given platform, and the service, training and support that determine whether an installed printer is used.
Leading companies are extending qualified resin portfolios across indications to capture recurring material revenue, pursuing regulatory clearance for directly fabricated intraoral devices, validating complete workflows from intraoral scan to finished appliance, developing printable ceramics and metals for definitive restorations, and building training and clinical support to raise utilisation of installed printers. Recent market context includes record quarterly consumables revenue of USD 66.3 million at Stratasys in the second quarter of 2026 alongside a decline in products revenue, the statement by Align Technology that direct fabrication is currently margin-dilutive and becomes neutral above 10% to 15% of volume with aligner direct fabrication requiring regulatory approval, and first-half 2026 organic growth of 7.8% at Straumann Holding with double-digit digital solutions growth in North America and Latin America.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Dental 3D Printing Market. The key players profiled in the report include 3D Systems Corporation (U.S.), Stratasys Ltd. (Israel), Dentsply Sirona Inc. (U.S.), Straumann Holding AG (Switzerland), Align Technology, Inc. (U.S.), SprintRay Inc. (U.S.), Formlabs Inc. (U.S.), Carbon, Inc. (U.S.), Asiga (Australia), Rapid Shape GmbH (Germany), DWS S.r.l. (Italy), Ivoclar Vivadent AG (Liechtenstein), BEGO GmbH & Co. KG (Germany), Kulzer GmbH (Germany), GC Corporation (Japan), Keystone Industries (U.S.), 3M Company (U.S.), and Shandong Huge Dental Material Corporation (China).
- 3D Systems Corporation
- Stratasys Ltd.
- Dentsply Sirona Inc.
- Straumann Holding AG
- Align Technology, Inc.
- SprintRay Inc.
- Formlabs Inc.
- Carbon, Inc.
- Asiga
- Rapid Shape GmbH
- DWS S.r.l
- Ivoclar Vivadent AG
- BEGO GmbH & Co. KG
- Kulzer GmbH
- GC Corporation
- Keystone Industries
- 3M Company
- Shandong Huge Dental Material Corporation
Expert perspectives
The Dental 3D Printing Market is usually assessed through printer placements, and in 2026 that measure pointed in the wrong direction. A leading system supplier reported total revenue of USD 137.6 million against USD 138.1 million a year earlier, with products revenue down to USD 92.7 million and record consumables revenue of USD 66.3 million in the same quarter, while the largest potential adopter of direct fabrication stated that the practice is currently dilutive to gross margin and becomes neutral only above 10% to 15% of volume. Demand for digital dentistry itself was not weak, with organic growth of 7.8% and a core EBIT margin of 26.9% at the leading implant and digital dentistry group. The binding constraint is therefore shifting from printer capability to the qualification and scale-up of materials, because the growth in this market now accrues to whoever supplies the resin consumed by printers already installed.
Three structural changes are expected to shape competitive positions through 2036. First, the revenue mix is expected to continue moving from systems to materials, which rewards cleared material portfolios over hardware placement and makes installed base utilisation a more important metric than units shipped. Second, direct fabrication is expected to arrive by device class rather than at once, beginning with attachments and specialty retainers and reaching aligners only after regulatory approval, which places the largest increase in material demand in the later part of the forecast period. Third, printing and milling are expected to develop in parallel rather than one displacing the other, since continuing investment in subtractive capability indicates that laboratories will select the process by indication.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in cleared resin formulations across denture, restorative, orthodontic and surgical indications, chairside workflows validated end to end for practices that already hold intraoral scanners, printable zirconia for definitive restorations currently served by milling, production services for group practices consolidating volume across locations, and training and clinical support that converts installed printers into material consumption.
Two cautions belong in any assessment of this market. The first is that direct fabrication of the highest-volume orthodontic appliance depends on a regulatory decision that no participant controls, so a forecast that brings that volume forward carries timing risk that the engineering position does not. The second is that an installed printer generates no material revenue unless it is used, and underutilisation in practices without validated workflows or trained staff is a more serious constraint in a materials-led market than a slow equipment cycle. Overall, systems, polymer printers, vat photopolymerization, dental polymers, prosthodontics, dental laboratories and North America are expected to provide the core of demand, with materials, ceramics, orthodontics, dental hospitals and clinics and Asia-Pacific providing the fastest growth.
Customer perspectives
Insights gathered during primary interviews with dental laboratory owners, practice principals, and orthodontic production managers highlight where priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects material portfolio and clearance displacing hardware specification.”
“This indicates workflow and training determining utilisation of installed equipment.”
“This points to direct fabrication multiplying material demand per case.”
Frequently asked questions
The global Dental 3D Printing Market is estimated at USD 5.14 billion in 2026.
Cite this report
Meticulous Research. (2026). Dental 3D Printing Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MRHC - 104803). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/dental-3d-printing-market-5487