Cancer Genomic Testing Market (2026-2036)
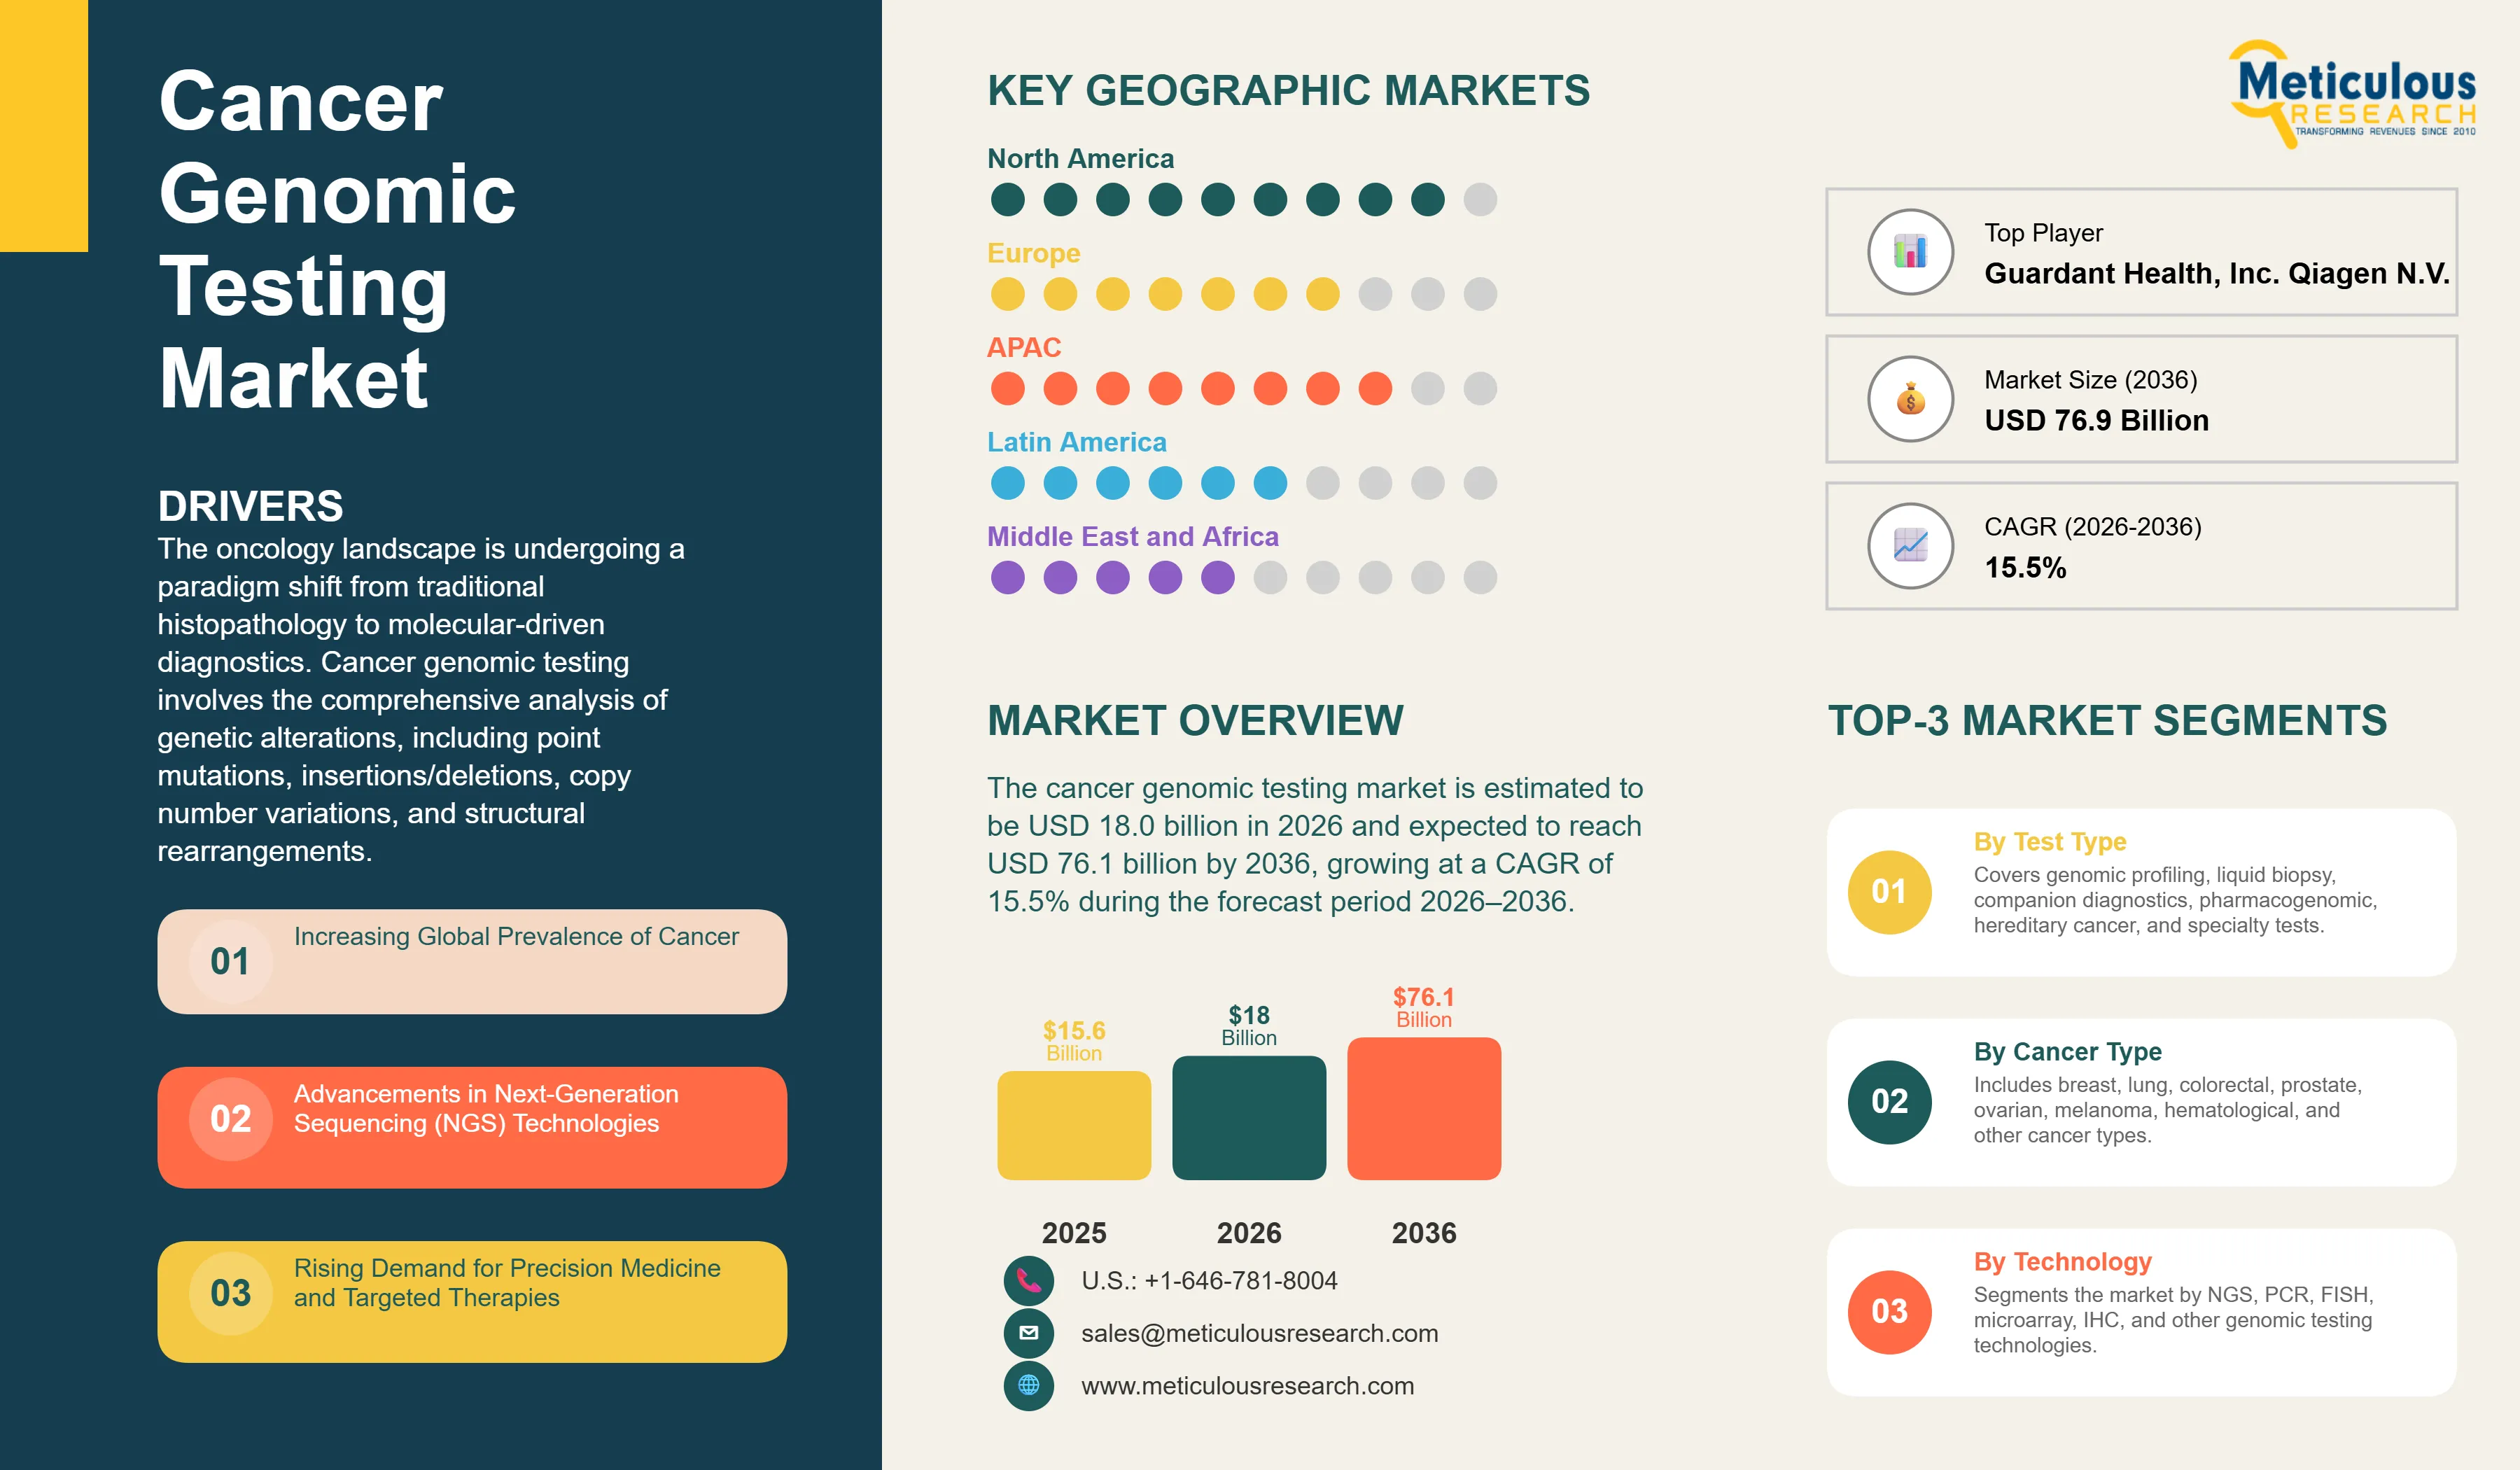
Market Sizing and Growth Projections The global cancer genomic testing market is estimated to be USD 18.0 billion in 2026. This market is expected to reach USD 76.1 billion by 2036, growing at a CAGR of 15.5% during the forecast period 2026–2036. The growth of this market is driven by the increasing
- Published
- Jun 2026
- Pages
- 284
- Format
- PDF + Excel
- Report ID
- MRHC - 1042038
- Base year
- 2025
- 2026 · ESTIMATED
- $18.00B
- 2036
- $76.10B
- CAGR 2026–2036
- 15.5%
2025 baseline · 2026–2036 forecast at 15.5% CAGR · hover a bar for the value
Key highlights
The next-generation sequencing (NGS) segment is expected to account for the largest share of the market in 2026, driven by its high throughput and ability to detect multiple biomarkers simultaneously.
Based on cancer type, the lung cancer segment is projected to hold the largest market share, supported by the extensive use of companion diagnostics for targeted therapies such as EGFR and ALK inhibitors.
The diagnostic laboratories segment is anticipated to remain the leading end user, owing to the centralization of complex genomic testing services and the presence of advanced laboratory infrastructure.
North America is estimated to dominate the global market in 2026, primarily due to high healthcare expenditure, the presence of major market players, and early adoption of advanced diagnostic technologies.
The liquid biopsy tests segment is expected to witness the highest CAGR during the forecast period, facilitated by the rising demand for minimally invasive monitoring of treatment response and minimal residual disease (MRD).
Strategic collaborations between biotechnology firms and pharmaceutical companies are accelerating the development of novel companion diagnostics for emerging immunotherapy agents.
The integration of AI-enabled bioinformatics tools is significantly enhancing the accuracy and speed of genomic data interpretation, reducing the clinical reporting turnaround time.
Precision oncology diagnostics are increasingly being adopted in emerging markets, driven by government initiatives to improve cancer care infrastructure and rising awareness among clinicians.
The expansion of multi-cancer early detection (MCED) tests is expected to redefine the screening landscape, offering opportunities for early intervention in high-risk populations.
Favorable reimbursement policies for comprehensive genomic profiling (CGP) in developed regions are encouraging the adoption of large-gene panels over single-gene tests.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 18.00 billion |
| Market Size (2036) | USD 76.10 billion |
| CAGR (2026–2036) | 15.5% |
| Format | PDF, Excel & Cloud Portal · 284 pages |
| Segments Covered | By Test Type · By Cancer Type · By Technology · By End User |
| Key Companies | Illumina, Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd, Qiagen N.V., Agilent Technologies, Inc., Myriad Genetics, Inc., Exact Sciences Corporation, Guardant Health, Inc., Foundation Medicine, Inc., Natera, Inc., NeoGenomics Laboratories, Inc., Veracyte, Inc., Tempus Labs, Inc., Personalis, Inc., Burning Rock Biotech Limited, Fulgent Genetics, Inc., Nanostring Technologies, Inc. |
Report infographic
Market Sizing and Growth Projections
The global cancer genomic testing market is estimated to be USD 18.0 billion in 2026. This market is expected to reach USD 76.1 billion by 2036, growing at a CAGR of 15.5% during the forecast period 2026–2036. The growth of this market is driven by the increasing prevalence of cancer globally, the rising demand for precision medicine, advancements in next-generation sequencing (NGS) technologies, and favorable reimbursement policies for genomic testing in developed regions. Furthermore, the integration of artificial intelligence (AI) in genomic data interpretation and the growing number of FDA-approved companion diagnostics are expected to offer significant growth opportunities for market players.
Strategic Evolution of Oncology Genomics and Precision Cancer Diagnostics
The oncology landscape is undergoing a paradigm shift from traditional histopathology to molecular-driven diagnostics. Cancer genomic testing involves the comprehensive analysis of genetic alterations, including point mutations, insertions/deletions, copy number variations, and structural rearrangements. This molecular insight is fundamental to precision oncology, enabling clinicians to tailor therapeutic interventions based on the unique genomic signature of a patient's tumor. According to the World Health Organization (WHO), cancer remains a leading cause of death worldwide, with nearly 10 million deaths recorded in 2020. As the global cancer burden is projected to rise to 28.4 million cases by 2040, the demand for robust cancer sequencing and biomarker testing has become imperative for effective disease management.
Tumor genomic profiling has transitioned from research-only applications to routine clinical practice. The advent of Next-Generation Sequencing (NGS) has significantly reduced the cost and time required for whole-exome and whole-genome sequencing. The National Cancer Institute (NCI) emphasizes that genomic testing not only aids in therapy selection but also plays a critical role in clinical trial matching and identifying hereditary cancer syndromes. As precision oncology diagnostics become more accessible, the market is witnessing an influx of multi-gene panels and liquid biopsy assays that provide a non-invasive alternative to traditional tissue biopsies. The shift toward oncology genomics is further supported by the development of standardized reporting guidelines and the establishment of molecular tumor boards in leading cancer centers worldwide.
NGS cancer testing has revolutionized the diagnostic workflow by allowing for the simultaneous assessment of hundreds of genes. This high-throughput capability is essential for identifying actionable mutations in solid tumors and hematological malignancies. The integration of cancer biomarker testing into standard care pathways is being accelerated by the falling costs of sequencing and the increasing availability of targeted therapies. Industry associations like the American Society of Clinical Oncology (ASCO) and the European Society for Medical Oncology (ESMO) have incorporated genomic testing recommendations into their clinical practice guidelines, underscoring its clinical utility in improving patient survival rates.
Market dynamics
10 factors across 5 forcesIncreasing Global Prevalence of Cancer
The escalating incidence of cancer worldwide remains the primary driver for the cancer genomic testing market. According to the International Agency for Research on Cancer and the World Health Organization, approximately 20 million new cancer cases and 9.7 million cancer-related deaths were reported globally in 2022, making cancer one of the leading causes of mortality worldwide. Furthermore, breast cancer remains the most commonly diagnosed cancer globally, accounting for approximately 2.3 million new cases annually. The global cancer burden is projected to increase significantly, with the International Agency for Research on Cancer estimating that new cancer cases will exceed 35 million annually by 2050, representing a 77% increase compared with 2022 levels. This growing disease burden is intensifying the demand for precision oncology and advanced molecular diagnostics. Genomic testing enables the identification of actionable genetic alterations, supporting targeted therapy selection, treatment monitoring, and personalized disease management, ultimately improving clinical outcomes and healthcare efficiency.
Advancements in Next-Generation Sequencing (NGS) Technologies
Technological breakthroughs in NGS have revolutionized oncology genomics by significantly reducing sequencing costs and turnaround times. The launch of high-throughput platforms, such as Illumina's TruSight Oncology (TSO) Comprehensive in March 2022, has made comprehensive genomic profiling (CGP) more accessible in clinical settings. These advancements enable the simultaneous assessment of multiple tumor genes and biomarkers, facilitating precision medicine decisions. The shift from single-gene testing to large-scale genomic panels is a direct result of these technological improvements, allowing for more comprehensive tumor characterization.
Table of contents
12 chapters · 121 sections · 284 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Test Type | Genomic profiling tests | Liquid biopsy |
| By Technology | — | — |
By Test Type
- The genomic profiling tests segment is estimated to account for the largest share of the global cancer genomic testing market in 2026.
- This dominance is attributed to the rising adoption of CGP in clinical guidelines, such as those from the National Comprehensive Cancer Network (NCCN).
- Conversely, the liquid biopsy segment is expected to grow at the fastest CAGR.
- This is driven by its application in 'real-time' monitoring of tumor evolution and the increasing clinical utility of circulating tumor DNA (ctDNA) for detecting recurrence months before traditional imaging.
By Technology
- Next-generation sequencing (NGS) is the leading technology segment.
- Its ability to perform high-throughput sequencing of millions of DNA fragments simultaneously makes it indispensable for modern oncology.
- While PCR remains relevant for specific, high-sensitivity tests (like KRAS mutations), the comprehensive nature of NGS is driving its displacement of older technologies like FISH in many diagnostic workflows.
Geographic analysis
North America
Largest shareNorth America is expected to hold the largest market share in 2026. The region's leadership is underpinned by a robust ecosystem of biotechnology companies, favorable Medicare coverage for NGS-based tests, and a high rate of personalized medicine adoption. Europe follows North America, with strong government support for genomics initiatives in countries like the U.K., Germany, and France.
Asia-Pacific
Fastest growthThe Asia-Pacific region is projected to be the fastest-growing market, with a projected CAGR of 22.6%. This growth is fueled by increasing healthcare investments in China and India, a large patient pool, and the expansion of global diagnostic giants into these emerging markets.
Competitive landscape
- Illumina, Inc.
- Thermo Fisher Scientific Inc.
- F. Hoffmann-La Roche Ltd
- Qiagen N.V.
- Agilent Technologies, Inc.
- Myriad Genetics, Inc.
- Exact Sciences Corporation
- Guardant Health, Inc.
- Foundation Medicine, Inc.
- Natera, Inc.
- NeoGenomics Laboratories, Inc.
- Veracyte, Inc.
- Tempus Labs, Inc.
- Personalis, Inc.
- Burning Rock Biotech Limited
- Fulgent Genetics, Inc.
- Nanostring Technologies, Inc.
Frequently asked questions
The market is estimated to reach $76.01 billion by 2036, growing at a CAGR of 15.5% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Cancer Genomic Testing Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042038). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/cancer-genomic-testing-market-6721