Absorbent Hygiene Products Market (2026-2036)
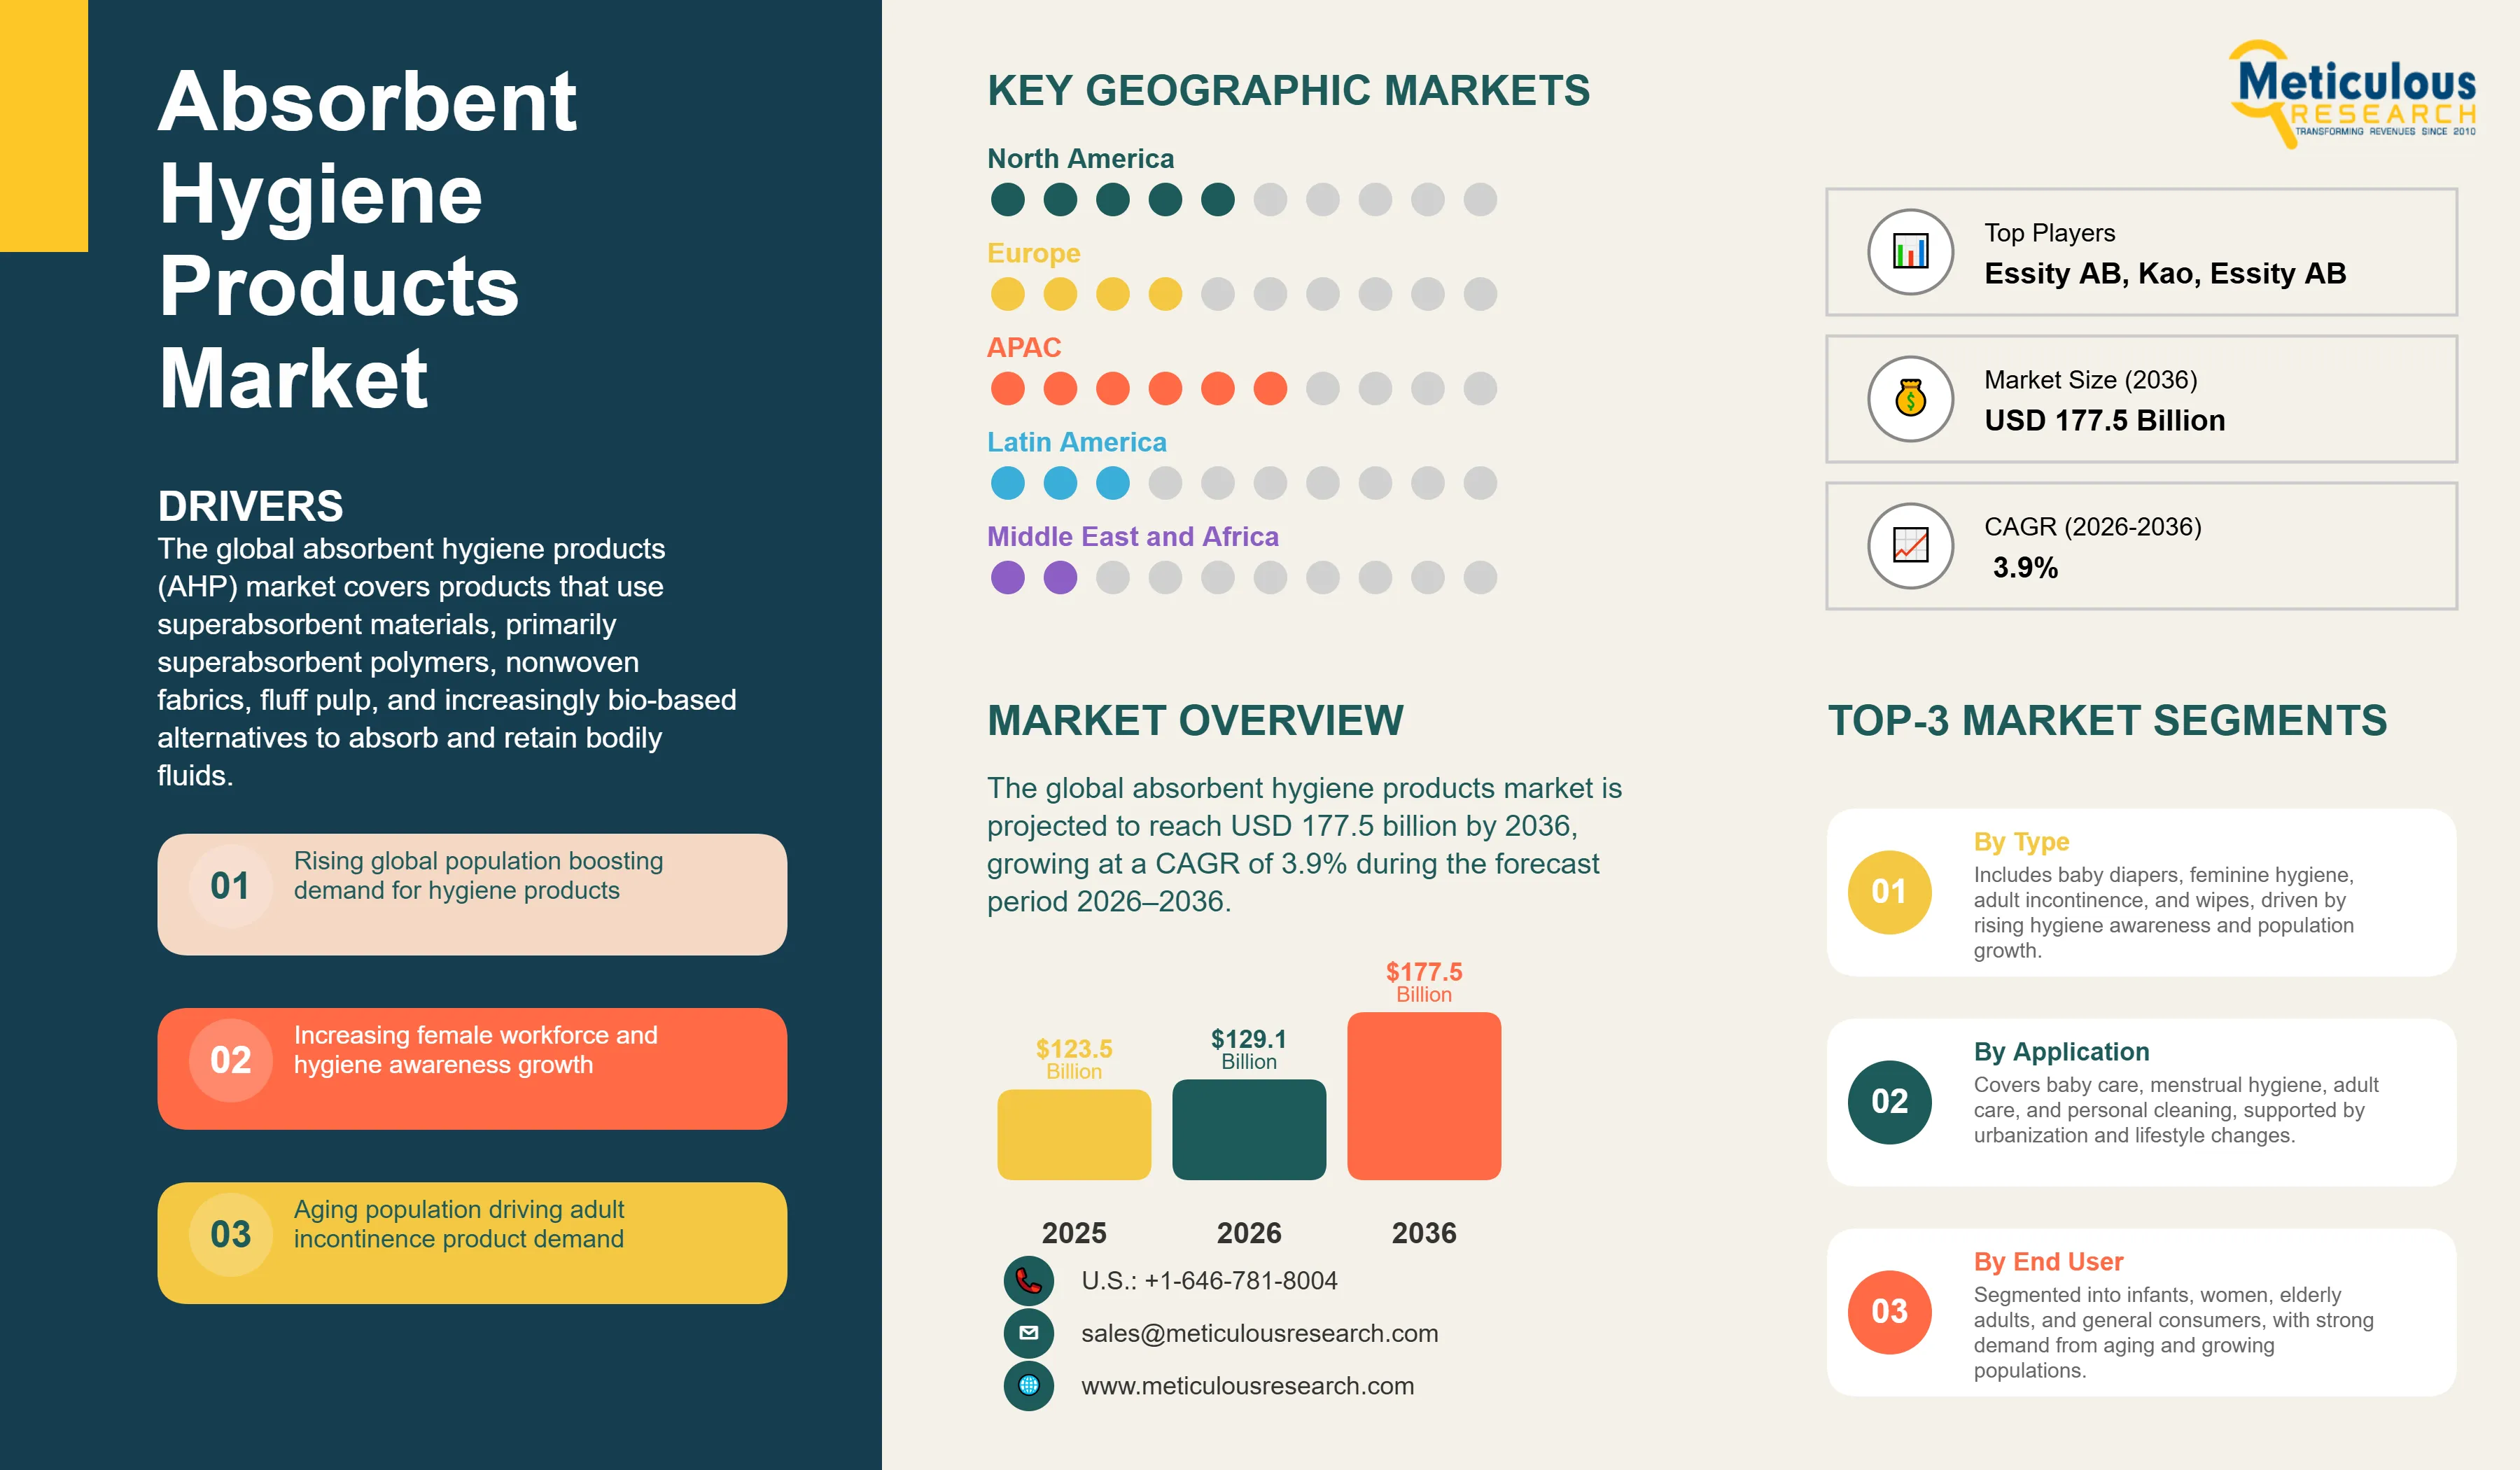
The global absorbent hygiene products market was valued at USD 123.5 billion in 2025. The market is projected to reach USD 177.5 billion by 2036 from an estimated USD 129.1 billion in 2026, growing at a CAGR of 3.9% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 283
- Format
- PDF + Excel
- Report ID
- MR-1926
- Base year
- 2025
- 2025 · BASELINE
- $123.5B
- 2036
- $177.5B
- CAGR 2026–2036
- 3.9%
2025 baseline · 2026–2036 forecast at 3.9% CAGR · hover a bar for the value
Key highlights
The global absorbent hygiene products market is projected to reach USD 177.5 billion by 2036.
The market is expected to grow at a CAGR of 4.7% during the forecast period 2026–2036.
The global absorbent hygiene products market was valued at USD 123.5 billion in 2025 and is estimated to reach USD 129.1 billion in 2026.
Asia Pacific is expected to dominate the global absorbent hygiene products market in 2026, accounting for around 35-40% of the global revenue. This dominance is mainly due to its position as both the world’s largest production hub for absorbent hygiene products and the fastest-growing consumer base, driven by the world’s largest infant and elderly populations, rapidly rising female workforce participation, and growing menstrual hygiene awareness.
Asia Pacific accounts for around 40-45% of the global diaper output annually, driven by major manufacturing investments across Japan, China, India, and Vietnam.
Asia Pacific absorbent hygiene products market is also expected to grow at the fastest CAGR during the forecast period. China and India are the two most significant growth opportunities.
North America holds a significant share of the global absorbent hygiene products market, driven by a combination of high per-capita product consumption in the baby diaper and adult incontinence segments, a large and fast-growing elderly population, and premium product demand supported by well-developed retail and e-commerce infrastructure.
The U.S. is the single largest national market for absorbent hygiene products globally for adult incontinence products and a major premium baby diaper market. Kimberly-Clark announced a USD 2 billion manufacturing investment in the U.S. spanning 2025 to 2030, its largest domestic expansion in 30 years, indicating the company’s confidence in strong growth in North American absorbent hygiene products market.
Europe holds the third-largest regional share, characterized by stringent environmental regulation, high consumer demand for sustainable and eco-friendly product formats, and well-established healthcare reimbursement frameworks for adult incontinence products.
The EU’s Packaging and Packaging Waste Regulation, effective February 2025, mandates escalating recycling standards and climate neutrality benchmarks, compelling manufacturers to accelerate investments in biodegradable materials, plant-based absorbent cores, and recyclable packaging.
By product category, baby diapers and training pants are expected to hold the largest market share in 2026, at around 45% to 50% of the global revenue. The baby diaper market is primarily driven by the expanding birth rate-driven demand base in Sub-Saharan Africa and South Asia, ongoing premiumization in developed markets, and the rapid urbanization of emerging markets where disposable diaper adoption is increasing.
Adult incontinence products are expected to register the fastest CAGR during the forecast period, driven by structural global population aging. Over 761 million people are aged 65 and above globally as of 2025, and the WHO’s Integrated Care for Older People guidelines document urinary incontinence prevalence of 9% to 39% across patient populations. Japan’s adult diaper market has outsold its baby diaper market every year since 2015, a demographic inflection point that is approaching in China, South Korea, and several European markets.
By raw material, superabsorbent polymers (SAP) are expected to hold the largest market share in 2026. SAP is the performance-critical component of all three major absorbent hygiene product categories, enabling products to absorb up to 500 times their own mass in liquid.
Bio-based and sustainable SAP alternatives are expected to grow at the fastest CAGR during the forecast period, driven by the EU Circular Economy Action Plan and rising consumer preference for products incorporating plant-derived or biodegradable absorbent materials.
By distribution channel, supermarkets and hypermarkets are expected to hold the largest market share in 2026, showing the dominant role of mass retail in providing accessibility, competitive pricing, and high consumer trial for all AHP categories.
Online and e-commerce channels are expected to register the fastest CAGR during the forecast period, with online channels currently indicating around 30-35% of the global absorbent hygiene product sales and growing rapidly through subscription models, direct-to-consumer brands, and expanding e-commerce infrastructure in emerging markets.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 177.5 Billion |
| Market Size in 2026 | USD 129.1 Billion |
| Market Size in 2025 | USD 123.5 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 3.9% |
| Format | PDF, Excel & Cloud Portal · 283 pages |
| Dominating Product Category | Baby Diapers & Training Pants |
| Fastest Growing Product Category | Adult Incontinence Products |
| Dominating Raw Material | Superabsorbent Polymers (SAP) |
| Fastest Growing Raw Material | Bio-Based / Sustainable Materials |
| Dominating End User | Infants & Babies |
| Fastest Growing End User | Elderly / Incontinent Adults |
| Dominating Category | Disposable |
| Fastest Growing Category | Reusable / Washable |
| Dominating Distribution Channel | Supermarkets & Hypermarkets |
| Fastest Growing Distribution Channel | Online / E-Commerce |
| Dominating Geography | Asia Pacific |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: raw material, end user, category, distribution channel, product category.
The global absorbent hygiene products (AHP) market covers products that use superabsorbent materials, primarily superabsorbent polymers, nonwoven fabrics, fluff pulp, and increasingly bio-based alternatives to absorb and retain bodily fluids. The market covers three primary product categories: baby diapers and training pants, feminine hygiene products (sanitary napkins, tampons, panty liners, and period underwear), and adult incontinence products (briefs, protective underwear, pads, and underpads), along with absorbent wipes used across baby care, personal hygiene, and healthcare applications.
Report infographic
Market dynamics
2 factors across 1 forceEmerging Market Penetration and Birth-Rate-Driven Volume Growth Creating Significant Structural Opportunities
One of the key trends in the global absorbent hygiene products market is the accelerating penetration of disposable hygiene products in Sub-Saharan Africa, South Asia, and Southeast Asia, where a combination of growing populations, rising incomes, rapid urbanization, and improving product access and awareness are converting hundreds of millions of potential consumers from traditional alternatives to commercial AHP products. This trend applies across all three major product categories simultaneously: baby diapers, feminine hygiene products, and adult incontinence products.
The feminine hygiene market provides the most acute illustration. In key Global South markets including India, Kenya, Nigeria, Ethiopia, Bangladesh, Senegal, and South Africa, disposable pad penetration is growing significantly, driven by younger generations that have grown up with product access and are driving category adoption rates significantly higher than older cohorts. In India, overall menstrual hygiene product penetration among menstruators stands at 77%, rising to 89% among the 18–24 age group, indicating a powerful generational adoption curve that will progressively expand the addressable market as younger cohorts age through their menstruating years.
The market entry of Unicharm in Kenya through a joint venture with Toyota Tsusho Corporation and CFAO Kenya Limited to launch local sanitary napkin production in January 2025 offers a blueprint for how global AHP leaders are tackling Africa's underpenetrated feminine hygiene segment. Local manufacturing proves essential for hitting the affordable price points needed to drive mass adoption in these price-sensitive markets, and this strategy is echoing through baby diaper production in India, where Doms Industries' acquisition of a 51.77% stake in Uniclan Healthcare targets the baby diaper market, leveraging Uniclan's 400 million units annual capacity.
Sustainability and Eco-Innovation Reshaping Raw Material Supply Chains and Product Design Across All AHP Categories
Sustainability is the defining challenge and innovation opportunity in the global absorbent hygiene products market. AHP products are estimated to contribute billions of units of non-biodegradable landfill waste annually, with conventional baby diapers, sanitary pads, and adult incontinence briefs all incorporating petroleum-derived SAPs, plastic-based nonwoven layers, and synthetic adhesives that resist decomposition for centuries. Regulatory pressure, consumer environmental consciousness, mainly in Europe and among millennial and Gen Z parents globally, and growing ESG reporting requirements on hygiene manufacturers are creating strong demand for sustainable product innovation across all AHP categories.
The SAP supply chain remains the critical focus area for sustainable AHP innovation. Traditional sodium polyacrylate SAP relies on energy-intensive petrochemical processes with zero biodegradability. In February 2025, BASF launched HySorb® B 6610 ZeroPCF, the first zero-product-carbon-footprint polyacrylate SAP in the industry, allowing manufacturers to slash Scope 3 emissions without reformulating products. Leading producers like Sumitomo Seika and LG Chem have rolled out bio-based SAP variants using renewable feedstocks, while Purdue University researchers hold patents on hemp-derived alternatives alongside active starch, cellulose, and sucrose-based R&D programs. The EU Circular Economy Action Plan, prioritizing product sustainability across sectors, continues driving these shifts in Europe and shaping worldwide AHP standards.
Across product categories, leading manufacturers are delivering concrete sustainability programs. Procter & Gamble introduced recyclable FSC-certified paper packaging for Charlie Banana reusable diapers in June 2024. Essity's TENA Lights Sensitive launch featured the first paper packaging in adult incontinence with ≥50% plant-based materials. Ontex rolled out biodegradable iD brand products in 2024. In feminine hygiene, GreenCore Solutions Corp. debuted FemCare UltraThin, its first tree-free feminine care line for European private labels, in May 2025. These moves indicate a evolution from packaging tweaks to core material redesign, driven by regulatory pressures, retailer mandates, and shifting consumer values.
Table of contents
13 chapters · 170 sections · 283 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Category | Baby Diapers & Training Pants | Adult incontinence products |
| By Raw Material | Superabsorbent Polymers | Bio-based and sustainable materials |
| By End User | Infants & Babies | — |
| By Category | Disposable | Reusable and washable products |
By Product Category
- Baby Diapers & Training Pants to Dominate the Global Absorbent Hygiene Products Market
- Baby diapers and training pants are expected to account for the largest share of the global absorbent hygiene products market.
- With annual global consumption exceeding 200 billion units, baby diapers remain the largest single product category within AHPs by both volume and value.
- Procter & Gamble, Kimberly-Clark, and Unicharm dominate this segment, with the top five producers collectively holding around 40-50% of the global market share.
- The growth of this market is mainly driven by the increasing demand from Sub-Saharan Africa, South Asia, and Southeast Asia, where rapidly growing infant populations are experiencing growing product adoption as income levels rise and retail availability expands.
- However, adult incontinence products are expected to register the fastest CAGR during the forecast period, driven by the increasing demographic aging of global populations.
- More than 761 million people are aged 65 and above globally as of 2025, with the WHO ICOPE guidelines documenting urinary incontinence prevalence of 9% to 39% across patient populations.
- The leakproof apparel sub-segment within adult incontinence, including washable absorbent underwear and period/incontinence crossover products, is growing significantly, indicating the most dynamic growth sub-segment across the entire AHP market.
By Raw Material
- Superabsorbent Polymers to Hold the Largest Share
- Superabsorbent polymers (SAP) are expected to account for the largest share of the global AHP raw materials market.
- SAP, primarily sodium polyacrylate produced by BASF, Nippon Shokubai, Evonik, Sumitomo Seika, and LG Chem, is the performance-critical core material in all three major AHP product categories, capable of absorbing up to 500 times its own mass in liquid.
- Nippon Shokubai’s August 2025 groundbreaking for a new SAP plant in Cilegon, Indonesia reflects the confidence in strong Asia Pacific demand growth for this critical raw material.
- Bio-based and sustainable materials are expected to register the fastest CAGR during the forecast period, driven by regulatory requirements, ESG mandates, and consumer sustainability preferences.
- BASF’s February 2025 launch of HySorb® B 6610 ZeroPCF, the first zero-carbon-footprint polyacrylate SAP, indicates a major commercial milestone, enabling manufacturers to reduce lifecycle emissions without changing production processes.
- Multiple research programs in hemp, corn starch, cellulose, and sucrose-based bio-SAPs are advancing toward commercial scale, supported by the EU Circular Economy Action Plan’s specific focus on sustainable AHP materials.
By End User
- Infants & Babies to Hold the Largest Share
- Infants and babies are expected to account for the largest share of the global AHP market, showing the dominant revenue contribution of baby diapers to total AHP product value.
- This commercial importance of this segment extends beyond its current revenue contribution to its role as the primary entry point for consumer adoption of the broader AHP product ecosystem in emerging markets, where first-time baby diaper buyers often subsequently develop awareness of feminine hygiene and other AHP categories.
- The elderly/incontinent adult segment consistently shows the highest CAGR across AHP categories, outpacing baby diapers and feminine hygiene due to unavoidable physiological demand tied to aging.
- UN World Population Prospects 2022 confirms 65+ as the fastest-growing age cohort globally, rising from 10% to 16% of world population by 2050, with 761 million people aged 65+ already in 2025 per updated UN figures.
By Category
- Disposable to Hold the Largest Share
- Disposable products are expected to account for the largest share of global AHP market.
- Disposable AHPs offer superior performance, convenience, and hygiene compared to traditional or reusable alternatives, and their adoption continues to expand rapidly in emerging markets as income levels improve and retail distribution broadens.
- The institutional care market, including nursing homes, hospitals, and eldercare facilities is mainly served by disposable products due to hygiene protocol requirements.
- Reusable and washable products are expected to register the fastest CAGR during the forecast period, led by the leakproof apparel sub-segment in adult incontinence and period underwear in feminine hygiene.
- Essity's estimate of 20%+ annual growth for leakproof apparel, Kimberly-Clark's Thinx acquisition, and the expanding availability of reusable cloth diapers and organic washable menstrual products reflect a genuine and growing commercial niche driven by environmental consciousness and premiumization in developed markets.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia Pacific is expected to account for the largest share of the global absorbent hygiene products market. The region is simultaneously the world’s largest production hub, contributing over 40-45% of the global diaper output annually, and the largest consumer market, driven by the world’s largest infant and elderly populations. Japan, China, South Korea, and India are the primary national markets, each at different stages of AHP category maturity. Japan represents the most advanced demographic scenario, with adult diapers outselling baby diapers since 2015. China combines the world’s second-largest diaper market with an increasing elderly population and 90 million adults affected by incontinence. India is the most significant volume growth opportunity, with a 1.4 billion population in which AHP penetration across all categories remains well below developed market levels. Nippon Shokubai’s August 2025 Indonesian SAP plant groundbreaking and Unicharm’s Vietnam manufacturing expansion reflect the region’s critical importance to global AHP supply chain strategy. South Korea Australia Vietnam Rest of Asia Pacific
North America
North America holds a significant share of the global AHP market, dominated by the U.S. The U.S. is the world’s single largest national market for adult incontinence products and a major premium baby diaper market, with Procter & Gamble and Kimberly-Clark maintaining the two strongest consumer brands in both segments. Kimberly-Clark’s USD 2 billion U.S. manufacturing investment spanning 2025 to 2030, described as the company’s largest domestic expansion in 30 years, indicates strong confidence in North American demand. First Quality Enterprises’ February 2025 acquisition of Henkel’s Retailer Brands North America business further reinforces the region’s competitive intensity in the private-label AHP segment. North America U.S. Canada Mexico
Europe
Fastest growthEurope also holds a significant share, characterized by the most stringent environmental regulatory environment for AHPs globally. The EU’s Packaging and Packaging Waste Regulation effective February 2025, its Circular Economy Action Plan, and the Single-Use Plastics Directive are collectively driving the fastest-paced sustainability transformation of AHP products anywhere in the world. Germany, France, the U.K., Sweden, and Italy are the largest national markets in Europe. Essity (Sweden), Ontex (Belgium), Paul Hartmann (Germany), and Abena (Denmark) are the dominant European AHP brands. Europe’s feminine hygiene market is experiencing rapid growth in organic, biodegradable, and reusable product formats, with GreenCore Solutions Corp.’s May 2025 tree-free feminine care launch for European private label retailers showing the direction of category evolution. U.K. France Sweden Italy Spain Rest of Europe
Latin America
Latin America and the Middle East & Africa are growing markets for AHP with distinct dynamics. In Latin America, Brazil and Mexico lead with rising middle-class income, growing female workforce participation, and improving e-commerce distribution. In Sub-Saharan Africa, the penetration of feminine hygiene products is increasing rapidly from a low base, with government and NGO programs addressing period poverty and improving menstrual hygiene education. The Kenya Menstrual Hygiene Management Policy, launched in 2020, and Unicharm’s January 2025 local sanitary napkin production launch in Kenya indicates the momentum of this growth opportunity. Baby diaper markets in Nigeria, South Africa, and Ethiopia are all at early-penetration stages with high volume growth potential. By Geography (Revenue, USD Billion, 2026–2036) Brazil Rest of Latin America
Middle East & Africa
UAE Saudi Arabia Kenya South Africa Rest of Middle East & Africa
Competitive landscape
- Procter & Gamble Company (U.S.)
- Kimberly-Clark Corporation (U.S.)
- Essity AB · Sweden
- Unicharm Corporation · Japan
- Kao Corporation · Japan
- Ontex Group NV · Belgium
- Paul Hartmann AG · Germany
- Johnson & Johnson (U.S.)
- Hengan International Group · China
- First Quality Enterprises, Inc. (U.S.)
- Drylock Technologies NV · Belgium
- Daio Paper Corporation · Japan
- Nobel Hygiene Pvt. Ltd. · India
- Edgewell Personal Care Company (U.S.)
- Abena Holding A/S · Denmark
- Medline Industries LP (U.S.)
Frequently asked questions
The global absorbent hygiene products market is expected to reach USD 177.5 billion by 2036 from an estimated USD 129.1 billion in 2026, at a CAGR of 3.9% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Absorbent Hygiene Products Market - Global Opportunity Analysis And Industry Forecasts (2026-2036) (Report No. MR-1926). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/absorbent-hygiene-products-market-6609