Wound Closure Market (2025-2032)
The Wound Closure Market was valued at $16.54 billion in 2024. This market is expected to reach $28.12 billion by 2032, from an estimated $17.75 billion in 2025, at a CAGR of 6.8% during the forecast period 2025-2032. Wound Closure Market Size & Forecast The growth of this market can be attributed
- Published
- May 2024
- Pages
- 330
- Format
- PDF + Excel
- Report ID
- MR-1153
- Base year
- 2024
- 2024 · BASELINE
- $16.54B
- 2032
- $28.12B
- CAGR 2025–2032
- 6.8%
2024 baseline · 2025–2032 forecast at 6.8% CAGR · hover a bar for the value
Key highlights
By Product: The Wound Dressings Segment to Dominate the Wound Closure Market in 2025
By Wound Type: The Acute Wounds Segment to Dominate the Wound Closure Market in 2025
By End User: The Hospitals & Clinics Segment to Dominate the Wound Closure Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 330 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 6.8% |
| Market Size (Value) | USD 28.12 Billion by 2032 |
| Segments Covered | By Product · Sutures · Absorbable Sutures · Non-absorbable Sutures · Suturing Devices · Needles · Tissue Adhesives · Topical/Local Hemostats · Sealants · Fibrin Sealants · Synthetic Sealants · Skin Staplers · Powered · Manual · Stapler Accessories · Wound Dressings · Hydrocolloid Dressings · Foam Dressings · Alginate Dressings · Film Dressings · Collagen Dressings · Hydrogel Dressings · Other Wound Dressings · Wound Closure Devices · Other Products & Accessories · (Note 1: Other Wound Dressings Include Composite Dressings, Transparent Dressings, and Hydrofiber Dressings.) · (Note 2: Wound Closure Devices Include Zips, Strips, and Bandages.) · (Note 3: Other Products & Accessories Include Meshes, Pledgets, Needle Holders, Pacing Leads, Bolsters, and Hydrogels.) · By Wound Type · Acute Wounds · Surgical Wounds · Traumatic Wounds · Burns · Chronic Wounds · Diabetic Foot Ulcers · Venous Leg Ulcers · Pressure Ulcers · Other Chronic Wounds · (Note: Other Chronic Wounds Include Arterial Ulcers and Acute & Sub-acute Ulcers.) · By End User · Hospitals & Clinics · Ambulatory Surgical Centers · Home Care Settings · Other End Users · (Note: Other End Users Include Academic & Research Institutes, Long-term Care Centers, and Defense.) |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, Italy, U.K., Spain, Switzerland, Belgium, Rest of Europe), Asia-Pacific (India, China, Japan, Australia, South Korea, Rest of Asia-Pacific), Latin America (Brazil, Mexico, Rest of Latin America), and the Middle East & Africa |
| Key Companies Profiled | 3M Company (U.S.), Medtronic plc (Ireland), Cardinal Health, Inc. (U.S.), Johnson & Johnson Services, Inc. (U.S.), B. Braun Melsungen AG (Germany), Essity AB (Sweden), Medline Industries, LP (U.S.), Stryker Corporation (U.S.), Smith & Nephew plc (U.K.), Integra LifeSciences Corporation (U.S.), Organogenesis Inc. (U.S.), Coloplast A/S (Denmark), Convatec Group plc (U.K.), and Corza Medical (U.S.) |
Report overview
Segments covered: product, suture, absorbable suture, non-absorbable suture, suturing device, needle, tissue adhesive, topical/local hemostat, sealant, fibrin sealant, synthetic sealant, skin stapler, powered, manual, stapler accessory, wound dressing, hydrocolloid dressing, foam dressing, alginate dressing, film dressing, collagen dressing, hydrogel dressing, other wound dressing, wound closure device, other products & accessory, wound type, acute wound, surgical wound, traumatic wound, burn, chronic wound, diabetic foot ulcer, venous leg ulcer, pressure ulcer, other chronic wound, end user, hospitals & clinic, ambulatory surgical center, home care setting, other end user. Regions: North America, Europe, Asia-Pacific, Latin America.
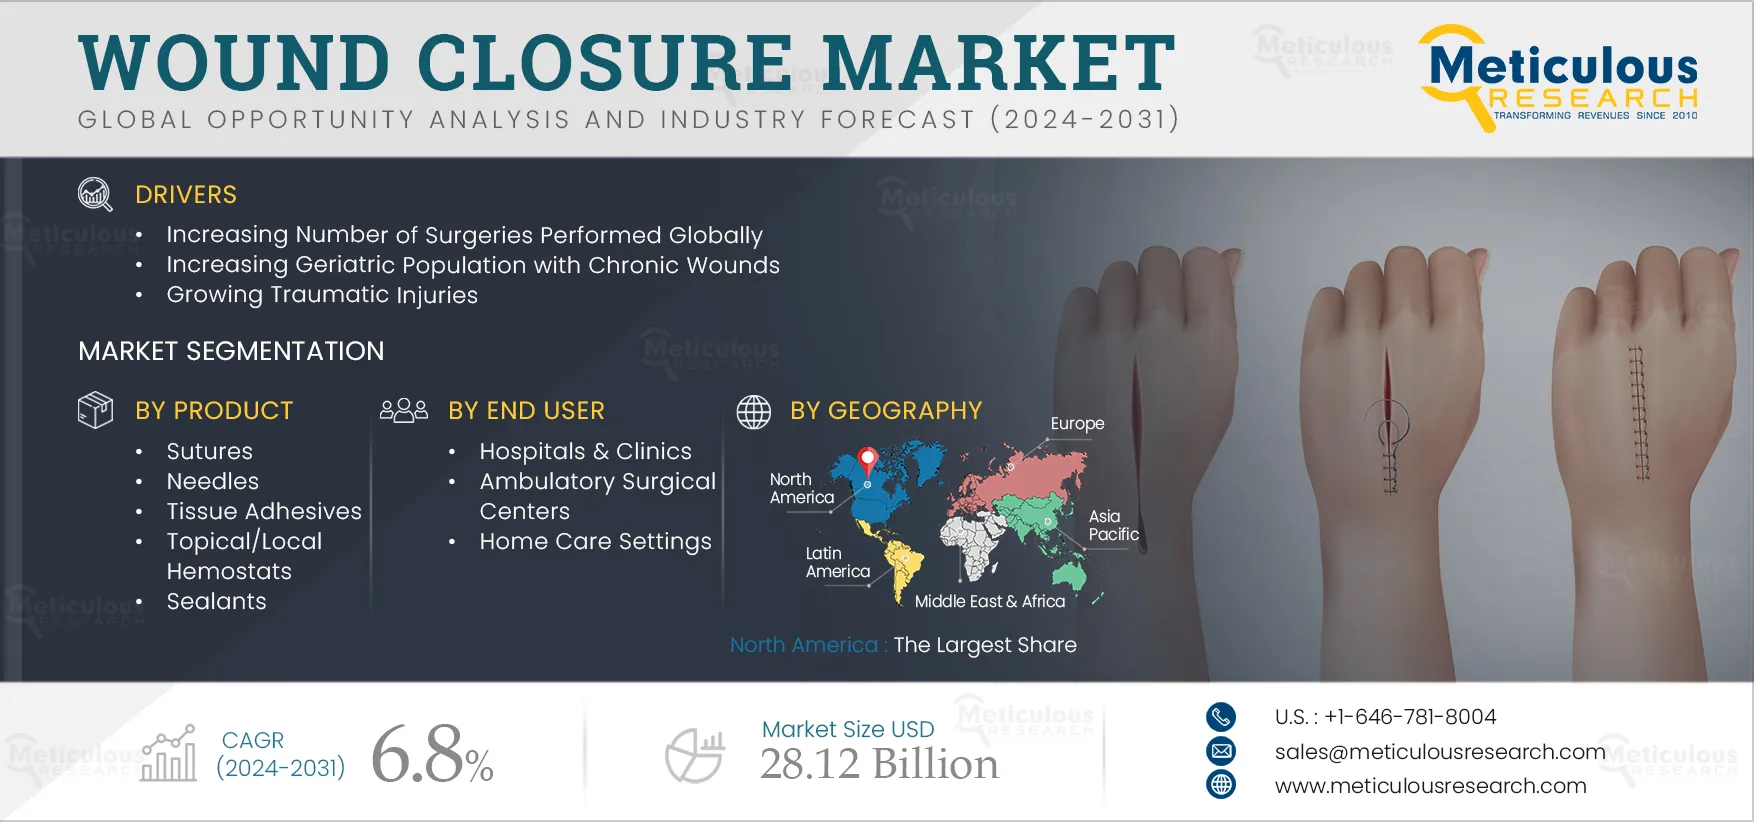
The growth of this market can be attributed to the increasing number of surgeries, growth in chronic wound cases among the geriatric population, the growing incidence of traumatic injuries, increasing awareness about wound care, and the rising focus on infection prevention.
Moreover, technological advancements in wound closure products and the demand for wound closure in aesthetic procedures are expected to offer growth opportunities for the players operating in this market.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Number of Surgeries
Medical conditions, including work-related injuries, cardiovascular diseases, cancer, and neurological diseases, require surgical interventions.
-
According to a WHO study, cesarean section was the most common type of surgery performed globally in 2021, accounting for 21% of all births. This number is expected to rise further over the next ten years, with cesarean sections estimated to account for nearly a third (29%) of all deliveries in 2032. By 2032, the highest rates of C-section surgery are projected to be in Eastern Asia (63%), Latin America & the Caribbean (54%), Western Asia (50%), Northern Africa (48%), Southern Europe (47%), and Australia & New Zealand (45%).
- According to data published by the Annuals of Thoracic Surgery Short Reports in December 2024, each year, over 1 million cardiac surgical procedures are conducted globally.
- According to the Organisation for Economic Co-operation and Development (OECD), in 2021, 111,783 appendectomy surgeries were conducted in Germany, 81,250 were conducted in Korea, 71,181 were conducted in France, and 41,866 were conducted in Canada.
Thus, the increasing number of surgeries is boosting the demand for various wound closure products, including sutures, needles, skin staplers, and dressings.
Growth in Chronic Wound Cases Among the Geriatric Population
Growth in the geriatric population has led to a rise in chronic wounds such as diabetic foot ulcers, venous leg ulcers, and pressure ulcers. Diabetes is a long-term condition that leads to diabetic foot ulcers. According to data published by the National Institutes of Health (NIH) in August 2024, the incidence of diabetic foot ulcers around the world ranges from 9.1 to 26.1 million yearly. Approximately 15 to 25% of people with diabetes mellitus are diagnosed with diabetic foot ulcers in their lifetime.
Furthermore, according to the International Diabetes Federation (IDF), in 2022, the prevalence of Diabetic Foot Ulcers (DFU) in African countries was between 10% and 30%. Also, the prevalence of diabetic foot ulcers throughout Europe in 2022 ranged between 1.0% (Denmark) and 17.0% (Belgium). Further, in the IDF Middle East & North Africa Region, DFU prevalence was between 5.0% and 20% in 2022, while DFU recurrence ranged between 31.0% (Egypt) to 43.0% (Turkey). In Brazil, the prevalence of DFU was 21.0% in 2022. Such chronic injuries require regular treatment to avoid severe infections and emergency conditions, driving the demand for various wound closure products.
Table of contents
11 chapters · 126 sections · 330 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Product | Wound Dressings | Wound dressings |
| By Wound Type | Acute Wounds | — |
| By End User | Hospitals & Clinics | — |
By Product
- The Wound Dressings Segment to Dominate the Wound Closure Market in 2025
- The wound dressings segment is expected to account for the largest share of 60.9% of the wound-closure market.
- The large market share of this segment can be attributed to the advancements in wound dressings, such as film dressings and foam dressings, which offer benefits such as reduced risk of wound breakdown, lower risk of infection, and faster healing.
- Furthermore, market players are focused on introducing innovative offerings to cater to the growing demand for wound dressings.
- For instance, in June 2022, Medline Industries, LP (U.S.) launched the Optifoam Gentle EX Foam Dressing to help reduce pressure injuries.
- Also, the wound dressings segment is projected to register the highest growth rate of 6.2% during the forecast period 2025–2032.
By Wound Type
- The Acute Wounds Segment to Dominate the Wound Closure Market in 2025
- The acute wounds segment is expected to account for the larger share of the wound closure market.
- The segment’s large market share can be attributed to the increasing number of surgical and traumatic injuries and burn cases all over the world.
- According to the World Health Organization’s (WHO) 2024 data, annually, 180,000 deaths are caused due to burns globally.
- Thus, the increasing number of burn injury cases drives the demand for advanced wound care products.
By End User
- The hospitals & clinics segment is expected to account for the largest share of 53.9% of the wound closure market.
- The large market share of this segment can be attributed to the growing number of patient visits to hospitals & clinics for wound care & management and surgical procedures, the presence of highly skilled healthcare professionals, ease in accessibility, increasing healthcare expenditures, improving hospital infrastructure in emerging economies, and the increasing adoption of advanced wound closure products among hospitals & clinics.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 38.3% of the wound closure market, followed by Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America’s significant market share can be attributed to the presence of major wound closure companies such as 3M Company (U.S.), Johnson & Johnson Services, Inc. (U.S.), and Cardinal Health, Inc. (U.S.), the high adoption of advanced wound closure devices in hospitals & clinics, the increasing cases of chronic wounds such as diabetic foot ulcers, and favorable reimbursement policies in the region.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest growth rate of 7.8% during the forecast period. The growth of this regional market is driven by the rising awareness about wound care & management, improving healthcare systems in countries such as China and India, increasing healthcare expenditures, and the growing demand for cost-effective advanced wound closure products.
Competitive landscape
- July 2024
SYNDEO Medical (Belgium) partnered with Clozex Medical, Inc. (U.S.) to boost patient care and transform wound closure solutions across the globe.
- August 2020
Futura Surgicare Pvt Ltd (India) launched Dolphin Sutures, a knotless wound closure device to alter the suturing experience for surgeons and establish the groundwork for creating new surgical methods that impact surgeons’ restoration and healing experience.
- April 2020
Medline Industries, LP (U.S.) partnered with BandGrip (U.S.) to expand the market reach of the company’s surgical wound closure innovations.
- 3M Company (U.S.)
- Medtronic plc · Ireland
- Cardinal Health, Inc. (U.S.)
- Johnson & Johnson Services, Inc. (U.S.)
- B. Braun Melsungen AG · Germany
- Essity AB · Sweden
- Medline Industries
- LP (U.S.)
- Stryker Corporation (U.S.)
- Smith & Nephew plc (U.K.)
- Integra LifeSciences Corporation (U.S.)
- Organogenesis Inc. (U.S.)
- Coloplast A/S · Denmark
- Convatec Group plc (U.K.)
- Corza Medical (U.S.). The top 4-5 players
Frequently asked questions
This study offers a detailed assessment of the wound closure market and analyzes the market sizes & forecasts based on product, wound type, and end user. This report also provides value analyses of various segments and subsegments of the wound closure market at the regional and country levels.
Cite this report
Meticulous Research. (2024). Wound Closure Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MR-1153). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/wound-closure-market-5836