Very Small Aperture Terminal (VSAT) Market (2026-2036)
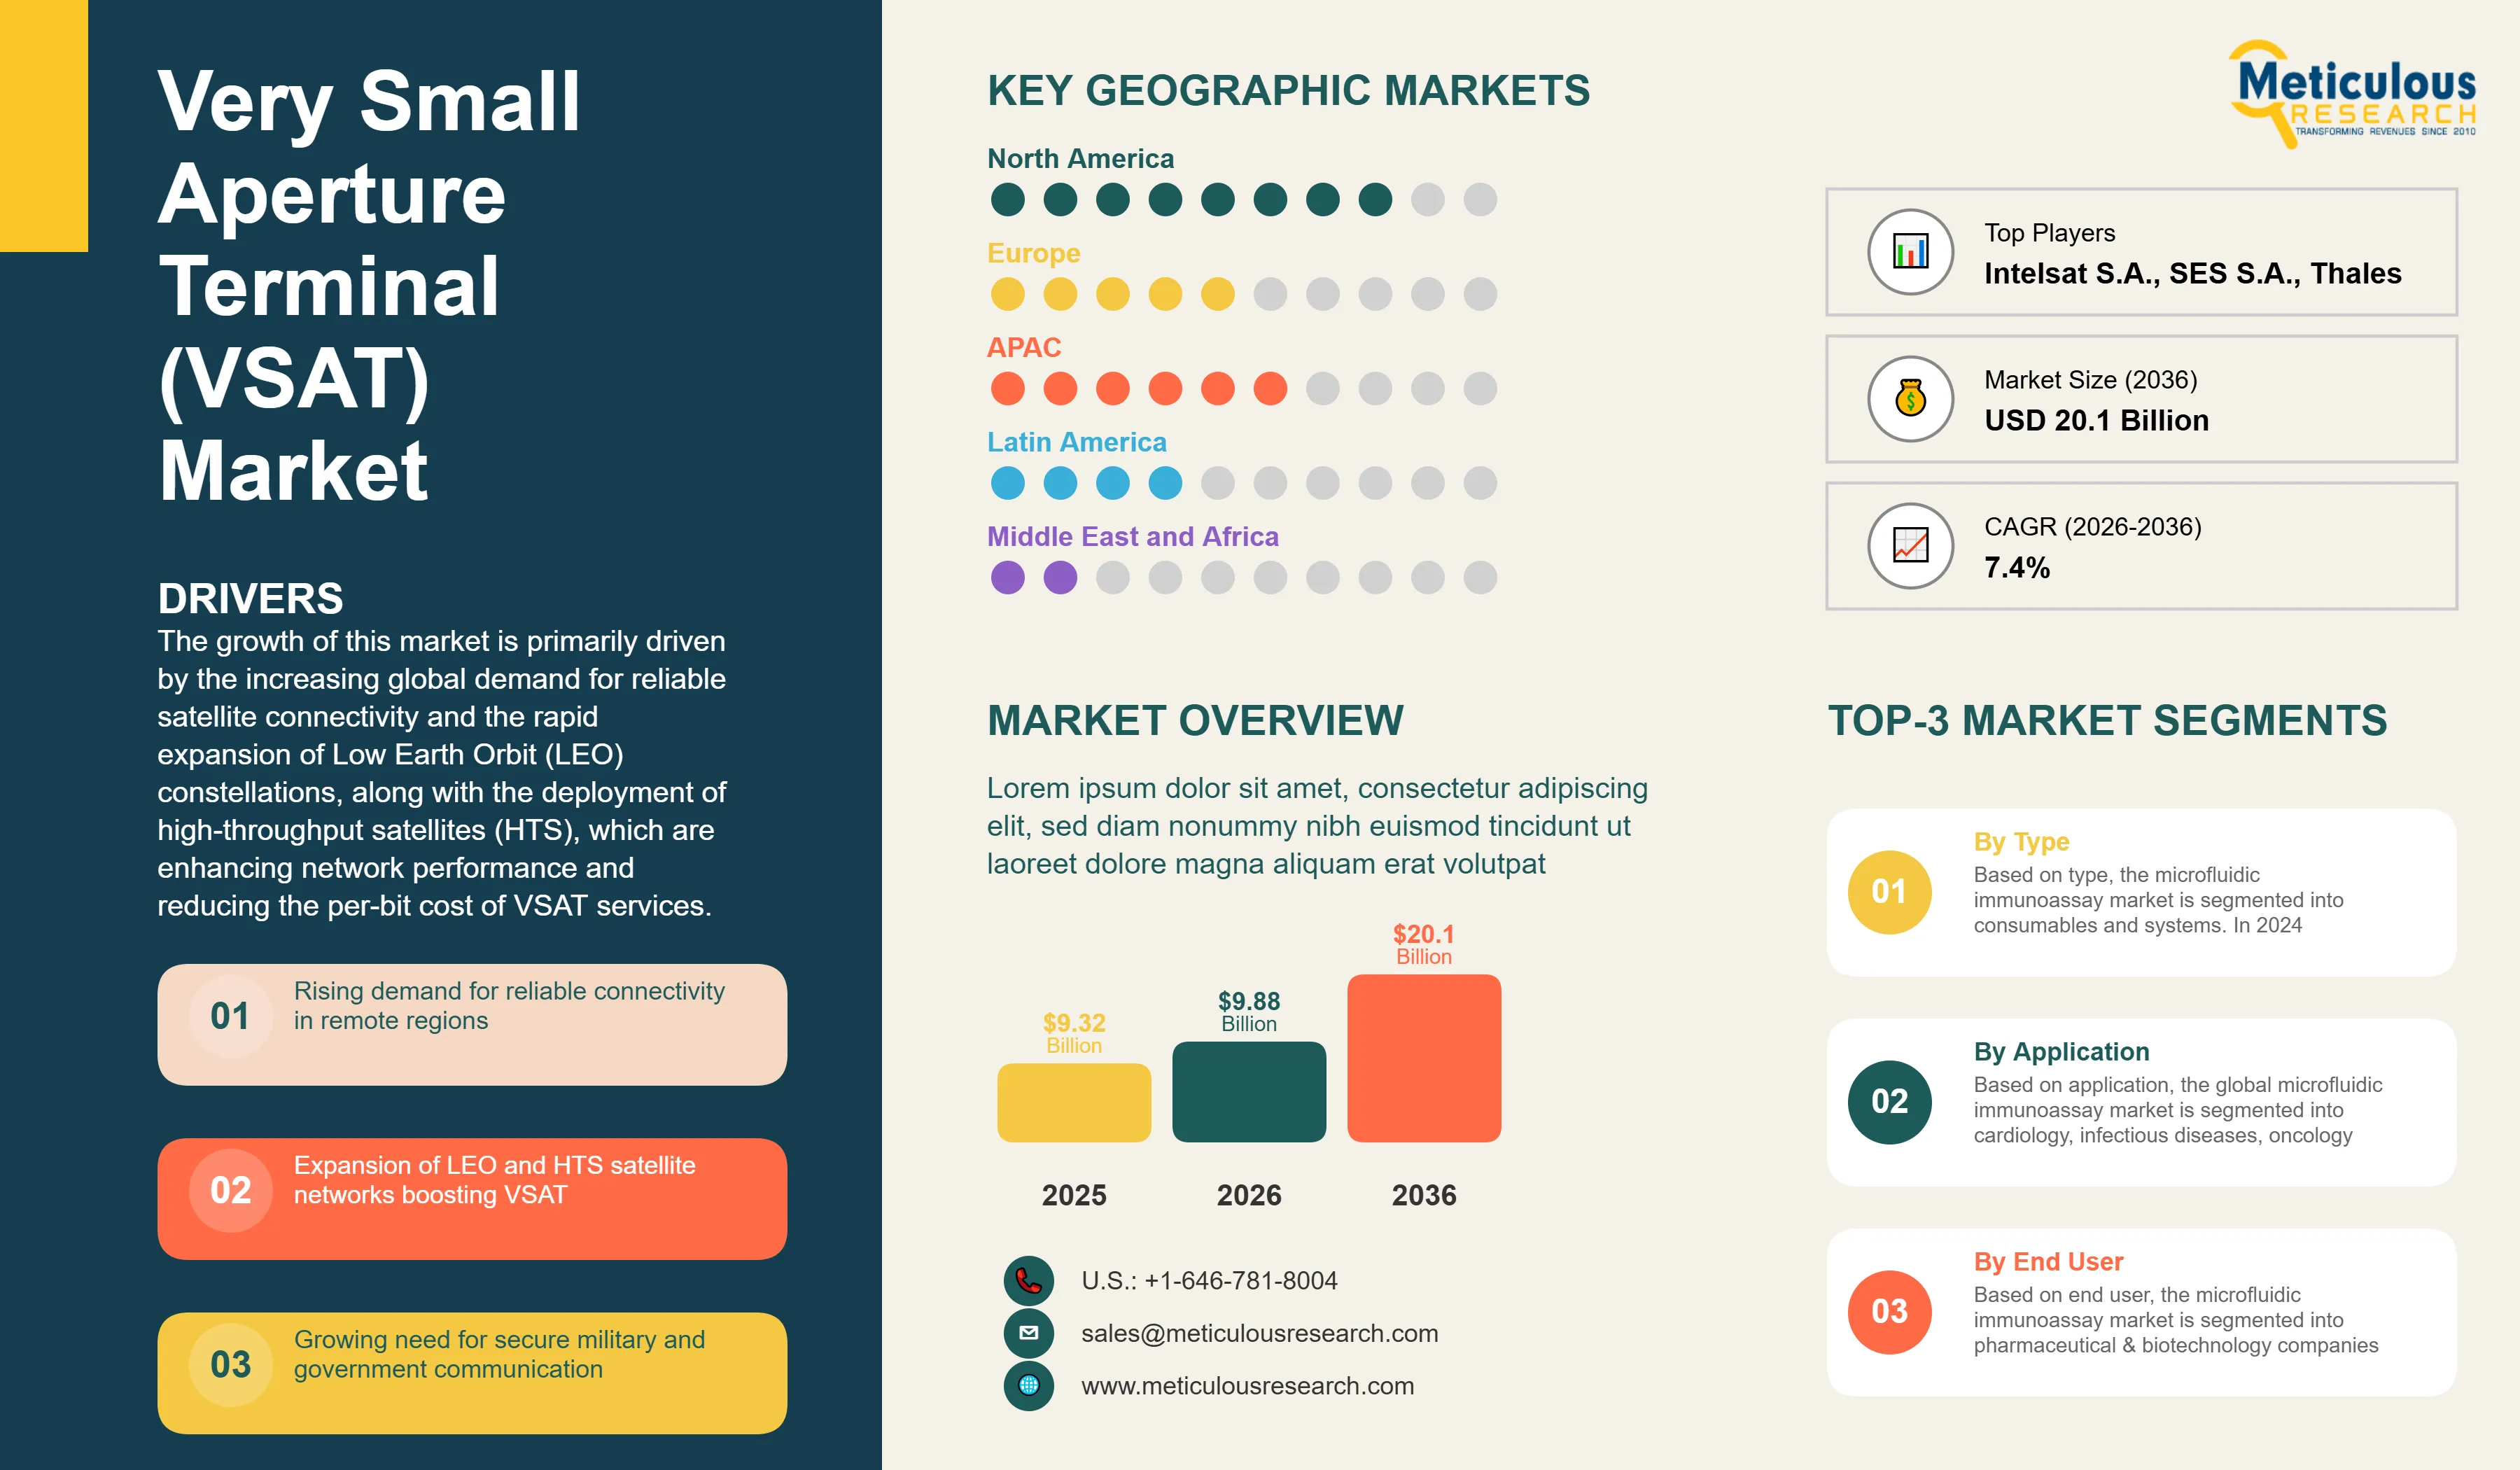
The global very small aperture terminal (VSAT) market was valued at USD 9.32 billion in 2025. This market is expected to reach USD 20.1 billion by 2036 from an estimated USD 9.88 billion in 2026, growing at a CAGR of 7.4% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 265
- Format
- PDF + Excel
- Report ID
- MR-1882
- Base year
- 2025
- 2025 · BASELINE
- $9.32B
- 2036
- $20.10B
- CAGR 2026–2036
- 7.4%
2025 baseline · 2026–2036 forecast at 7.4% CAGR · hover a bar for the value
Key highlights
The global VSAT market is projected to reach USD 20.1 billion by 2036.
The market is expected to grow at a CAGR of 7.4% during the forecast period 2026–2036.
The global VSAT market was valued at USD 9.32 billion in 2025 and is estimated to reach USD 9.88 billion in 2026.
North America dominates the global VSAT market with the largest market share in 2026, driven by extensive defense investments and the presence of leading satellite operators such as Hughes Network Systems and Viasat in the U.S.
Asia Pacific is expected to witness the fastest growth during the forecast period, driven by massive infrastructure development and the rapid adoption of satellite communication in China, India, and Southeast Asia, including government broadband initiatives and expanding maritime operations.
By frequency band, the Ku-band segment holds the largest share in 2026, particularly in supporting commercial broadband services, maritime operations, and established enterprise networks.
By frequency band, the Ka-band segment is expected to grow at the highest CAGR during the forecast period, driven by the growing need for high-throughput capacity and next-generation high-throughput satellite integration.
By platform, the land segment holds the largest market share in 2026, due to its widespread adoption across enterprise, commercial, and government applications.
By platform, the maritime segment is expected to witness the fastest growth during the forecast period, driven by the rapid digitalization of vessel operations, crew welfare connectivity requirements, and the expanding global shipping fleet.
By network architecture, the star topology segment holds the largest share in 2026, while the mesh topology segment is projected to grow steadily, driven by defense and emergency services demand.
By end-use, the government and military segment holds the largest share of the overall market in 2026, driven by the critical need for secure, resilient communication networks and substantial defense budgets.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 20.1 Billion |
| Market Size in 2026 | USD 9.88 Billion |
| Market Size in 2025 | USD 9.32 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 7.4% |
| Format | PDF, Excel & Cloud Portal · 265 pages |
| Dominating Frequency Band | Ku-Band |
| Fastest Growing Frequency Band | Ka-Band |
| Dominating Platform | Land |
| Fastest Growing Platform | Maritime |
| Dominating Network Architecture | Star Topology |
| Fastest Growing Network Architecture | Mesh Topology |
| Dominating Solution | Equipment |
| Fastest Growing Solution | Services |
| Dominating End-Use | Government & Military |
| Fastest Growing End-Use | Commercial & Enterprise |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: frequency band, platform, network architecture, solution, end-use.
The global very small aperture terminal (VSAT) market comprises advanced satellite communication systems that utilize small-aperture ground terminals, typically with antenna diameters ranging from 0.75 meters to 2.4 meters, to provide robust bidirectional connectivity across extensive geographic areas through satellite networks. These systems include terminals, antennas, modems, hub infrastructure, signal processing equipment, network management software, and associated managed and professional services designed to enable reliable voice, data, and video transmission, particularly in locations where terrestrial communication infrastructure is limited, unreliable, or unavailable.
The market also includes advanced technologies such as electronically steerable flat-panel antennas, software-defined networking (SDN) platforms, high-throughput satellite (HTS) integration, and multi-orbit connectivity management capabilities that enhance connection speeds, operational flexibility, terminal mobility, and service reliability in demanding remote and mobile environments. The scope of this market covers deployments across land, maritime, airborne, enterprise, government, defense, energy, and telecom applications.
The growth of this market is primarily driven by the increasing global demand for reliable satellite connectivity and the rapid expansion of Low Earth Orbit (LEO) constellations, along with the deployment of high-throughput satellites (HTS), which are enhancing network performance and reducing the per-bit cost of VSAT services.
In addition, the growing need for secure and low-latency connectivity across maritime vessel operations, commercial aviation in-flight connectivity, and remote energy infrastructure, where terrestrial network access remains limited or unavailable, further drives the growth of the overall VSAT market.
Moreover, the growing digital transformation of enterprises and government organizations, mainly across emerging economies, is driving the demand for satellite connectivity as a foundational infrastructure for cloud-based applications and distributed operations.
However, the high upfront capital investment required for VSAT terminal equipment and hub infrastructure, spectrum availability constraints across congested frequency bands in high-demand geographic regions, and the increasing competitive pressure from LEO broadband service providers offering lower-latency alternatives to traditional GEO-based VSAT services restrain the growth of this market.
On the other hand, the rapid commercialization of electronically steerable flat-panel antenna technology, which enables cost-effective multi-orbit terminal deployments across mobile platforms, offers significant growth opportunities for market players.
Furthermore, the increasing integration of VSAT systems with edge computing and industrial IoT ecosystems, transforming satellite terminals into intelligent edge nodes, along with the growing adoption of software-defined networking (SDN) and cloud-based network management platforms for VSAT infrastructure, is expected to create substantial market growth opportunities.
Furthermore, the transition toward multi-orbit VSAT architectures capable of seamless switching between GEO and LEO satellites is a major trend shaping the growth of this market.
The land segment also benefits from relatively simpler and more cost-effective fixed terminal configurations compared to maritime and airborne deployments.
Unlike mobile applications, land-based VSAT systems typically do not require stabilized antenna platforms or advanced multi-orbit tracking capabilities, resulting in lower per-terminal deployment costs and a broader addressable market base.
Furthermore, the increasing regulatory and commercial need to provide crew welfare broadband internet connectivity is emerging as a critical factor driving market growth, particularly in relation to seafarer recruitment and retention.
With the global commercial shipping fleet representing a large installed and potential terminal base, and VSAT penetration still relatively low across several vessel categories, the maritime segment is expected to offer substantial greenfield deployment opportunities over the forecast period.
The hub-and-spoke configuration of star topology, wherein all remote terminals communicate through a central hub, enables service providers and solution vendors to deliver scalable and predictable managed connectivity services across hundreds or thousands of distributed locations.
This architecture continues to be widely adopted across enterprise broadband and institutional communication networks due to its operational efficiency and ease of management.
However, the mesh topology segment is expected to witness steady growth during the forecast period.
The growth of this segment is primarily driven by the increasing adoption of VSAT systems across military communications, emergency response networks, disaster recovery operations, and tactical satellite communication applications that require direct site-to-site connectivity without reliance on a centralized hub.
This architecture is particularly critical for defense and mission-critical deployments, where minimizing hub dependency and eliminating single points of failure are key operational requirements.
As a result, the growing demand for resilient and decentralized communication networks is expected to drive steady growth in the mesh topology segment through 2036.
In addition, enterprise VSAT deployments across oil & gas, mining, utilities, and remote industrial operations continue to generate relatively high average revenue per terminal due to the mission-critical nature of connectivity requirements in these sectors.
Report infographic
Market dynamics
3 factors across 1 forceRapid Deployment of LEO Satellite Constellations Transforming VSAT Economics and Performance
The rapid commercial deployment of Low Earth Orbit (LEO) and Medium Earth Orbit (MEO) satellite constellations, including SpaceX’s Starlink Business services for maritime and aviation applications, Eutelsat OneWeb’s enterprise connectivity solutions, and SES’s O3b mPOWER platform, is significantly transforming the performance and economic landscape of the VSAT market. These next-generation satellite systems offer substantially lower latency, higher per-terminal throughput, and improved link availability compared to traditional GEO-based VSAT systems, mainly across high-demand maritime shipping routes, aviation corridors, and remote enterprise deployments. For instance, while conventional GEO VSAT systems typically operate with latency exceeding 550 milliseconds, LEO services can reduce latency significantly, while MEO platforms such as O3b mPOWER offer predictable latency of around 150 milliseconds.
This evolving competitive landscape is increasing pressure on traditional Ku-band and Ka-band GEO VSAT operators, including Hughes Network Systems, LLC, Viasat, Inc., and Intelsat S.A., particularly across maritime, enterprise, and mobility-focused applications. As a result, incumbent players are increasingly driving investments in LEO integration and multi-orbit terminal solutions to maintain service competitiveness and improve customer value propositions.
While this shift is expected to moderate the average revenue per user (ARPU) growth of traditional GEO VSAT services, it is also creating significant opportunities for hybrid GEO-LEO and GEO-MEO architectures that optimize network cost, performance, latency, and service reliability across diverse end-use environments.
Innovation in Flat-Panel Electronically Steerable Antennas Enabling Mobile VSAT at Scale
The transition from mechanically steered parabolic dish antennas to electronically steerable flat-panel antennas (ESAs) is one of the most significant hardware innovations transforming the economics and scalability of the VSAT market. These antennas leverage phased-array technology to electronically direct and track satellite beams without the need for moving mechanical parts, enabling reliable connectivity across highly mobile platforms such as vessels, aircraft, and ground vehicles.
This technological advancement is significantly improving terminal mobility, reducing maintenance requirements, and enabling low-profile installations that were previously difficult to achieve with conventional dish-based systems. Unlike traditional parabolic antennas that often require bulky radomes and stabilized mechanical assemblies, flat-panel ESAs support streamlined form factors suitable for aircraft fuselages, vessel superstructures, and land mobility applications where aerodynamic and structural constraints limit the use of conventional systems.
Leading players such as Kymeta Corporation, Intellian Technologies, Inc., and other satellite connectivity solution providers are accelerating the commercialization of flat-panel and multi-orbit antenna systems to support maritime, aviation, and defense applications. As ongoing commercialization and technological advancements continue to reduce system costs, mobile VSAT adoption is expected to expand across vessel and aircraft classes that were previously considered economically unviable for complex stabilized dish systems. This is expected to create significant growth opportunities for VSAT solution providers over the forecast period.
VSAT Integration with Edge Computing and Industrial IoT Ecosystems
The integration of VSAT connectivity with edge computing and industrial Internet of Things (IIoT) ecosystems is transforming satellite terminals from conventional connectivity endpoints into intelligent edge nodes capable of local data processing, real-time decision-making, and selective data transmission. This convergence significantly reduces satellite bandwidth consumption while enabling faster response times and real-time operational visibility across remote and infrastructure-constrained environments.
In energy and industrial operations, VSAT-connected sensors used for pipeline integrity monitoring, wellhead pressure management, asset performance tracking, and predictive maintenance are increasingly processing critical data locally at the terminal edge, transmitting only alerts, exceptions, and aggregated datasets over satellite links. This approach is improving the economic viability of industrial IoT deployments by optimizing bandwidth utilization and reducing communication costs.
Furthermore, the growing integration of VSAT with operational technology (OT) systems across maritime fleet management, mining automation, utilities monitoring, and remote control applications is creating new opportunities for vertical-specific managed services and high-value connectivity solutions. These specialized service offerings are expected to support premium pricing compared to conventional broadband-based VSAT services, thereby creating significant revenue growth opportunities for market players over the forecast period.
Table of contents
13 chapters · 191 sections · 265 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Frequency Band | Ku-band | Ka-band |
| By Platform | Land | Maritime |
| Other segments | Land | Maritime |
| By Network Architecture | Star topology | — |
| By End-use | Government and military | — |
By Frequency Band
- The global very small aperture terminal (VSAT) market is segmented into C-band, Ku-band, Ka-band, X-band, and multi-band.
- The Ku-band segment is expected to account for the largest share of the global VSAT market.
- The large share of this segment is primarily attributed to the extensive deployment of Ku-band VSAT infrastructure across commercial maritime operations, enterprise broadband networks, and government communication systems.
- Over the years, continuous Ku-band satellite capacity deployment has resulted in a large installed base of compatible terminals, well-established service ecosystems, and proven operational frameworks across major end-use industries.
- In addition, Ku-band offers a favorable balance between antenna size requirements, service reliability, and satellite capacity availability across major geostationary orbital slots, making it one of the most widely adopted frequency bands for operational VSAT networks globally.
- Compared to Ka-band, Ku-band is also relatively less susceptible to rain fade, which further drives its adoption across maritime, enterprise, and mobility applications.
- Furthermore, large-scale deployments across Asia-Pacific and North America, mainly in maritime and commercial sectors, continue to drive the dominance of this segment.
- However, the Ka-band segment is expected to grow at the fastest CAGR during the forecast period.
- The high growth of this segment is primarily driven by the increasing demand for high-throughput satellite capacity, the growing deployment of next-generation HTS systems, and the rising integration of advanced satellite constellations, including platforms such as Viasat-3 and EchoStar’s Jupiter series.
- Furthermore, the superior spectral efficiency of Ka-band and its support for frequency reuse through multi-beam architectures enable significantly lower cost per bit compared to conventional Ku-band systems, making it highly suitable for high-density bandwidth applications such as in-flight connectivity, maritime broadband, enterprise networks, and remote industrial operations.
- This is expected to drive strong growth in the Ka-band segment over the forecast period.
- Furthermore, the growing demand for X-band and Ka-band military satellite communication services, along with government-led broadband initiatives for rural and remote connectivity, is creating a large and relatively stable VSAT procurement base.
- Compared to commercial deployments, this segment remains less susceptible to competitive pressure from commercial LEO broadband services due to its stringent requirements related to security, survivability, network redundancy, and operational continuity.
By Platform
- The global very small aperture terminal (VSAT) market is segmented into land, maritime, and airborne.
Other segments
- The land segment is expected to hold the largest share of the global VSAT market.
- The large market share of this segment is primarily attributed to the extensive deployment of VSAT systems across fixed enterprise and institutional sites for remote connectivity applications in industries such as oil & gas, mining, energy, retail, banking and financial services, education, and healthcare.
- In addition, the significant deployment of fixed VSAT terminals across government and military sites further drives the dominance of this segment.
- However, the maritime segment is expected to register the highest CAGR during the forecast period.
- The high growth of this segment is primarily driven by the rapid digitalization of vessel operations, including bridge navigation systems, engine room monitoring, cargo management automation, and compliance-related communication systems such as AIS and GMDSS.
- The star topology segment is expected to account for the largest share of the global VSAT market.
- The large share of this segment is primarily attributed to its strong suitability for centralized network management, cost-effective hub operations, and simplified deployment across multiple remote sites.
- These advantages make star topology the preferred architecture for enterprise, commercial, retail, banking, education, and other large-scale VSAT deployments that require centralized monitoring, bandwidth allocation, service management, and billing capabilities.
- The government & military segment is expected to hold the largest share of the global VSAT market.
- The large market share of this segment is primarily attributed to the critical need for secure, resilient, and mission-critical communication networks across defense and government operations.
- In addition, the presence of substantial defense budgets, particularly across the U.S., NATO member states, and major Asia-Pacific economies, continues to support the procurement of encrypted, anti-jamming, and high-reliability VSAT systems for tactical as well as strategic military communications.
- The commercial and enterprise segments collectively account for a substantial and steadily growing share of the global VSAT market.
- Maritime VSAT is expected to witness the fastest growth during the forecast period, driven by increasing vessel digitalization and crew connectivity requirements.
By Network Architecture
- The global very small aperture terminal (VSAT) market is segmented into star topology, mesh topology, and hybrid network.
By End-use
- The global very small aperture terminal (VSAT) market is segmented into government & military, commercial (maritime, aviation, oil & gas, mining & energy), enterprise (banking, financial services, and insurance, retail, education, and healthcare), and other end-use industries.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to hold the largest share of the global VSAT market. The large market share of this region is primarily attributed to the substantial defense expenditure of the U.S., which remains one of the largest individual procurement markets for secure satellite communication systems across defense, intelligence, and government applications. In addition, the presence of leading VSAT equipment manufacturers and service providers, including Hughes Network Systems, LLC, Viasat, Inc., Comtech Telecommunications Corp., and L3Harris Technologies, Inc., further supports the region’s market dominance. Furthermore, the extensive deployment of VSAT systems across enterprise, government, maritime, and aviation connectivity applications, along with high adoption of advanced satellite communication infrastructure, continues to strengthen North America’s leading position in the global market.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is expected to register the highest CAGR during the forecast period. The rapid growth of this region is primarily driven by the significant expansion of maritime VSAT deployments across major shipping economies such as China, South Korea, Japan, and Southeast Asian countries. In addition, increasing government-led broadband connectivity initiatives across India, Indonesia, the Philippines, and other emerging economies are supporting the deployment of satellite-based communication infrastructure for rural and remote connectivity. The growing expansion of offshore oil & gas operations, mining activities, and remote industrial infrastructure across Southeast Asia and Australia is further driving demand for reliable VSAT communication systems. Moreover, the increasing procurement of defense satellite communication systems across China, India, Japan, and South Korea is expected to support robust regional market growth. Furthermore, the large rural population base across several Asia-Pacific countries, where VSAT often remains one of the most viable broadband delivery solutions for remote communities and industrial sites, is expected to create substantial growth opportunities for market participants over the forecast period.
Competitive landscape
- Hughes Network Systems, LLC (U.S.)
- Viasat, Inc. (U.S.)
- Gilat Satellite Networks Ltd. · Israel
- ST Engineering iDirect, Inc. (U.S.)
- Comtech Telecommunications Corp. (U.S.)
- L3Harris Technologies, Inc. (U.S.)
- Cobham Satcom Ltd. (U.K./Denmark)
- Inmarsat Global Limited (U.K.)
- KVH Industries, Inc. (U.S.)
- SES S.A. · Luxembourg
- Eutelsat Communications S.A. · France
- EchoStar Corporation (U.S.)
- Orbit Communication Systems Ltd. · Israel
- Thales S.A. · France
- Speedcast International Limited · Australia
Frequently asked questions
The global VSAT market is expected to reach USD 20.1 billion by 2036 from an estimated USD 9.88 billion in 2026, at a CAGR of 7.4% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Very Small Aperture Terminal (VSAT) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1882). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/very-small-aperture-terminal-market-6565