Small Satellite Market (2026-2036)
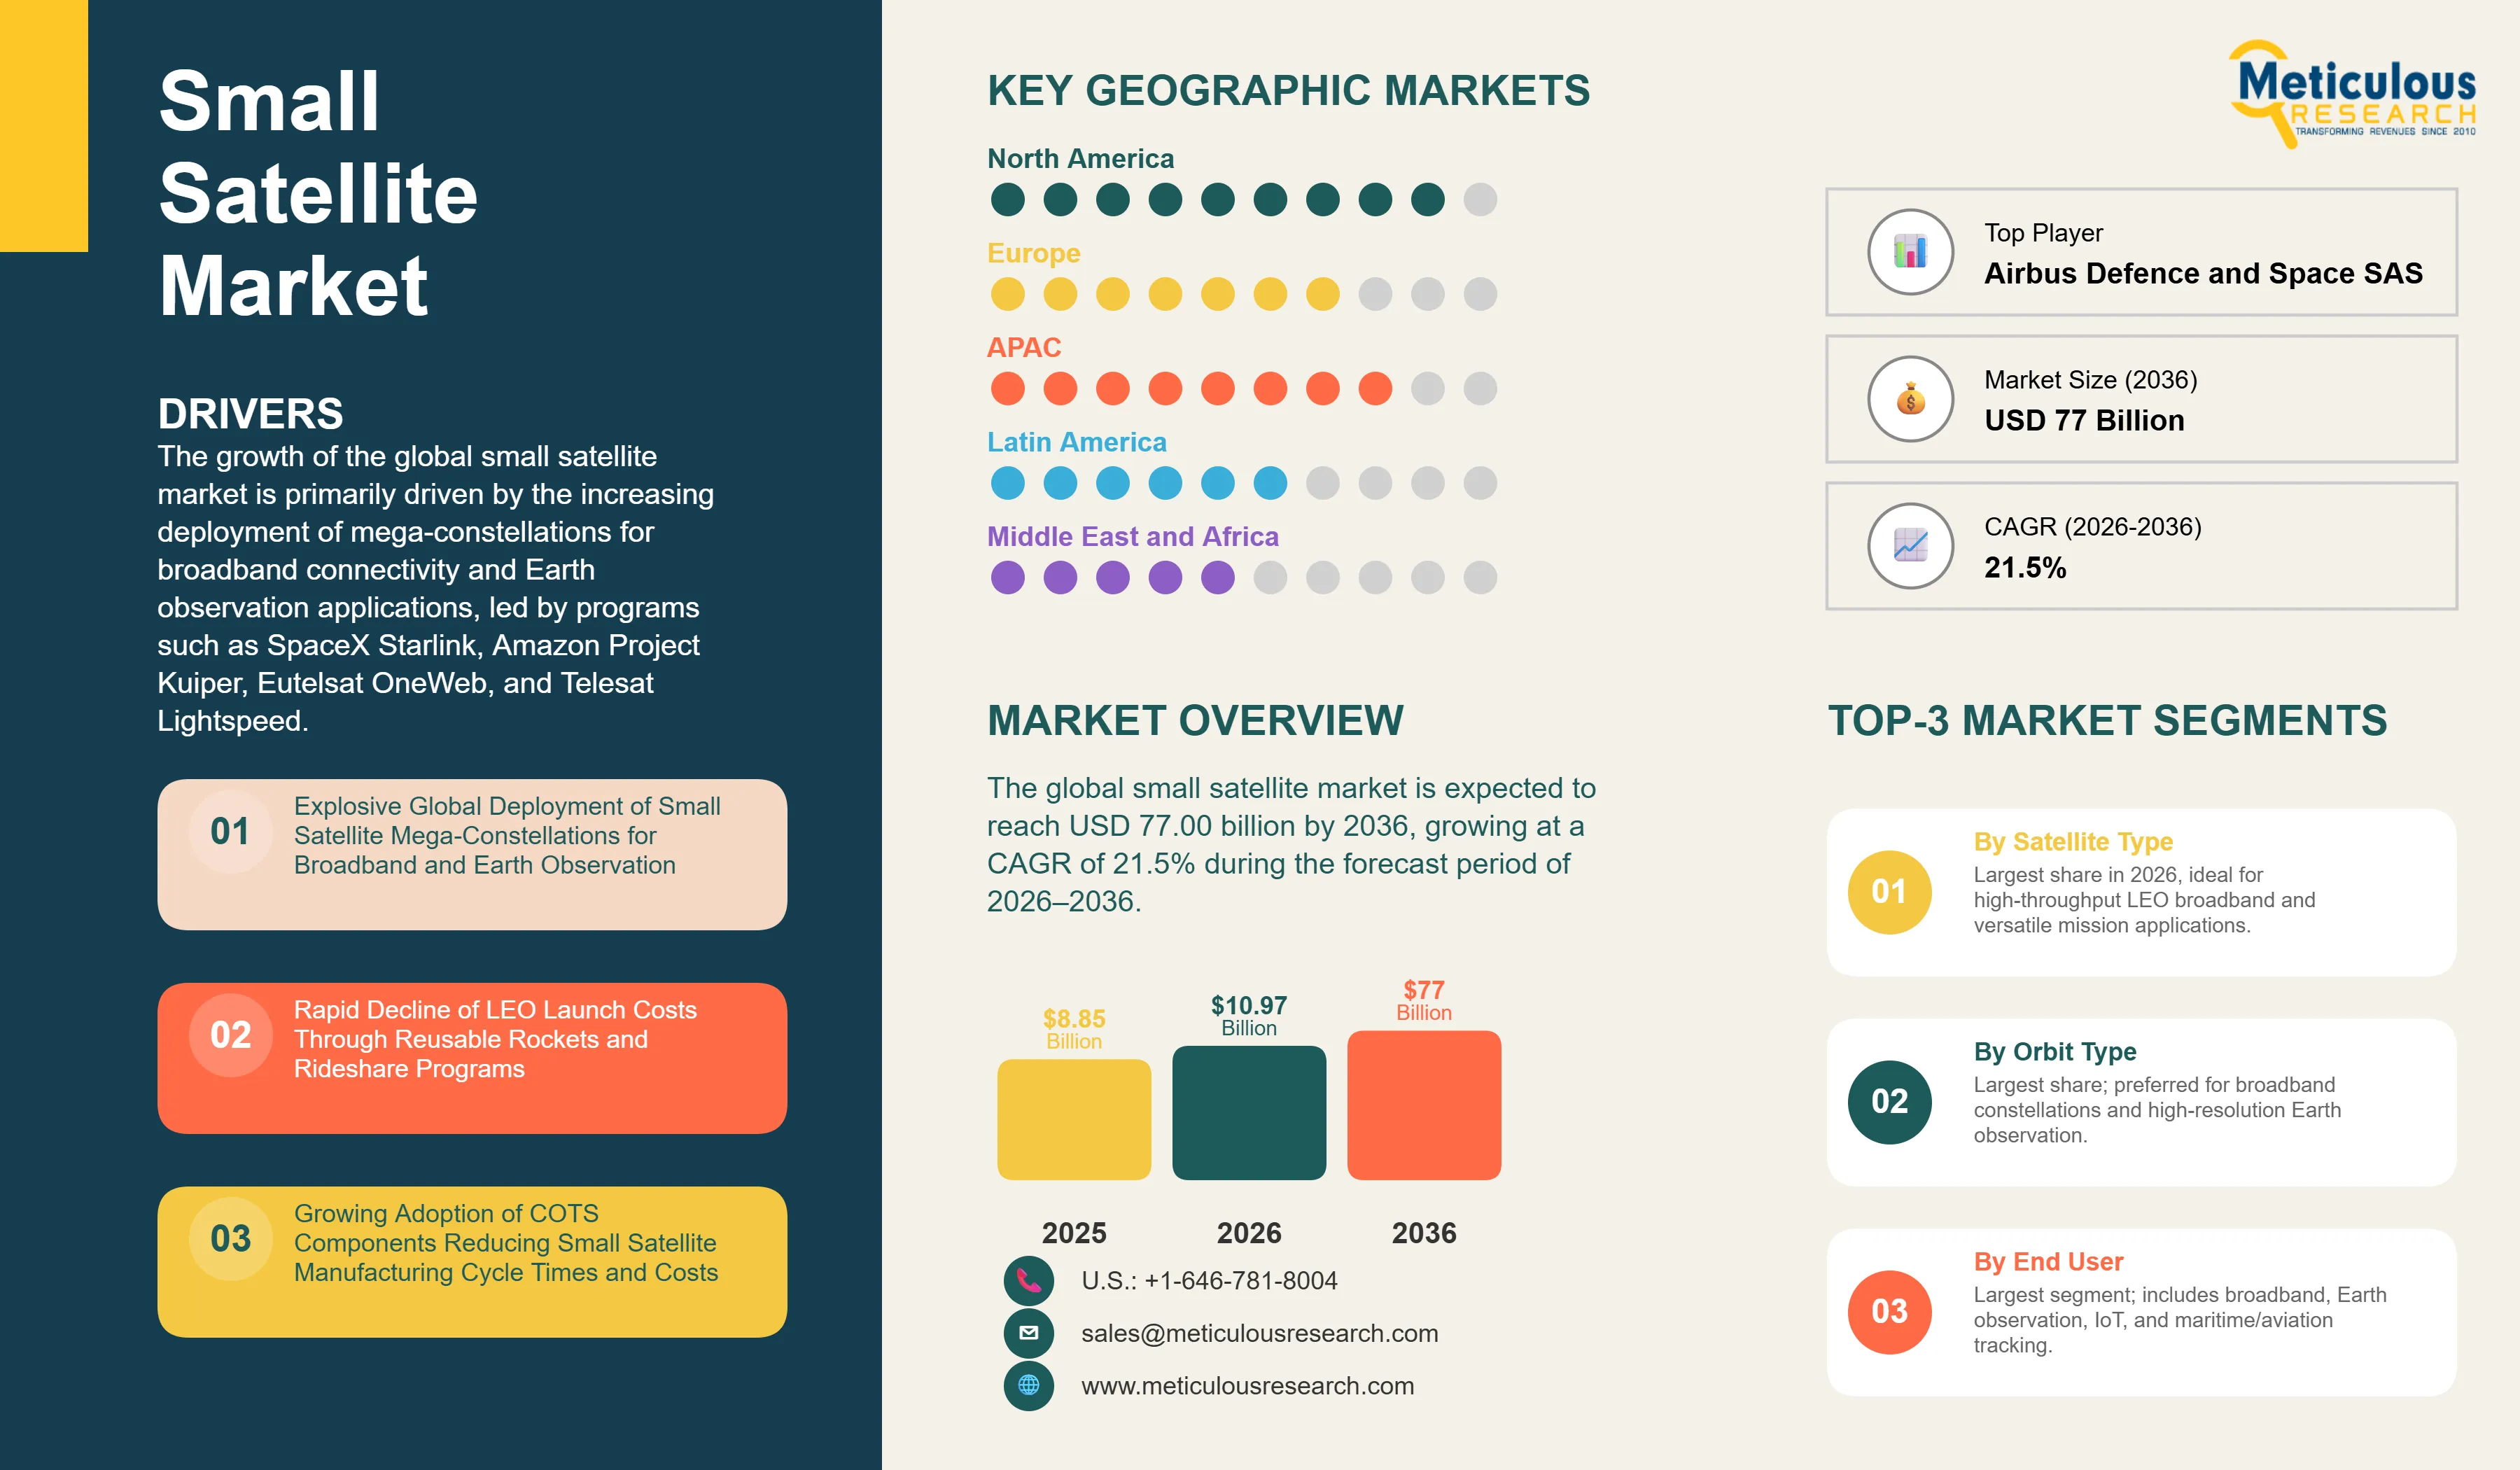
The global small satellite market was valued at USD 8.85 billion in 2025. This market is expected to reach USD 77.00 billion by 2036 from an estimated USD 10.97 billion in 2026, growing at a CAGR of 21.5% during the forecast period of 2026–2036.
- Published
- Apr 2026
- Pages
- 293
- Format
- PDF + Excel
- Report ID
- MR-1871
- Base year
- 2025
- 2025 · BASELINE
- $8.85B
- 2036
- $77.00B
- CAGR 2026–2036
- 21.5%
2025 baseline · 2026–2036 forecast at 21.5% CAGR · hover a bar for the value
Key highlights
The global small satellite market is projected to reach USD 77 billion by 2036.
The market is expected to grow at a CAGR of 21.5% during the forecast period 2026–2036.
The global small satellite market was valued at USD 8.85 billion in 2025 and is estimated to reach USD 10.97 billion in 2026.
North America is expected to dominate the global small satellite market with the largest share of around 40–45% in 2026, driven by the highest concentration of small satellite operators and launch service providers including SpaceX, Amazon, Rocket Lab, and Planet Labs, strong government and defense procurement through NASA, DARPA, the U.S. Space Force, and the National Reconnaissance Office, and the most advanced small satellite manufacturing ecosystem in the world.
Asia Pacific is projected to witness the fastest growth during the forecast period, driven by massive national space program investments in China, India, Japan, and South Korea, the rapid emergence of commercial space ecosystems in these markets, and the increasing domestic deployment of small satellite constellations for communications, Earth observation, and surveillance applications.
By satellite type, minisatellites are expected to hold the largest share of the overall small satellite market, driven by their optimal balance of capability, cost, and mission versatility.
By satellite type, the nanosatellites and CubeSats segment is projected to register the highest CAGR during the forecast period, driven by rapid growth in deployment volumes, regulatory deorbit mandates expanding the propulsion-equipped CubeSat market, and the proliferation of CubeSat platforms for academic, defense, and commercial Earth observation missions.
By subsystem, the payloads and structures segment is expected to account for the largest share of the global small satellite market in 2026.
By subsystem, the propulsion systems segment is projected to register the highest CAGR during the forecast period, driven by regulatory deorbit mandates and the growing adoption of electric propulsion for LEO constellation station-keeping.
By orbit type, low earth orbit is expected to account for the largest share of the market in 2026, reflecting the dominant role of LEO mega-constellation deployments.
By application, the communication segment is expected to account for the largest share in 2026, while the earth observation and remote sensing segment is projected to register the highest CAGR during the forecast period.
By end user, the commercial segment is expected to hold the largest share in 2026, while the government and defense segment is projected to register the fastest growth during the forecast period.
By geography, North America is expected to dominate the global small satellite market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 77.00 Billion |
| Market Size in 2026 | USD 10.97 Billion |
| Market Size in 2025 | USD 8.85 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 21.5% |
| Format | PDF, Excel & Cloud Portal · 293 pages |
| Dominating Satellite Type | Minisatellites |
| Fastest Growing Satellite Type | Nanosatellites/CubeSats |
| Dominating Subsystem | Payloads & Structures |
| Fastest Growing Subsystem | Propulsion Systems |
| Dominating Orbit | Low Earth Orbit (LEO) |
| Dominating Application | Communication |
| Fastest Growing Application | Earth Observation & Remote Sensing |
| Dominating End User | Commercial |
| Fastest Growing End User | Government & Defense |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: satellite type, subsystem, orbit type, application, end user.
The growth of the global small satellite market is primarily driven by the increasing deployment of mega-constellations for broadband connectivity and Earth observation applications, led by programs such as SpaceX Starlink, Amazon Project Kuiper, Eutelsat OneWeb, and Telesat Lightspeed. In addition, the significant reduction in launch costs enabled by reusable launch vehicle technologies and rideshare missions has made large-scale deployment of small satellites increasingly economically viable. The growing adoption of commercial off-the-shelf (COTS) components is further driving market growth by substantially reducing manufacturing cycle times and lowering per-unit production costs.
However, the relatively shorter operational lifespan of small satellites compared with conventional large satellites, typically 5–7 years versus more than 15 years, results in higher replacement and replenishment costs over the mission lifecycle. Furthermore, increasing congestion across low Earth orbit (LEO) orbital shells is elevating collision risks and adding to regulatory and space traffic management complexities. Supply chain constraints related to specialized components, mainly radiation-hardened electronics, advanced sensors, and propulsion hardware, also remain key restraints to market growth.
The increasing deployment of LEO-based infrastructure to complement 5G and next-generation communication networks, growing government and defense procurement of proliferated satellite architectures for resilient surveillance, intelligence, and secure communications, and the growing use of satellite-derived data across agriculture, maritime monitoring, logistics, and climate intelligence applications are expected to create significant growth opportunities for market players. Moreover, the continued miniaturization of satellite bus platforms, enabling compact and cost-efficient spacecraft to perform missions that previously required significantly larger satellites, is emerging as a major trend shaping the evolution of this market.
Report infographic
Market dynamics
3 factors across 1 forceMega-Constellation Manufacturing at Industrial Scale Transforming Satellite Production Economics
The deployment of satellite mega-constellations at industrial scale is transforming small satellite manufacturing from a project-based, artisanal industry into a high-volume, assembly-line manufacturing sector with economics more analogous to commercial aviation than traditional spacecraft production. SpaceX's Starlink manufacturing facility in Redmond, Washington, produces approximately 70+ satellites per week, a throughput that exceeds the total annual production of most national space agencies, using automotive-inspired production line techniques, COTS components, and aggressive supplier integration.
This manufacturing scale is significantly reducing per-unit satellite production costs, driving supply chain standardization, and fostering the emergence of a new class of small satellite component and subsystem suppliers capable of delivering thousands of units annually. In addition, the constellation manufacturing paradigm is enabling new business models, including satellite-as-a-service, data-as-a-service, and connectivity-as-a-service, which are attracting substantial venture capital and strategic investments across the global space ecosystem.
Proliferated Defense Satellite Architectures Driving Government Small Satellite Procurement
The growing adoption of proliferated low‑Earth orbit (LEO) satellite architectures by defense agencies is creating a substantial and rapidly growing government procurement market for small satellites. Under this architecture, surveillance, secure communications, and missile‑warning capabilities are distributed across dozens to hundreds of smaller satellites, rather than being concentrated in a limited number of large, high‑value, strategically vulnerable spacecraft.
A key example is the U.S. Space Development Agency’s (SDA) Proliferated Warfighter Space Architecture (PWSA), which includes the Transport Layer and Tracking Layer constellations designed to provide low‑latency military communications, resilient data relay, and missile warning and tracking capabilities. The SDA has already awarded contracts for more than 430 satellites across multiple tranches, with cumulative contract values reaching several billion dollars. Recent awards include multiple multi‑billion‑dollar multi‑vendor contracts for Tranche 3 Tracking Layer satellites supplied by primes such as Lockheed Martin Corporation, Northrop Grumman Corporation, L3Harris Technologies, Inc., and Rocket Lab USA, Inc., reflecting a shift toward large‑scale, tranche‑based small‑satellite procurement.
In addition, manufacturers such as York Space Systems LLC and Terran Orbital Corporation continue to benefit from recurring tranche‑based procurement programs for advanced tactical communications and missile‑defense applications. Beyond the U.S., defense agencies in the U.K., Australia, France, Japan, and other allied nations are increasingly pursuing similar proliferated‑architecture strategies to strengthen space resilience and reduce single‑point mission vulnerabilities. This trend is broadening the defense small‑satellite procurement market beyond its historical U.S.‑centric concentration and is expected to remain a major driver of market growth over the forecast period.
AI and Onboard Processing Enabling Autonomous Small Satellite Operations
The integration of artificial intelligence and onboard processing into small satellite platforms, enabling autonomous anomaly detection, intelligent downlink scheduling, on‑orbit image processing, and adaptive mission planning with minimal reliance on continuous ground‑station contact, is expanding the mission capability envelope of small satellites and creating new commercial opportunities for satellite‑derived intelligence products.
Planet Labs’ Pelican constellation, for example, embeds advanced onboard AI and edge‑processing capabilities to support functions such as automated cloud detection and tasking optimization, thereby maximizing the collection of scientifically useful imagery per orbit. These onboard processing capabilities are particularly valuable for high‑volume constellations where the ground segment cannot practically manage every satellite contact, enabling the constellation to operate with a high degree of autonomy and significantly reducing operational cost per satellite.
Table of contents
13 chapters · 144 sections · 293 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Satellite Type | Minisatellites | Nanosatellites and CubeSats |
| By Subsystem | Payloads & Structures | Propulsion systems |
| By Orbit Type | Low Earth Orbit | — |
| By Application | Communication | Commercial |
| By End User | Commercial | Government and defense |
By Satellite Type
- The Minisatellites Segment to Dominate the Global Small Satellite Market
- The minisatellites segment is expected to account for the largest market share of the global small satellite market.
- The large share of this segment is attributed to the deployment of minisatellite-class platforms as the preferred configuration for high-throughput LEO broadband constellation nodes, where the higher mass envelope enables larger solar arrays for electric propulsion, more powerful communication payloads for high-capacity throughput, and longer operational lifespans that reduce replacement cadence costs.
- Starlink V2 Mini satellites at approximately 800 kg, OneWeb satellites at approximately 150 kg, and Telesat Lightspeed microsatellite nodes weighing in the 700–750 kg range all fall within the small‑satellite class, with OneWeb squarely in the minisatellite range and Starlink V2 Mini and Telesat Lightspeed at the upper‑end of the small‑satellite or lower‑medium‑satellite mass band.
- This positioning reflects their role as high‑capacity, high‑throughput communication platforms, for which average per‑unit revenue is typically among the highest in the commercial satellite market.
- However, the nanosatellites and CubeSats segment is projected to register the highest CAGR during the forecast period.
- The high growth of this segment is driven by the rapid growth in CubeSat deployment volumes across commercial Earth observation, IoT connectivity, technology demonstration, and academic missions; the regulatory mandate for end-of-life deorbit capability expanding the propulsion-equipped CubeSat addressable market; and the proliferation of standardized 3U, 6U, and 12U CubeSat platforms that enable rapid, low-cost mission deployment for a growing global base of commercial and academic operators.
By Subsystem
- The Payloads & Structures Segment to Hold the Largest Share
- The payloads and structures segment is expected to account for the largest share of the global small satellite market.
- The large share of this segment is attributed to the dominant revenue contribution of mission-specific payload equipment, including imaging sensors, communication transponders, scientific instruments, and radar systems, that constitute the highest-value content per satellite and determine the commercial mission utility and revenue-generating capability of each deployment.
- Advances in miniaturized sensor technology, software-defined radio, and on-orbit processing have significantly improved payload performance per unit mass, enabling smaller satellites to perform missions previously requiring much larger platforms.
- However, the propulsion systems segment is projected to register the highest CAGR during the forecast period.
- The strong growth of this segment is driven by the U.S. FCC’s five‑year deorbit rule and equivalent international regulations mandating propulsion capability across satellite classes that previously flew without it, the growing adoption of electric propulsion for low‑Earth orbit (LEO) constellation station‑keeping, and the increasing deployment of multi‑mode propulsion systems that combine chemical and electric technologies for mission‑specific optimization.
By Orbit Type
- Low Earth Orbit to Account for the Largest Share
- The LEO segment is expected to account for the largest share of the global small satellite market, reflecting the dominant role of LEO mega‑constellation deployments for broadband connectivity, Earth observation, and defense surveillance, as the primary driver of small satellite manufacturing volume.
- LEO’s advantage in launch cost, low‑latency communication performance, and suitability for high‑revisit Earth observation makes it the optimal orbit class for the vast majority of small satellite applications.
By Application
- The Communication Segment to Hold the Largest Share
- The communication segment is expected to account for the largest share of the global small satellite market.
- This dominance reflects the huge procurement volumes generated by low Earth orbit (LEO) broadband constellation deployments—SpaceX Starlink, Amazon Kuiper, OneWeb/Eutelsat, and Telesat Lightspeed—each requiring hundreds to thousands of communication satellite platforms to achieve global coverage.
- The commercial segment is expected to record the highest CAGR in the satellite market, driven by rising demand for high‑speed internet in underserved regions and the development of large‑scale LEO satellite constellations.
- However, the Earth observation and remote sensing segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is driven by the expanding commercial Earth observation data market, with operators such as Planet Labs, ICEYE, Satellogic, BlackSky, and numerous specialized firms deploying increasingly capable imaging and synthetic aperture radar (SAR) constellations, and by growing government investment in enhanced Earth observation capability for climate monitoring, disaster management, agricultural surveillance, and military intelligence applications, which small satellites uniquely support through high revisit frequency and global coverage.
By End User
- The Commercial Segment to Hold the Largest Share
- The commercial segment is expected to account for the largest share of the global small satellite market, reflecting the dominant role of private commercial operators as both the largest satellite deployers by volume and the primary drivers of small satellite manufacturing innovation.
- The commercial segment includes broadband connectivity operators, Earth observation data companies, IoT connectivity platform providers, maritime and aviation tracking services, and the broad ecosystem of data analytics companies that derive revenue from satellite‑collected information.
- However, the government and defense segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is driven by increasing national investment in proliferated low Earth orbit (LEO) satellite architectures for defense surveillance, strategic communications, and missile warning, with the U.S. Space Development Agency’s Transport Layer and Tracking Layer programs representing billions of dollars of committed small satellite procurement, and by growing investment in national commercial space programs across Europe, Japan, India, Australia, and the Middle East, creating sustained government demand that complements commercial constellation activity.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of around 40–45% of the global small satellite market, driven by the concentration of commercial small satellite operators such as SpaceX, Amazon, Rocket Lab, Planet Labs, Maxar, L3Harris, Northrop Grumman, and York Space Systems, along with hundreds of smaller firms, the most advanced small satellite manufacturing ecosystem globally, and the largest government and defense satellite procurement market through NASA, the U.S. Space Force, and the National Reconnaissance Office.
Asia-Pacific
Fastest growthHowever, the Asia Pacific small satellite market is expected to grow at the fastest CAGR from 2026 to 2036. This growth is driven by China’s aggressive domestic small satellite constellation buildout, including the government‑backed Guowang 13,000‑satellite constellation and commercial constellations from GalaxySpace, Commsat, and LandSpace, India’s liberalized space policy enabling rapid private‑sector growth following the establishment of IN‑SPACe, Japan’s expanding commercial space program anchored by iQPS and Synspective, and South Korea’s growing national and commercial satellite deployment programs.
Competitive landscape
- Space Exploration Technologies Corp. (U.S.)
- Airbus Defence and Space SAS · France
- Boeing Company (U.S.)
- Lockheed Martin Corporation (U.S.)
- Northrop Grumman Corporation (U.S.)
- Rocket Lab USA, Inc. (U.S.)
- Surrey Satellite Technology Limited (U.K.)
- Thales Alenia Space SAS · France/Italy
- OHB SE · Germany
- L3Harris Technologies, Inc. (U.S.)
- York Space Systems LLC (U.S.)
- China Aerospace Science and Technology Corporation · China
- ICEYE Oy · Finland
- BlackSky Technology Inc.
- Spire Global, Inc.
- GomSpace Group AB
- AAC Clyde Space AB
- Blue Canyon Technologies, Inc.
- Kongsberg NanoAvionics
- LeoStella LLC
Frequently asked questions
The global small satellite market is expected to reach USD 77.00 billion by 2036 from an estimated USD 10.97 billion in 2026, at a CAGR of 21.5% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Small Satellite Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1871). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/small-satellite-market-6554