Ventilators Market (2024-2031)
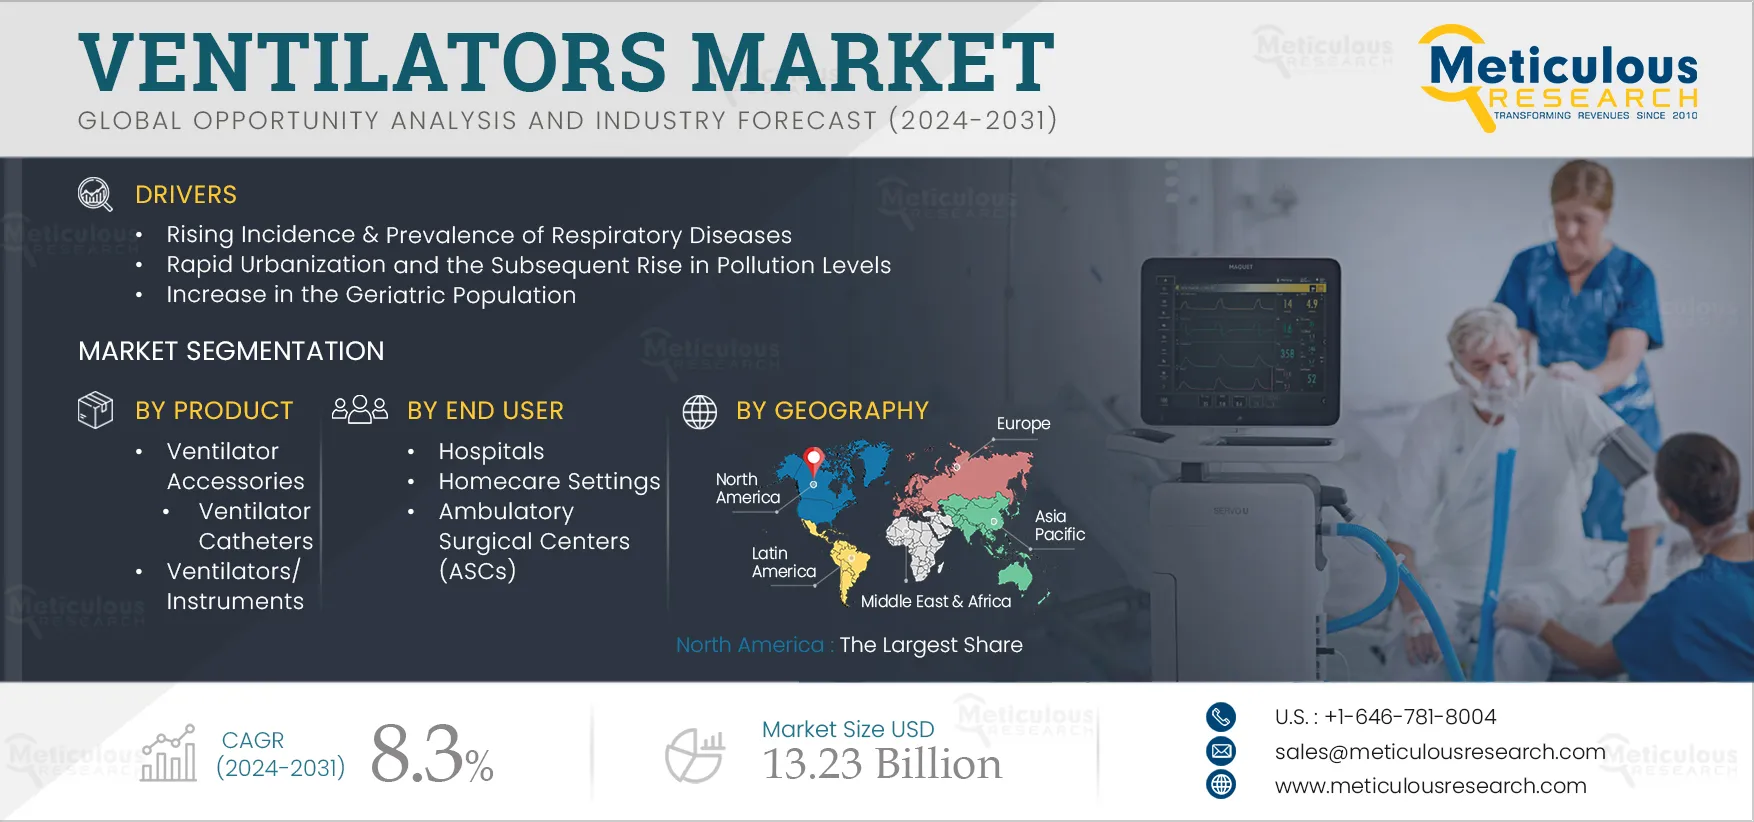
The Ventilators Market was valued at $6.94 billion in 2023. This market is anticipated to reach $13.23 billion by 2031 from an estimated $7.57 billion in 2024, at a CAGR of 8.3% during the forecast period of 2024-2031. Ventilators Market Size & Forecast The growth of the ventilators market is driven
- Published
- Sep 2024
- Pages
- 230
- Format
- PDF + Excel
- Report ID
- MRHC - 104395
- Base year
- 2023
- 2023 · BASELINE
- $6.94B
- 2031
- $13.23B
- CAGR 2024–2031
- 8.3%
2023 baseline · 2024–2031 forecast at 8.3% CAGR · hover a bar for the value
Key highlights
By Product: In 2024, the Ventilator Accessories Segment to Dominate the Ventilators Market
By Mobility: In 2024, the Intensive Care Ventilators Segment to Dominate the Ventilators Market
By Interface: In 2024, the Invasive Ventilators Segment to Dominate the Ventilators Market
By Age Group: The Adult & Pediatric Segment to Dominate the Ventilators Market
By Mode: The Volume Mode Ventilation Segment Dominate the Ventilators Market
By End User: The Hospitals Segment to Dominate the Ventilators Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 230 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 8.3% |
| Market Size (Value) | USD 13.23 Billion by 2031 |
| Segments Covered | By Product · Ventilator Accessories · Ventilator Catheters · Endotracheal Tubes · Ventilator Masks · Other Ventilator Accessories · (Note: Other accessories primarily include interfaces, sensors, nebulizers, oxygen & CO2 measurement devices, circuit sets, and valve sets) · Ventilators/Instruments · By Mobility · Intensive Care Ventilators · Portable Ventilators · By Interface · Invasive Ventilators · Non-invasive Ventilators · By Age Group · Adult & Pediatric · Neonatal & Infant · By Mode · Volume Mode Ventilation · Dual/Combined Mode Ventilation · Pressure Mode Ventilation · Other Ventilation Modes · (Note: Other ventilation modes primarily include Synchronized Intermittent-mandatory Ventilation, Assist-Control Ventilation, Continuous Positive Airway Pressure (CPAP) Mode, Bilevel Positive Airway Pressure (BIPAP), Airway Pressure Release Ventilation, and High-Frequency Oscillatory Ventilation) · By End User · Hospitals · Homecare Settings · Ambulatory Surgical Centers (ASCs) · Other End Users · (Note: Other end users primarily include emergency medical services/transport [ambulance services or paramedic services], nursing care centers, and military centers) |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, Switzerland, Belgium, and Rest of Europe), Asia-Pacific (China, Japan, India, Australia, South Korea, Indonesia, Singapore, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and Middle East & Africa (U.A.E., Saudi Arabia, South Africa, and Rest of Middle East & Africa) |
| Key Companies | Schiller AG (Switzerland), Hamilton Medical AG (Switzerland), Koninklijke Philips N.V. (Netherlands), GE HealthCare Technologies, Inc. (U.S.), Medtronic plc (Ireland), Getinge AB (Sweden), ResMed Inc. (U.S.), Zoll Medical Corporation (U.S.), Drägerwerk AG & Co. KGaA (Germany), Fisher & Paykel Healthcare Limited (New Zealand), and VYAIRE MEDICAL, INC. (U.S.) |
Report overview
Segments covered: product, ventilator accessory, ventilator catheter, endotracheal tube, ventilator mask, other ventilator accessory, ventilators/instrument, mobility, intensive care ventilator, portable ventilator, interface, invasive ventilator, non-invasive ventilator, age group, adult & pediatric, neonatal & infant, mode, volume mode ventilation, dual/combined mode ventilation, pressure mode ventilation, other ventilation mode, end user, hospital, homecare setting, other end user. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the ventilators market is driven by factors such as the increasing number of intensive care units (ICUs) and the corresponding rise in the demand for related equipment & systems, the rising incidence & prevalence of respiratory diseases, rapid urbanization and the consequent rise in pollution levels, the increase in the geriatric population, and the rising incidence of preterm births.
Furthermore, the increasing demand for home care therapeutic devices and the expansion of healthcare infrastructure across emerging economies in Asia-Pacific and Latin America are expected to create market growth opportunities.
Report infographic
Market dynamics
5 factors across 2 forcesIncreasing Number of Intensive Care Units (ICUs) and the Corresponding Rise in the Demand for Related Equipment & Systems
The intensive care unit (ICU) is a specialized facility where critically ill patients receive intensive medical care. The strength of healthcare systems globally is often assessed based on the availability of hospital beds and critical care beds, including those in the ICU. This availability determines the accessibility of healthcare services for the population. Currently, access to healthcare services, particularly intensive care, varies significantly worldwide. The number of ICU beds per 10,000 population differs across regions. For example, in Europe, ICU bed numbers range from 0.42 per 10,000 population in Portugal to 2.92 per 10,000 population in Germany, with an average of 1.15 ICU beds per 10,000 population across Europe. Globally, the U.S. has the highest number of ICU beds, with 3.42 beds per 10,000 population—nearly ten times that of China (0.36) and three times that of Italy (1.25).
Equipment utilized in ICUs ranges from basic tools like blood pressure monitors to highly specialized machinery such as dialysis machines. Key components of critical care infrastructure include ventilators, infusion pumps, IV pole mounts, bedside electronic and manual patient monitoring devices, resuscitation equipment, and various catheters and intubation devices. Therefore, a rise in the overall number of ICU beds subsequently increases demand for associated devices like ventilators.
Urbanization and the Consequent Rise in Pollution Levels
Over the past several decades, the share of the global urban population has significantly increased. This rising urbanization often leads to deforestation for residential and industrial development. The resultant deforestation, combined with higher emissions from various industries and increased vehicle use in urban areas, contributes to numerous environmental issues, including air pollution. As urbanization continues, air pollution levels tend to rise, which adversely affects human health, particularly the respiratory system. Increased exposure to air pollutants is linked to higher incidences of respiratory diseases. For instance, according to the American Lung Association (ALA), in 2022, 11.7 million people, or 4.6% of adults, reported being diagnosed with chronic obstructive pulmonary disease (COPD), chronic bronchitis, or emphysema. Thus, the rising levels of air pollution driven by urbanization have increased the incidence and prevalence of respiratory diseases, thereby driving the demand for ventilators.
Rising Incidence of Preterm Births
According to the WHO, preterm birth is defined as the birth of babies before 37 complete weeks of pregnancy. Over the past several decades, the rates of preterm birth have been rising in many countries. According to the CDC, in 2022, preterm birth affected approximately one in every ten infants born in the U.S. Globally, premature births are the leading cause of death among children under five years old.
Preterm infants are more susceptible to respiratory problems as their lungs are underdeveloped and may not function properly. As a result, preterm babies are at risk for serious complications such as Respiratory Distress Syndrome (RDS), sleep apnea, anemia, bronchopulmonary dysplasia (BPD), persistent pulmonary hypertension of the newborn (PPHN), and pneumonia. Among these, bronchopulmonary dysplasia (BPD) is the most common complication in premature infants and often requires ventilatory support.
The rising incidence of preterm births and associated complications, including respiratory distress syndrome, bronchopulmonary dysplasia, and sleep apnea, is driving the demand for neonatal ventilators worldwide.
Table of contents
14 chapters · 114 sections · 230 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Product | Ventilator Accessories | — |
| By Mobility | Intensive Care Ventilators | — |
| By Interface | Invasive Ventilators | — |
| By Age Group | Adult & Pediatric | — |
| By Mode | Volume Mode Ventilation | — |
| By End User | Hospitals | — |
By Product
- The ventilator accessories segment is anticipated to hold the largest share of 36.8% of the ventilators market in 2024.
- This significant share can be attributed to the rising awareness regarding hospital hygiene practices and the extensive utilization of ventilator accessories such as catheters, masks, endotracheal tubes, sensors, nebulizers, humidifiers, oxygen and CO2 measurement devices, circuit sets, and valve sets.
- The high demand for these accessories has prompted market players to expand their product offerings.
- For instance, in May 2021, Olympus Corporation (Japan) obtained 510(k) clearance for its Airway Mobilescopes, including the MAF-TM2, MAF-GM2, and MAF-DM2 models, designed for a range of upper and lower airway management procedures.
- These flexible mobile scopes feature a video camera at the tip, facilitating enhanced visualization during procedures.
- Anesthesiologists and pulmonologists can utilize these devices to deliver critical and intensive care.
By Mobility
- The intensive care ventilators segment is anticipated to hold the largest share of 76.2% of the ventilators market in 2024.
- This significant share can be attributed to the increasing installation of ventilators in ICUs, the availability of reimbursements for ventilation solutions and respiratory treatment procedures, a surge in patient admissions in CCUs driven by the rising prevalence of chronic & respiratory infectious diseases, and the rising incidence of preterm births worldwide.
By Interface
- The invasive ventilators segment is anticipated to hold the largest share of the ventilators market in 2024.
- This significant share can be attributed to the extensive use of invasive ventilators in ICUs for patients with neurological disorders, chronic respiratory and infectious diseases, and sleep disorders.
By Age Group
- The adult & pediatric segment is anticipated to hold the largest share of the ventilators market in 2024.
- This significant share can be attributed to the increased adoption of ventilation support among the elderly population, their increased vulnerability to chronic and infectious diseases such as COPD and lung infections, and the increased tobacco use among this demographic.
- Furthermore, the high rates of hospital admissions further drive the need for critical care equipment, such as ventilators.
- For instance, according to the American Hospital Association (AHA), in 2022, a total of 33,679,935 admissions were recorded across all U.S. hospitals.
- Similarly, National Health Service (NHS) England recorded approximately 237,951 adult critical care admissions in 2022.
- These high admission rates necessitate the utilization of critical care equipment like ventilators, thereby contributing to the market’s growth.
By Mode
- The volume mode ventilation segment is anticipated to hold the largest share of the ventilators market in 2024.
- This significant share can be attributed to the widespread adoption of volume-controlled ventilators in intensive care units due to their advantages, including precise minute ventilation and consistent tidal volume delivery.
- Volume Controlled Ventilation (VCV) has traditionally been the standard mode of controlled ventilation in anesthesia.
- Some of the companies that provide volume mode ventilators are GE HealthCare Technologies, Inc. (U.S.), Hamilton Company (U.S.), Medtronic plc (Ireland), and Drägerwerk AG & Co. KGaA (Germany).
By End User
- The Hospitals Segment to Dominate the Ventilators Market
- The hospitals segment is anticipated to hold the largest share of the ventilators market in 2024.
- This significant share can be attributed to the considerable number of patients afflicted with respiratory illnesses, the presence of skilled medical practitioners in hospitals, and the accessibility to advanced healthcare facilities equipped with state-of-the-art medical devices.
Geographic analysis
North America
Largest shareIn 2024, North America is anticipated to hold the largest share of 55.7% of the ventilators market. North America’s large market share is attributed to the region's robust healthcare infrastructure, the increasing incidence of chronic and infectious diseases, the presence of leading market players, and the widespread adoption of cutting-edge medical technologies. By Geography: North America to Dominate the Ventilators Market
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is anticipated to record the highest CAGR of 18.7% during the forecast period. This growth is driven by the increasing prevalence of respiratory diseases, growing investments in the healthcare sector, and ongoing innovations in ventilation technology. For instance, in November 2023, China’s National Health Commission reported a rise in respiratory diseases, particularly among children. Additionally, in November 2021, Shenzhen Comen Medical Instruments Co., Ltd. (China) introduced the Comen V1 transport ventilator at the Medica Trade Fair in Germany. This ventilator is easy to use, compact in design, and portable, making it suitable for use outside hospital settings.
Competitive landscape
- November 2023
Inspiration Healthcare Group plc. (U.K.) launched SLE1500, which is a compact respiratory system that provides non-invasive ventilation to neonatal patients.
- June 2023
Noccarc Robotics Private Limited (India) launched the Noccarc V730i Smart ICU Ventilator, which has cloud access to software upgrades to integrate with hardware modules. This device also enables real-time remote patient monitoring.
- January 2023
Getinge AB (Sweden) launched the Servo-c mechanical ventilator to address personalized patient respiratory needs using various functionalities in the device.
- Schiller AG · Switzerland
- Hamilton Medical AG · Switzerland
- Koninklijke Philips N.V. · Netherlands
- GE HealthCare Technologies, Inc. (U.S.)
- Medtronic plc · Ireland
- Getinge AB · Sweden
- ResMed Inc. (U.S.)
- Zoll Medical Corporation (U.S.)
- Drägerwerk AG & Co. KGaA · Germany
- Fisher & Paykel Healthcare Limited · New Zealand
- VYAIRE MEDICAL, INC. (U.S.)
Frequently asked questions
This market study covers the market sizes & forecasts of the ventilators based on product, mobility, interface, age group, mode, end user, and geography. It also provides the value analysis of various segments and sub-segments of the global ventilators market at country levels.
Cite this report
Meticulous Research. (2024). Ventilators Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRHC - 104395). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ventilators-market-5093