Synthetic Rubber Market (2025-2032)
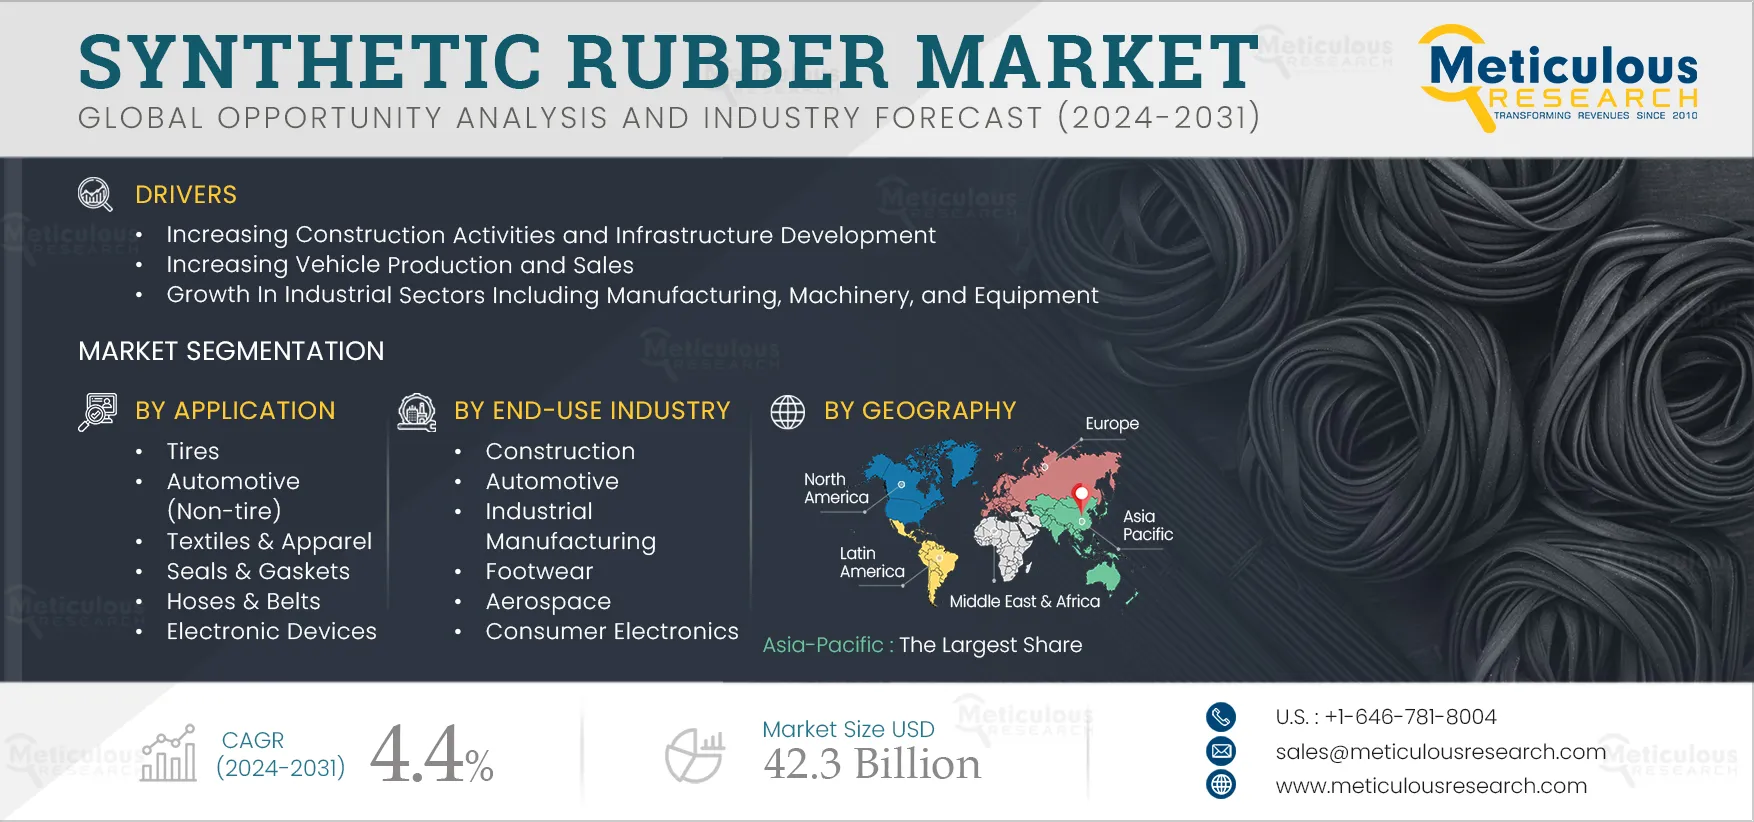
The Synthetic Rubber Market is expected to reach $42.3 billion by 2032, at a CAGR of 4.4% from 2025 to 2032.The growth of this market is driven by increasing construction activities and infrastructure development, increasing vehicle production and sales, and growth in industrial sectors, including manufacturing, machinery, and equipment.
- Published
- May 2024
- Pages
- 180
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041165
- Base year
- 2024
- 2032 · FORECAST
- $42.30B
- 2032
- $42.30B
- CAGR 2025–2032
- 4.4%
2024 baseline · 2025–2032 forecast at 4.4% CAGR · hover a bar for the value
Key highlights
By Type: In 2025, The Styrene butadiene rubber (SBR) Segment to Dominate the Synthetic Rubber Market
By Application: In 2025, The Tires Segment to Dominate the Synthetic Rubber Market
By End-use Industry: In 2025, The Automotive Segment to Dominate the Synthetic Rubber Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 180 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 4.4% |
| Market Size (Value) | USD 42.3 Billion by 2032 |
| Segments Covered | By Type · Styrene Butadiene Rubber (SBR) · Polybutadiene Rubber (BR) · Styrene Block Copolymer (SBC) · Ethylene Propylene Diene Rubber (EPDM) · Butyl Rubber (IIR) · Acrylonitrile-butadiene Rubber (NBR) · Isoprene Rubber (IR) · Chloroprene Rubber (CR) · Other Types · By Application · Tires · Automotive (Non-tire) · Footwear Components · Textiles & Apparel · Seals & Gaskets · Hoses & Belts · Electronic Devices · Lubrications · Packaging · Other Applications · By End-use Industry · Construction · Automotive · Industrial Manufacturing · Footwear · Aerospace · Consumer Electronics · Other End-use Industries |
| Countries Covered | Europe (Germany, U.K., Italy, France, Spain, Russia, Netherlands, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Thailand, Singapore, and Rest of Asia-Pacific), North America (U.S., Canada), Latin America (Brazil, Argentina, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Saudi Arabia, South Africa, and Rest of the Middle East & Africa) |
| Key Companies | China Petrochemical Corporation (a subsidiary of Sinopec Corp.) (China), ERIKS N.V.(Netherlands), The Dow Chemical Company (U.S), Exxon Mobil Corporation (U.S.), Kumho Petrochemical Co., Ltd. (KKPC) (South Korea), Zeon Corporation (Japan), Nizhnekamskneftekhim (NKNK) (Russian), Mitsui Chemicals, Inc. (Japan), JSR Corporation (Japan), SABIC (Saudi Arabia), Denka Company Limited (Japan), Asahi Kasei Corporation (Japan), Indian Synthetic Rubber Private Limited (India), Apcotex (India), Reliance Industries Limited (India), Trinseo PLC (U.S.), TSRC Corporation (Taiwan), Michelin Group (France), and LANXESS (Germany). |
Report overview
Segments covered: type, application, industry. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
Additionally, the growing demand for eco-friendly synthetic rubber alternatives is expected to create market growth opportunities. However, issues related to waste disposal, pollution, and carbon emissions may restrain the growth of this market. However, stringent environmental regulations, quality standards, and compliance policies by governments pose a major challenge for the players operating in this market.
Additionally, the increasing demand for high-performance synthetic rubber materials is a key market trend.
Report infographic
Market dynamics
4 factors across 3 forcesIncreasing Vehicle Production and Sales
The automotive sector is a major consumer of synthetic rubber, with tires alone representing a substantial portion of the market. Synthetic rubber plays a pivotal role in vehicle manufacturing. It is used to manufacture various automotive components such as seals, gaskets, hoses, belts, and vibration isolators and is primarily used in tire production. According to the World Economic Forum (Switzerland), the global sales of electric cars will increase by 60.0% in 2022, exceeding 10 million for the first time, as per the Net Zero Emissions (NZE) by 2050 scenario. In 2032, electric car fleets are expected to account for nearly 60.0% of new car sales, with a volume of 300 million units. As a result, the rise of electric vehicles is a key driver in increasing vehicle production and sales, thereby supporting the demand for synthetic rubber in the coming years.
Growth in Industrial Sectors, Including Manufacturing, Machinery, and Equipment
Synthetic rubber plays a crucial role in various industrial sectors for a wide range of applications due to its favorable properties such as durability, resilience, and chemical resistance. It is used in the production of hoses, belts, seals, gaskets, O-rings, and vibration-dampening components. Also, it is used for components such as bushings, seals, gaskets, and conveyor belts to ensure optimal performance and longevity. According to the National Institute of Standards and Technology (NIST)(U.S.), in 2022, the U.S. manufacturing contributed more than $2.3 trillion to the U.S. GDP amounting to 11.4 % of total U.S. GDP, measured in chained 2012 dollars. According to the India Brand Equity Foundation (India) report 2025, manufacturing exports have registered the highest annual exports of $447.46 billion with 6.03% growth during 2024 surpassing the previous year (2022) record exports of $422 billion. This growth underscores the importance of synthetic rubber in supporting industrial activities and meeting the demand for various rubber components in manufacturing processes and equipment. All such factors, along with increasing demand for manufactured goods, Industry 4.0, and infrastructure development are supporting the demand for synthetic rubber during the forecast period.
Table of contents
11 chapters · 125 sections · 180 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Styrene butadiene rubber (SBR) | Ethylene propylene diene rubber (EPDM) |
| By Application | Tires | Electronic devices |
| By End-use Industry | Automotive | Consumer electronics |
By Type
- The styrene butadiene rubber (SBR) segment is expected to account for the largest share of above 29.0% of the synthetic rubber market.
- The large market share of this segment is attributed to the increasing demand for tires, the growing use of SBR in tire manufacturing due to its high abrasion resistance and good aging properties, and the growing shift toward green tire technologies that incorporate higher proportions of bio-based and recycled materials including SBR.
- However, the ethylene propylene diene rubber (EPDM) segment is projected to record the highest CAGR during the forecast period of 2025–2032.
- This growth is driven by the increasing use of EPDM in construction applications, automotive seals, gaskets, weatherstripping, and hoses due to its high weather resistance and durability; growing focus on renewable energy sources as EPDM is used in seals & gaskets for renewable energy technologies.
By Application
- The Tires Segment to Dominate the Synthetic Rubber Market
- The tires segment is expected to account for the largest share of above 72.0% of the synthetic rubber market.
- The large market share of this segment is attributed to the expansion of the automotive industry, driven by increasing vehicle production and sales globally, increasing vehicle maintenance, rising demand for tires, and growing need for tire replacement due to wear and tear.
- However, the electronic devices segment is projected to witness the highest growth rate during the forecast period of 2025–2032.
- This growth is driven by the growth of the consumer electronics market, the growing popularity of wearable devices such as smartwatches, fitness trackers, and earbuds, the expansion of telecommunication infrastructure, including the deployment of 5G networks and increased connectivity, and the increasing use of synthetic rubber in various electronic components such as keypads, gaskets, vibration dampening materials, and seals.
By End-use Industry
- The Automotive Segment to Dominate the Synthetic Rubber Market
- The automotive segment is expected to account for the largest share of above 76.0% of the synthetic rubber market.
- The large market share of this segment can be attributed to the growth of the automotive industry, the growing use of synthetic rubber in automotive applications such as tires, seals, gaskets, automotive interiors, exteriors, and chassis systems, and increasing demand for high-performance synthetic rubber materials with enhanced properties.
- However, the consumer electronics segment is projected to record the highest CAGR during the forecast period of 2025–2032.
- This growth is driven by the continuous technological advancement in the consumer electronics industry, the growing popularity of wearable devices, the expansion of telecommunication infrastructure, the growing demand for water- and dust-resistant devices, and the proliferation of IoT devices, including smart home appliances, connected wearables, and industrial sensors.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of above 54.0% of the synthetic rubber market, followed by Europe, North America, Latin America, and the Middle East & Africa. Asia-Pacific's significant market share can be attributed to several key factors, including the increasing demand for synthetic rubber in various industries, including automotive, construction, manufacturing, and consumer goods, increasing urbanization and infrastructure development, increasing government initiatives and policies promoting industrial growth, and growing automotive and consumer electronics industry in countries including China, Japan, South Korea, and India. The region is also slated to register the highest growth rate of above 6.0% during the forecast period.
Competitive landscape
- January 2025
Michelin Group (France), IFP Energies nouvelles (IFPEN) (France), and Axens (France) unveiled an industrial-scale demonstrator for producing bio-based butadiene, a key ingredient in synthetic rubber production. The demonstrator was built within the framework of the BioButterfly project, which aims to develop and commercialize butadiene from ethanol derived from biomass (plants) to replace butadiene from petrochemicals.
- May 2024
ARLANXEO (Netherlands) announced to build of a rubber production plant in Jubail, Saudi Arabia, with an annual capacity of 140,000 metric tons. This plant will be part of the USD 11 billion Amiral complex planned by Saudi Aramco and Total Energies to produce two elastomers, including ultra-high cis polybutadiene (NdBR) and lithium butadiene rubber (LiBR).
- May 2024
Hankook Tire & Technology Co., Ltd. (South Korea) and Kumho Petrochemical Co., Ltd. (South Korea) entered into a memorandum of understanding (MoU) to collaborate on advancing environmentally friendly tires by utilizing eco-solution-polymerized styrene-butadiene rubber (eco-SSBR). Under this agreement, Hankook Tire will secure synthetic rubber certified by the International Sustainability & Carbon Certification (ISCC) PLUS – an international certification system for environmentally friendly materials.
- April 2024
Hainan Baling Chemical New Material Co., Ltd. China (a subsidiary of Sinopec Corp. (China)) launched its latest project focused on the production of Styrene-Butadiene Copolymer (SBC) in Hainan, China. The annual production capacity of 170,000 tons will make Sinopec the world's largest producer of SBC plants.
- ERIKS N.V. · Netherlands
- Dow Chemical Company (U.S)
- Exxon Mobil Corporation (U.S.)
- Kumho Petrochemical Co., Ltd. (KKPC) · South Korea
- Zeon Corporation · Japan
- Nizhnekamskneftekhim (NKNK) · Russian
- Mitsui Chemicals, Inc. · Japan
- JSR Corporation · Japan
- SABIC · Saudi Arabia
- Denka Company Limited · Japan
- Asahi Kasei Corporation · Japan
- Indian Synthetic Rubber Private Limited · India
- Apcotex · India
- Reliance Industries Limited · India
- Trinseo PLC (U.S.)
- TSRC Corporation · Taiwan
- Michelin Group · France
- LANXESS · Germany
Frequently asked questions
The Synthetic Rubber Market refers to the global industry that produces and sells rubber materials manufactured through chemical processes, often derived from petroleum byproducts. These rubber materials are used in various industries like automotive, construction, electronics, and industrial manufacturing due to their properties such as elasticity, durability, and resistance to heat, chemicals, and wear.
Cite this report
Meticulous Research. (2024). Synthetic Rubber Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRCHM - 1041165). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/synthetic-rubber-market-5848