Carbon Steel Market (2025-2032)
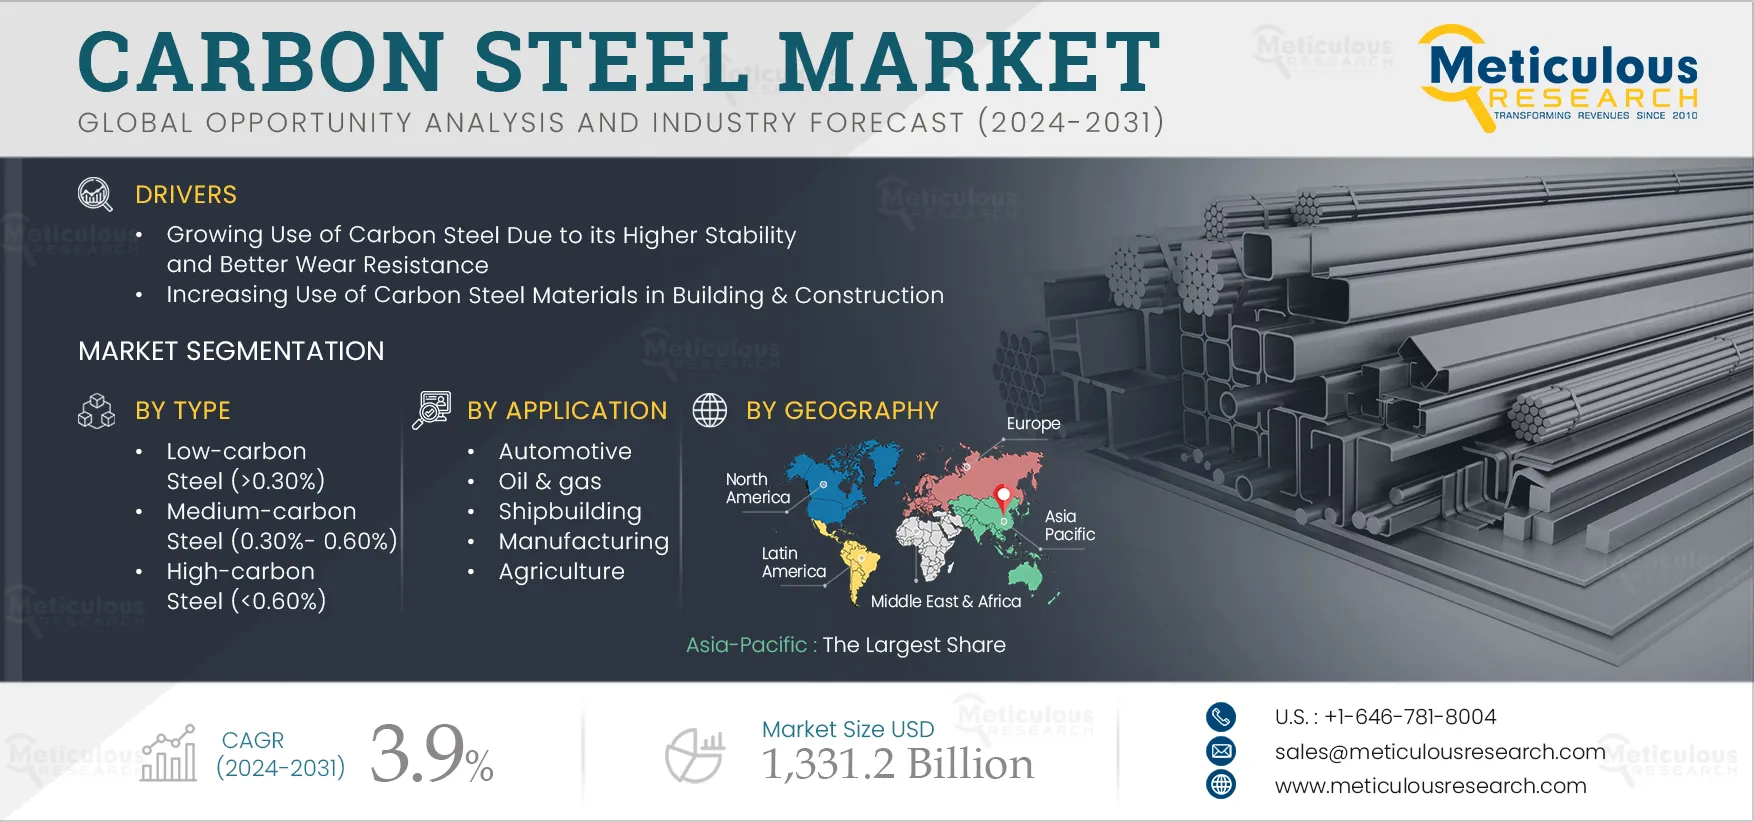
The Carbon Steel Market is expected to reach $1,331.2 billion by 2032, at a CAGR of 3.9% from 2025 to 2032.
- Published
- Sep 2024
- Pages
- 220
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041286
- Base year
- 2024
- 2032 · FORECAST
- $1.33T
- 2032
- $1.33T
- CAGR 2025–2032
- 3.9%
2024 baseline · 2025–2032 forecast at 3.9% CAGR · hover a bar for the value
Key highlights
By Type: In 2025, the Low-Carbon Steel (>0.30%) Segment to Dominate the Carbon Steel Market
By Process: In 2025, the Basic Oxygen Process (BOP) Segment to Dominate the Carbon Steel Market
By Product: In 2025, the Flat Carbon Steel Segment to Dominate the Carbon Steel Market
By Application: In 2025, the Building & Construction Segment to Dominate the Carbon Steel Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 220 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 3.9% |
| Market Size (Value) | USD 1331.2 Billion by 2032 |
| Segments Covered | By Type · Low-carbon Steel (>0.30%) · Medium-carbon Steel (0.30%- 0.60%) · High-carbon Steel (<0.60%) · By Process · Basic Oxygen Process (BOP) · Electric Arc Furnace Process (EAF) · By Product · Flat Carbon Steel · Long Carbon Steel · Tubular Carbon Steel · By Application · Building & Construction · Automotive · Oil & gas. · Shipbuilding · Locomotive & Transportation · Manufacturing · Consumer Electronics · Aerospace & Defense · Agriculture · Other Applications |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Netherlands, Spain, Sweden, and Rest of Europe), Asia-Pacific (China, India, Japan, South Korea, Singapore, Australia & New Zealand, Indonesia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (Saudi Arabia, UAE, Israel, and Rest of the Middle East & Africa) |
| Key Companies | Tata Steel Limited (India), JFE Steel Corporation (A Subsidiary of JFE Holdings, Inc.) (Japan), JSW STEEL LIMITED (India), POSCO HOLDINGS INC. (South Korea), United States Steel Corporation (U.S.), Jiangsu Shagang Group Company Limited (China), Ansteel Group Corporation Limited (China), Nippon Steel Corporation (Japan), HBIS Group Co., Ltd. (China), Kobe Steel, Ltd. (Japan), NACHI-FUJIKOSHI CORP (Japan), Hudson Tool Steel Corporation (U.S.), AK Steel International B.V. (A Subsidiary of Cleveland-Cliffs Inc.) (Netherlands), Sandvik AB (Sweden), and Daido Steel Co., Ltd. (Japan). |
Report overview
Segments covered: type, process, product, application. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The market for carbon steel is expanding because of the increased use of this high-wear-resistant and stable material and the rising use of carbon steel-based building and construction materials. Furthermore, the surging demand for carbon steel in the oil and gas industry for pipelines and storage tanks is expected to generate growth opportunities for the players operating in this market.
Report infographic
Market dynamics
3 factors across 3 forcesIncreasing use of Carbon Steel Materials in Building & Construction
Carbon steel has grown in popularity in the building & construction industry due to its physical and mechanical features, which provide several advantages to modern construction, such as strength, durability, and cost-effectiveness. Carbon steel is widely used for the structural framework of bridges, high-rise buildings, and major industrial complexes. Carbon steel can effectively support buildings and ensure structural safety, through precise engineering and processing.
Additionally, carbon steel is durable and resistant to corrosion & oxidation. There is an increase in the utilization of carbon steel to maintain the integrity of the structure and its performance. Due to its resilience, carbon steel is ideal for outdoor construction and infrastructure projects such as highways, railroads, and oil pipelines. As a result, numerous businesses are releasing carbon steel goods due to the growing use of carbon steel materials in the building & construction industry. For instance, in March 2025, Clarkwestern Dietrich Building Systems LLC (U.S.) launched a new line of low embodied carbon steel framing products, allowing architects and engineers greater freedom in designing sustainable buildings. The LEC portfolio includes ProSTUD metal drywall framing systems, structural steel, clips and connectors, floor framing, and more.
Table of contents
12 chapters · 116 sections · 220 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Low-Carbon Steel (>0.30%) | High-carbon steel (<0.60%) |
| By Process | Basic Oxygen Process (BOP) | — |
| By Product | Flat Carbon Steel | Tubular carbon steel |
| By Application | Building & Construction | Manufacturing |
By Type
- The Low-Carbon Steel (>0.30%) Segment to Dominate the Carbon Steel Market
- The low-high carbon steel (>0.30%) segment is expected to account for the largest share of 81% of the global carbon steel market.
- This segment's large market share is attributed to the rising use of low-carbon steel for applications that require shaping, bending, and welding; low-carbon steel has good ductility, which allows it to be formed into diverse shapes without sacrificing strength.
- Additionally, the increasing usage of low-carbon steel minimizes the likelihood of cracking or breaking.
- However, the high-carbon steel (<0.60%) segment is expected to register the highest CAGR during the forecast period.
- This segment’s growth is attributed to the increasing adoption of high-carbon steel in mining, construction, and manufacturing due to its strength, hardness, and wear resistance, as well as the increasing utilization of high-carbon steels for heat treatment, which allows manufacturers to tailor their mechanical properties to specific application needs.
By Process
- The basic oxygen process (BOP) segment is expected to account for the largest share of over 62% of the global carbon steel market.
- This segment's large market share is attributed to the increased use of BOP to generate large quantities of carbon steel in less time than other processes; the BOP is increasingly being utilized to produce a wide range of carbon steels, from low to high-carbon content.
- Additionally, the BOP facilities are highly automated, lowering the chance of accidents and boosting overall worker safety.
- However, the electric arc furnace process (EAF) segment is expected to register a higher CAGR during the forecast period.
- This segment's growth is attributed to the growing need for lower emissions of greenhouse gases and other pollutants during the carbon steel process, as well as the increasing adoption of the EAF process, which requires less initial capital investment than establishing a traditional integrated steel plant.
- Furthermore, the EAF process requires less energy per ton of carbon steel produced.
By Product
- The flat carbon steel segment is expected to account for the largest share of 48% of the global carbon steel market.
- This segment's large market share is attributed to the growing adoption of flat carbon steel due to its high strength & durability and the increasing use of flat carbon steel to fabricate, weld, and mold into various shapes and sizes.
- The growing demand for flat carbon steel in construction and manufacturing for structural applications such as support beams, braces, and framing.
- However, the tubular carbon steel segment is expected to register the highest CAGR during the forecast period.
- This segment’s growth is attributed to the increasing use of tubular carbon for conveying fluids, gases, and solids in industries such as oil & gas, construction, automotive, and manufacturing.
- The growing use of tubular carbon steel is due to its high resistance to rust, corrosion, and extreme temperatures.
By Application
- The building & construction segment is expected to account for the largest share of 43% of the global carbon steel market.
- This segment's large market share is attributed to the increasing usage of carbon steel for structural components and load-bearing elements in construction as well as the expanding use of carbon steel components due to its low weight and ease of handling & installation than concrete or other materials.
- Carbon steel is also sturdy and fatigue-resistant, making it ideal for long-term use in construction projects.
- However, the manufacturing segment is expected to register the highest CAGR during the forecast period.
- This segment's growth is attributed to the increasing use of carbon steel in manufacturing due to its strength and resistance to mechanical loads and the expanding adoption of carbon steel for ease of cutting, machining, welding, and forming.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of 64% of the global carbon steel market. Asia-Pacific’s significant market share can be attributed to the increasing growth of the automotive and shipbuilding industries and the growing adoption of carbon steel products due to rising environmental concerns & regulations for sustainable alternatives. The rapid urbanization in countries like China, India, and Southeast Asia for carbon steel for buildings, bridges, and urban infrastructure. Moreover, the Asia-Pacific is expected to register the highest CAGR of 5% during the forecast period. In 2025, Asia-Pacific Region to Dominate the Carbon Steel Market
Competitive landscape
- June 2025
Rio Tinto Group (U.K.) announced an investment of USD 143 million (AUD 215 million) in a research and development facility in Western Australia to evaluate the effectiveness of BioIron, a low-carbon ironmaking process that supports decarbonization of the global steel value chain.
- November 2024
ArcelorMittal S.A. (Luxembourg) partnered with Schneider Electric SE (France) to supply Schneider Electric with XCarb recycled and renewable steel for its electrical cabinets and enclosures. XCarbrecycled and renewably generated steel is manufactured at ArcelorMittal’s site in Sestao, Spain, employing a high amount of recycled steel in an electric arc furnace driven entirely by renewable electricity. This results in CO emissions that are 70% lower than the same product made without XCarb recycled and sustainably produced steel.
- Tata Steel Limited · India
- JSW STEEL LIMITED · India
- POSCO HOLDINGS INC. · South Korea
- United States Steel Corporation (U.S.)
- Jiangsu Shagang Group Company Limited · China
- Ansteel Group Corporation Limited · China
- Nippon Steel Corporation · Japan
- HBIS Group Co., Ltd. · China
- Kobe Steel, Ltd. · Japan
- NACHI-FUJIKOSHI CORP · Japan
- Hudson Tool Steel Corporation (U.S.)
- Sandvik AB · Sweden
- Daido Steel Co., Ltd. · Japan
Frequently asked questions
The carbon steel market study focuses on the market assessment and opportunity analysis through the sales of carbon steel across different regions, and countries across different market segmentations. This study is also focused on competitive analysis for carbon steel based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). Carbon Steel Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRCHM - 1041286). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/carbon-steel-market-5969