Secure Access Service Edge (SASE) Market (2026-2036)
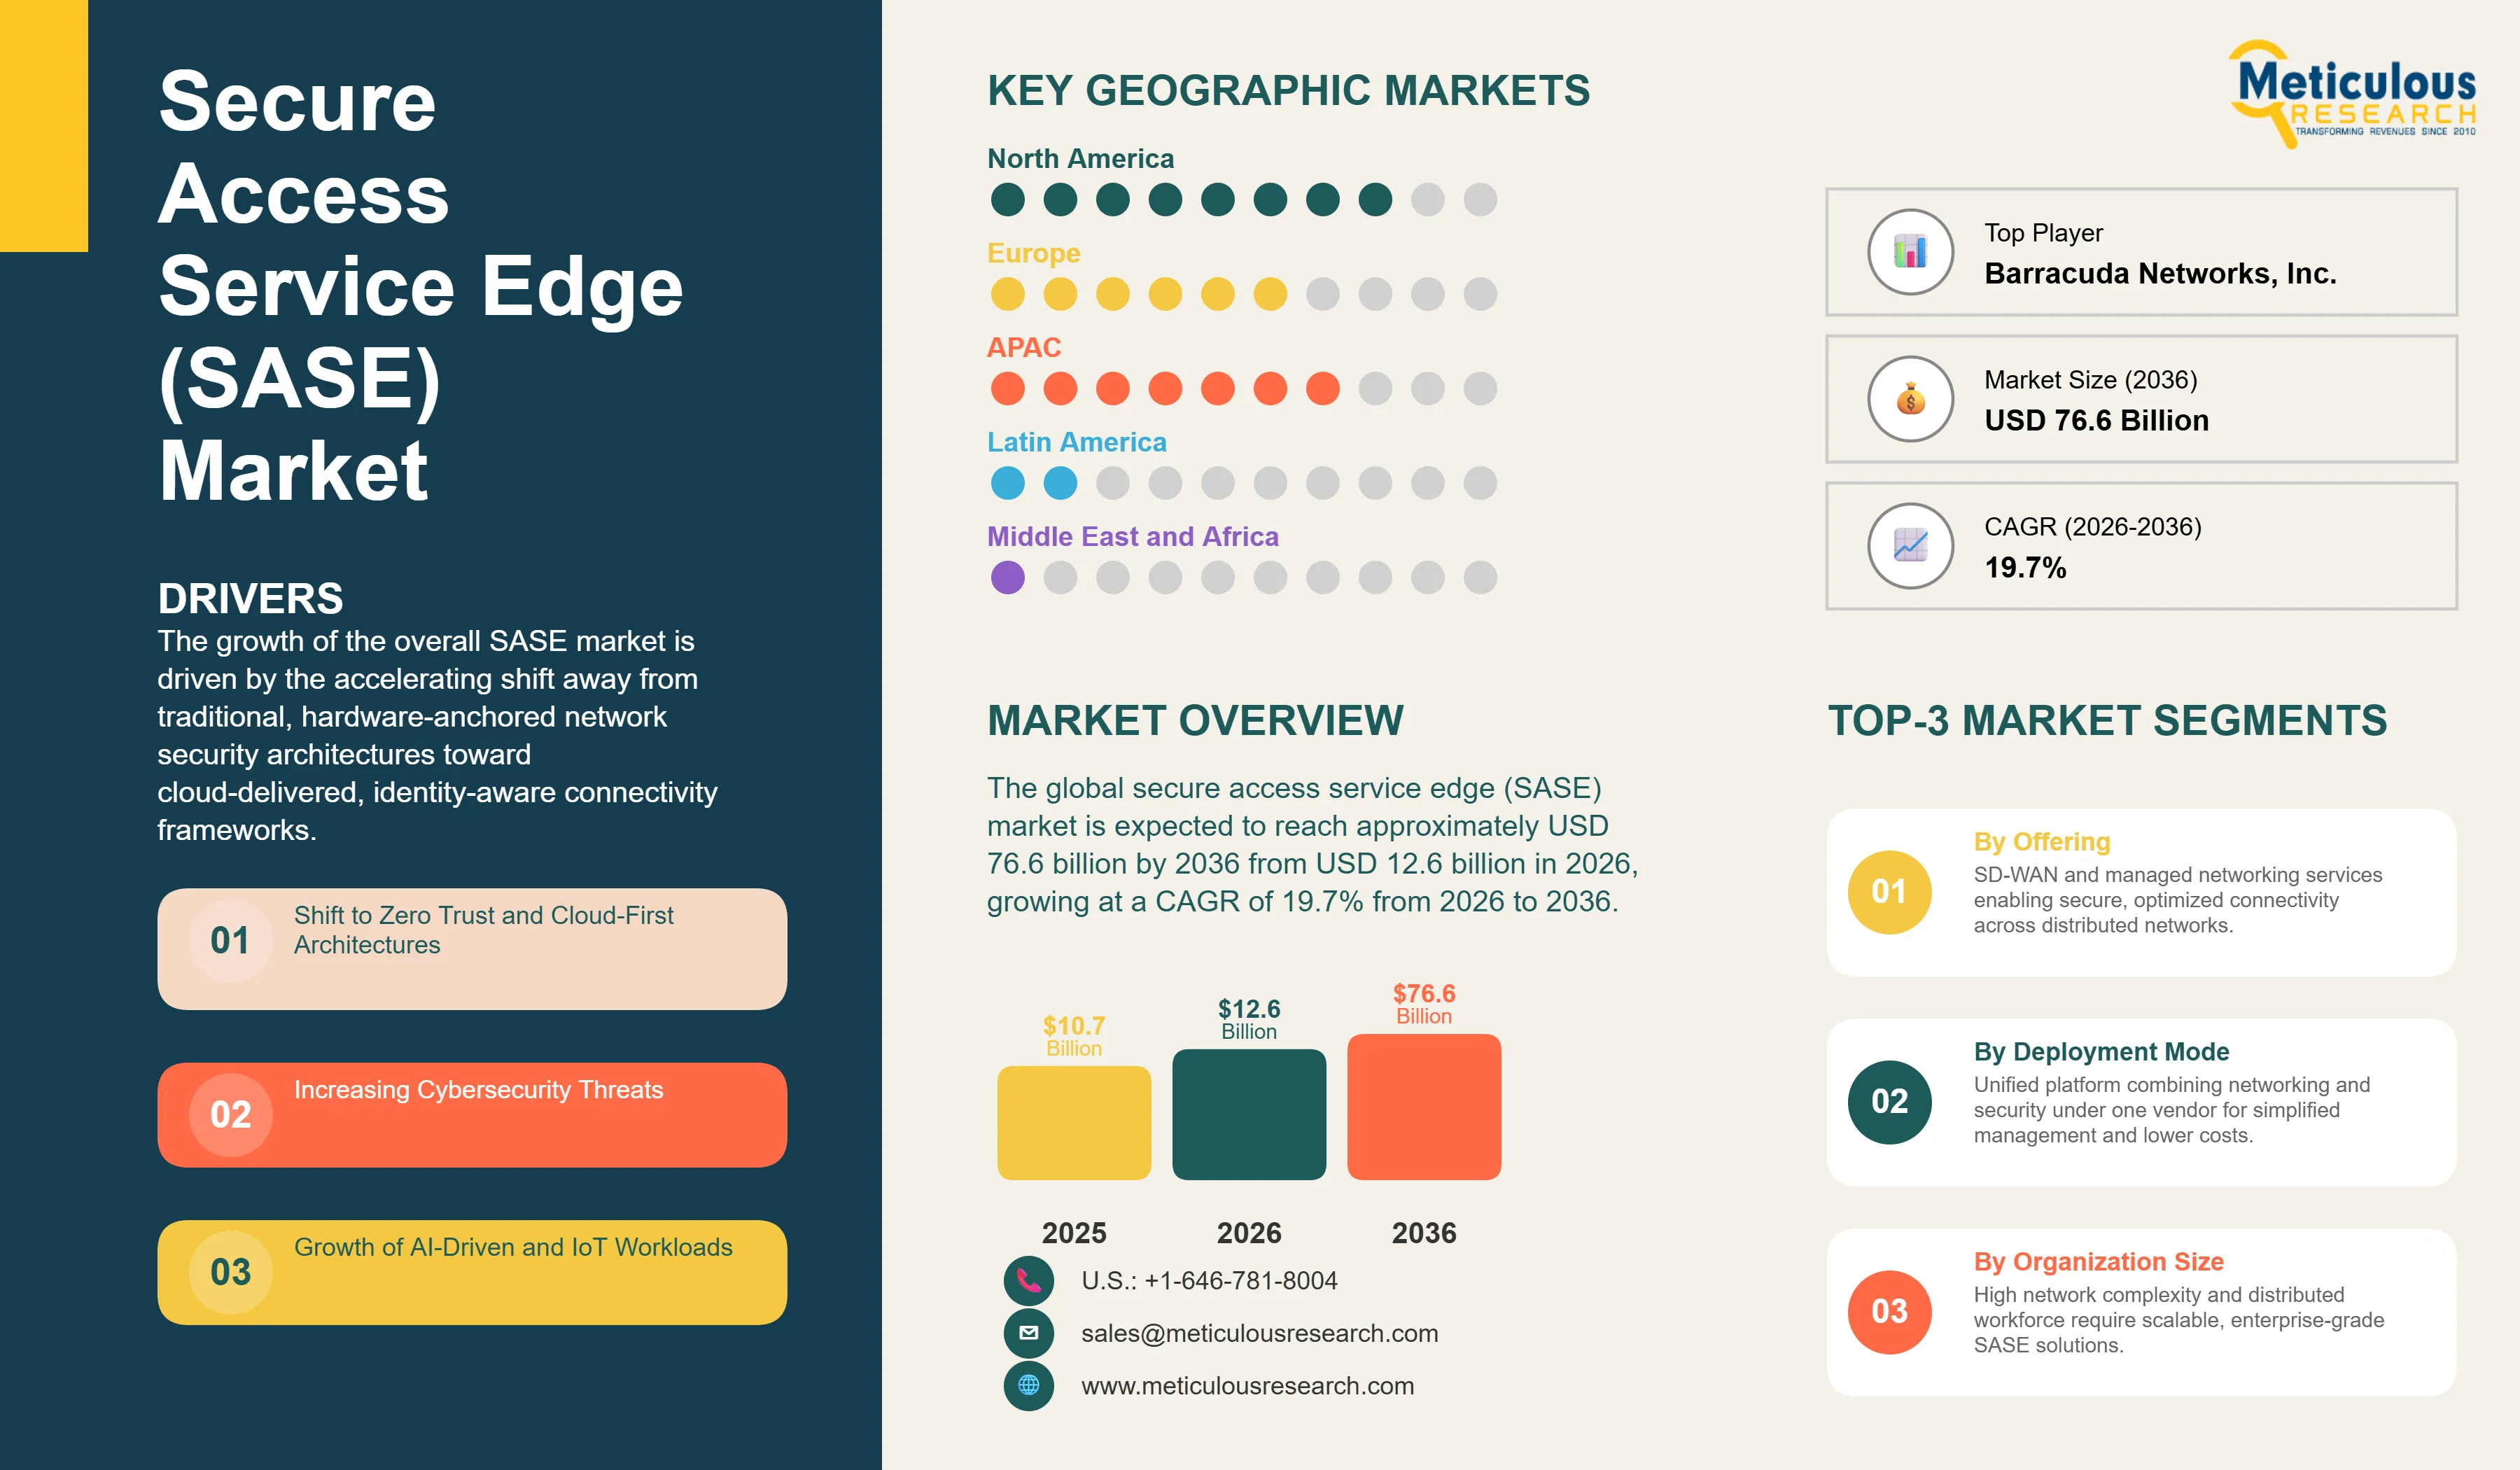
The global secure access service edge (SASE) market was valued at USD 10.7 billion in 2025. The market is expected to reach approximately USD 76.6 billion by 2036 from USD 12.6 billion in 2026, growing at a CAGR of 19.7% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 307
- Format
- PDF + Excel
- Report ID
- MR-1805
- Base year
- 2025
- 2025 · BASELINE
- $10.70B
- 2036
- $76.60B
- CAGR 2026–2036
- 19.7%
2025 baseline · 2026–2036 forecast at 19.7% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global SASE market is projected to reach USD 76.6 billion by 2036.
The market is expected to grow at a CAGR of 19.7% from 2026 to 2036.
North America dominates the global SASE market with the largest market share in 2026, supported by the concentration of leading solution providers, early enterprise adoption of zero trust frameworks, and strong federal mandates driving cloud security transformation in the region.
Asia-Pacific is expected to witness the fastest growth during the forecast period, fueled by rapid cloud migration across industries, expanding digital infrastructure investment, and growing cybersecurity awareness among enterprises in China, India, Japan, and Southeast Asia.
By offering, the Security Service Edge (SSE) segment holds the largest market share in 2026, reflecting the strong enterprise demand for integrated cloud security capabilities including zero trust network access, cloud access security broker, and secure web gateway functionalities.
By deployment mode, the single-vendor SASE segment holds the largest market share in 2026, driven by enterprise preference for consolidated management, reduced integration complexity, and lower total cost of ownership.
By end-use vertical, the BFSI segment holds the largest share of the overall market in 2026, given the sector's stringent regulatory requirements and the high sensitivity of financial data requiring continuous, policy-driven access control.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 76.6 Billion |
| Market Size in 2026 | USD 12.6 Billion |
| Market Size in 2025 | USD 10.7 Billion |
| Market Growth Rate (2026–2036) | CAGR of 19.7% |
| Format | PDF, Excel & Cloud Portal · 307 pages |
| Dominating Region | North America |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Offering, Deployment Mode, Organization Size, End-use Vertical, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: offering, deployment mode, organization size, end-use vertical.
The growth of the overall SASE market is driven by the accelerating shift away from traditional, hardware-anchored network security architectures toward cloud-delivered, identity-aware connectivity frameworks. As organizations navigate increasingly distributed workforces, multi-cloud environments, and a rapidly expanding threat landscape, SASE has emerged as the preferred architecture for converging wide-area networking and security functions into a single, unified platform. The sustained rise in ransomware attacks, data breach incidents, and strict data sovereignty regulations is further compelling enterprises across all industries to transition away from legacy virtual private network and perimeter-based security models. At the same time, the rapid expansion of artificial intelligence (AI)-driven operations and IoT-connected edge devices is reinforcing the need for continuous, context-aware security enforcement across every user, device, and application -- a capability that SASE platforms are uniquely positioned to deliver.
Secure access service edge is a cloud-delivered architecture that converges wide-area network connectivity and comprehensive security functions into a single, centrally managed service. These platforms integrate core capabilities such as software-defined wide-area networking (SD-WAN), zero trust network access (ZTNA), cloud access security broker (CASB), secure web gateway (SWG), and firewall-as-a-service (FWaaS) into a unified policy engine that governs user and device access based on identity, location, device posture, and real-time risk context -- regardless of where users, applications, or data reside. The market is defined by a decisive shift from hardware-centric, perimeter-based security models toward cloud-native platforms capable of delivering consistent security and optimal connectivity across branch offices, remote workers, and multi-cloud environments simultaneously.
The market encompasses a diverse range of solution architectures, from lightweight security service edge platforms serving cloud-first enterprises to fully converged single-vendor SASE offerings that replace entire legacy networking and security stacks. These platforms are increasingly embedded with AI and machine learning capabilities that automate threat detection, dynamically adjust access policies, and provide proactive digital experience management across distributed environments. The ability to deliver sub-millisecond threat inspection, granular data loss prevention, and continuous compliance monitoring from a single cloud-delivered platform has made SASE technology the architecture of choice for organizations that require both operational agility and enterprise-grade security resilience.
The global enterprise security environment is undergoing fundamental transformation, driven by the intersection of cloud-first application strategies, hybrid work permanence, and escalating cyber threat sophistication. This transformation has dramatically accelerated the retirement of traditional VPN infrastructure and campus-based firewalls, with organizations prioritizing unified SASE platforms that can enforce least-privilege access, automate incident response, and maintain regulatory compliance across geographically dispersed operations. The rapid growth in cloud-native application development, edge computing deployments, and AI workloads is further reinforcing SASE as the foundational security architecture for the modern digital enterprise.
Report infographic
Market dynamics
4 factors across 3 forcesAccelerating Shift to Zero Trust and Cloud-First Enterprise Architectures
A fundamental driver of the SASE market is the broad organizational move away from legacy, perimeter-based security architectures toward zero trust frameworks that assume no implicit trust for any user or device. The pandemic-driven normalization of hybrid work has made traditional VPN and on-premises firewall infrastructure structurally inadequate, as organizations now require secure, policy-consistent access to cloud applications and internal resources for users spread across homes, offices, partner sites, and mobile environments. The U.S. federal government's executive order mandating zero trust adoption across agencies and the Cybersecurity and Infrastructure Security Agency's (CISA) published guidance on zero trust and SASE frameworks have accelerated this transition significantly in North America, while similar directives are gaining traction across Europe and Asia-Pacific. These mandates are establishing SASE not as an optional modernization initiative but as a compliance requirement, driving procurement timelines and budget allocations across government, financial services, and critical infrastructure sectors.
Table of contents
11 chapters · 99 sections · 307 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Offering | Security Service Edge (SSE) | — |
| By Deployment Mode | Single-Vendor SASE Segment Maintain Its | — |
| By Organization Size | Large enterprises | Small and medium enterprises (SMEs) |
| By End-use Vertical | BFSI | Healthcare vertical |
By Offering
- The SSE segment accounts for the largest share of the overall SASE market in 2026.
- This dominance is primarily driven by the urgent enterprise need to replace legacy secure web gateways and VPN concentrators with cloud-delivered security capabilities that can protect users and data regardless of access location.
- The SSE bundle -- combining ZTNA, CASB, SWG, and FWaaS under a single policy engine -- addresses the most pressing security challenges of the cloud-first enterprise, including shadow IT visibility, data exfiltration prevention, and real-time malware protection.
- Large-scale SSE deployments by healthcare institutions, financial services firms, and government agencies are reinforcing this segment's leadership position, with vendors like Netskope, Zscaler, and Palo Alto Networks continuing to expand their SSE capability sets through AI-driven enhancements and broader ecosystem integrations.
- The Network-as-a-Service (NaaS) segment, which encompasses SD-WAN solutions and managed SD-WAN services, is expected to grow at a healthy rate during the forecast period.
- As enterprises consolidate their networking and security procurement, SD-WAN's role within the broader SASE architecture is becoming more tightly integrated, with vendors increasingly bundling SD-WAN capabilities into their SASE licensing tiers rather than selling them as standalone products.
By Deployment Mode
- The single-vendor SASE segment holds the largest market share in 2026, driven by the growing enterprise recognition that managing separate networking and security products from multiple vendors introduces policy inconsistencies, integration overhead, and higher operational costs.
- A unified SASE platform delivered by a single vendor allows network and security teams to manage all functions -- from SD-WAN and ZTNA to CASB and DLP -- from one console, with consistent policy enforcement and a single point of accountability for performance and security outcomes.
- Vendors such as Cato Networks, Fortinet, and Palo Alto Networks have continued to invest heavily in deepening the native integration of their networking and security stacks, reinforcing this segment's appeal.
- The dual-vendor SASE segment, where organizations pair a best-of-breed SD-WAN provider with a dedicated SSE vendor, continues to serve enterprises with existing infrastructure investments that make a full-stack migration impractical in the near term.
- However, as single-vendor platforms mature and integration complexity becomes a more prominent total cost of ownership consideration, the dual-vendor approach is expected to gradually give way to consolidated platforms across most enterprise segments during the forecast period.
By Organization Size
- Large enterprises account for the majority of SASE revenue in 2026, reflecting their greater network complexity, larger distributed workforce footprints, and the scale of their cloud application environments.
- The operational and financial case for SASE is most compelling at enterprise scale, where the consolidation of multiple point security products and legacy WAN infrastructure into a single platform delivers measurable reductions in licensing costs, management overhead, and incident response times.
- Financial institutions, global manufacturers, and multinational technology firms are among the most active SASE adopters, driven by the convergence of regulatory pressure, ransomware risk, and the scale of their digital transformation initiatives.
- Small and medium enterprises (SMEs) represent the fastest-growing organization size segment during the forecast period, as managed service providers (MSPs) and managed security service providers (MSSPs) increasingly offer SASE as a turnkey, subscription-based service that eliminates the need for in-house security expertise and capital-intensive infrastructure deployment.
- This consumption model has substantially lowered the barrier to enterprise-grade security for mid-market organizations, creating a large and rapidly expanding addressable market that was previously underserved by traditional security vendors.
By End-use Vertical
- The banking, financial services, and insurance (BFSI) vertical commands the largest share of the global SASE market in 2026.
- This leadership stems from the sector's combination of stringent regulatory obligations -- including PCI DSS v4.0, DORA in Europe, and FFIEC guidelines in the U.S. -- and the high sensitivity of the financial data it handles.
- BFSI institutions manage vast volumes of transactions and sensitive customer data across globally distributed operations, making consistent, identity-aware access control and real-time threat detection a non-negotiable operational requirement.
- SASE platforms that deliver continuous compliance monitoring, granular data loss prevention, and automated incident response are particularly compelling for financial services firms seeking to meet regulatory mandates without expanding their security operations headcount.
- The IT and telecom vertical is poised for steady growth through 2036, fueled by the sector's role as both a primary SASE consumer and a major delivery channel through which managed service providers package and resell SASE capabilities to enterprise clients.
- The healthcare vertical is also emerging as a high-growth segment, driven by the rapid expansion of telehealth services, connected medical device deployments, and the stringent data protection requirements of HIPAA and equivalent regional regulations.
Geographic analysis
North America
Largest shareNorth America holds the largest share of the global SASE market in 2026. This dominance is primarily attributable to the region's high concentration of leading SASE solution providers, mature enterprise cybersecurity awareness, and strong regulatory impetus driving zero trust adoption across both public and private sectors. The United States alone accounts for the majority of regional revenue, with federal mandates requiring civilian agencies to implement zero trust architectures and CISA's published guidance on SASE frameworks accelerating procurement timelines across government and critical infrastructure. The presence of established vendors including Palo Alto Networks, Zscaler, Netskope, Cisco Systems, Cloudflare, Versa Networks, and Cato Networks, alongside a well-developed channel of MSSPs and systems integrators, provides North American enterprises with robust go-to-market access to mature, fully supported SASE deployments.
Asia-Pacific
Fastest growthAsia-Pacific is the fastest-growing regional market for SASE during the forecast period, driven by rapid cloud infrastructure investment across China, India, Japan, South Korea, and Southeast Asia. The region's large and rapidly digitizing enterprise base, combined with growing awareness of sophisticated cyber threats and evolving data protection regulations, is creating strong demand for cloud-delivered security platforms that can scale with the pace of digital transformation. Governments across the region are also actively promoting cybersecurity frameworks aligned with zero trust principles, further accelerating enterprise adoption.
Europe
Europe represents a substantial and steadily growing share of the global SASE market, shaped by the continent's stringent data sovereignty and privacy regulations, including the General Data Protection Regulation (GDPR) and the Digital Operational Resilience Act (DORA) for financial services. The regulatory requirement for in-region data processing and storage is driving European enterprises to prioritize SASE vendors with locally distributed points of presence and the ability to enforce data residency policies at the platform level. Germany, the United Kingdom, France, and the Netherlands are among the most active adoption markets, supported by a mature enterprise IT landscape and a well-developed ecosystem of regional managed security service providers.
Competitive landscape
- Palo Alto Networks, Inc.
- Netskope, Inc.
- Zscaler, Inc.
- Fortinet, Inc.
- Cato Networks, Ltd.
Frequently asked questions
The global SASE market is expected to grow from USD 12.6 billion in 2026 to USD 76.6 billion by 2036.
Cite this report
Meticulous Research. (2026). Secure Access Service Edge (SASE) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1805). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/secure-access-service-edge-market-6488