SCADA Market (2024-2031)
The SCADA Market is expected to reach $18.7 billion by 2031, at a CAGR of 9% from 2024 to 2031.
- Published
- Jan 2024
- Pages
- 226
- Format
- PDF + Excel
- Report ID
- MRICT - 104492
- Base year
- 2023
- 2031 · FORECAST
- $18.70B
- 2031
- $18.70B
- CAGR 2024–2031
- 9%
2023 baseline · 2024–2031 forecast at 9% CAGR · hover a bar for the value
Key highlights
By Type: In 2024, the Networked SCADA Systems Segment to Dominate the SCADA Market
By Component: In 2024, the Hardware Segment to Dominate the SCADA Market
By Deployment Mode: In 2024, the On-premise Deployments Segment to Dominate the SCADA Market
By End-use Industry: In 2024, the Manufacturing Segment to Dominate the SCADA Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 226 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 9% |
| Market Size (Value) | USD 18.7 Billion by 2031 |
| Segments Covered | By Type · Monolithic SCADA Systems · Distributed SCADA Systems · Networked SCADA Systems · Other SCADA Systems · By Component · Hardware · Human-Machine Interface (HMI) · Distributed Control Systems (DCS) · Remote Terminal Units (RTU) · Programmable Logic Controllers (PLC) · Process Control Systems (PCS) · Communication Systems · Other Hardware Components · Software · Services · Professional Services · Managed Services · By Deployment Mode · On-premise Deployments · Cloud-based Deployments · By End-use Industry · Oil & Gas · Pipeline Monitoring and Controls · Remote Equipment and Asset Monitoring · Off-shore Platforms and On-shore Wells · Other Applications · Automotive · System Monitoring · Automated Controls · Data Collection and Analysis · Other Applications · Food & Beverage · Monitoring Control · F&B Product Consistency · Regulatory Compliance · Other Applications · Semiconductors & Electronics · Smart Machinery Maintenance · Process Traceability · Elimination of Manual Operation · Other Applications · IT & Telecommunications · Real-time Data Analysis · Automation of Processes · Network Security · Other Applications · Agriculture · Greenhouse Automation · Irrigation Control · Livestock Farming · Other Applications · Pharmaceuticals & Healthcare · Pharmaceutical Manufacturing Processes · Hospital Facilities Management · Other Applications · Transportation · Airports & Aviation · Ports & Harbors · Railway Systems · Other Applications · Manufacturing · System Monitoring · Automated Controls · Data Collection and Analysis · Process Automation and Control · Other Applications · Other End-use Industries |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Rest of Asia-Pacific), Latin America, and the Middle East & Africa |
| Key Companies | Rockwell Automation, Inc. (U.S.), Siemens AG (Germany), Eaton Corporation plc (Ireland), Schneider Electric SE (France), ABB Ltd (Switzerland), Yokogawa Electric Corporation (Japan), General Electric Company (U.S.), Emerson Electric Co. (U.S.), Honeywell International, Inc. (U.S.), Mitsubishi Electric Corporation (Japan), OMRON Corporation (Japan), Pilz GmbH & Co. KG (Germany), Survalent Technology Corporation (Canada), Valmet (Finland), and Hitachi, Ltd. (Japan) |
Report overview
Segments covered: type, component, deployment mode, end-use industry. Regions: North America, Europe, Asia-Pacific.
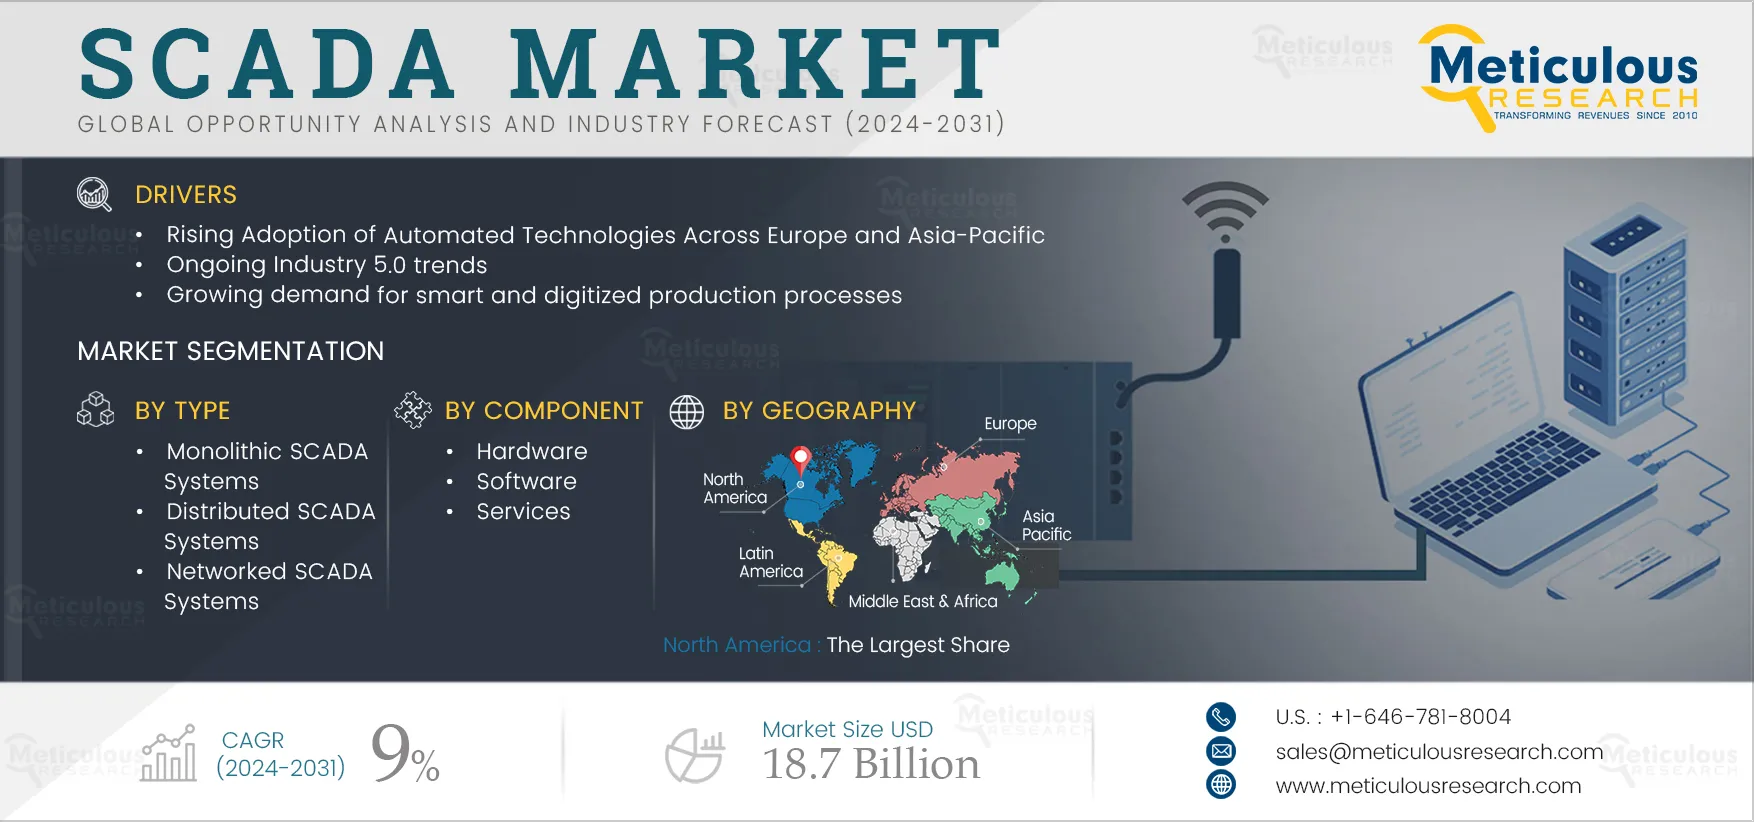
The growth of this market is attributed to the rising adoption of automated technologies across Europe and Asia-Pacific, the ongoing Industry 5.0 trends, growing demand for smart and digitized production processes, and government support and initiatives for industrial automation. Moreover, the increasing trend of wireless sensor networks and the proliferation of smart factories are expected to offer growth opportunities for the players operating in this market.
Report infographic
Market dynamics
5 factors across 3 forcesRising Adoption of Automated Technologies Across Europe and Asia-Pacific Driving Market Growth
Increased competition and evolving customer requirements have compelled Europe’s manufacturing sector to embrace novel technologies and solutions for digital transformation. The major industries adopting automation in Europe include oil & gas, chemicals & petrochemicals, power & utilities, food & beverage, and automotive. Companies are investing in SCADA software, which is an integral part of automation systems. In September 2022, Schneider Electric (France) acquired AVEVA (U.K.), a leading industrial software provider, to accelerate its software growth strategy and enhance its hybrid cloud-based subscription model.
Automation in APAC is driven by population growth, urbanization, economic development, and increasing wages. The Government of China has launched the Made in China 2025 initiative to upgrade the Chinese industry. With this initiative, China plans to expand its high-tech sectors and further develop its advanced manufacturing base. The program aims to use government subsidies, mobilize state-owned enterprises, and pursue intellectual property acquisition to catch up with Western technological prowess in advanced industries. The Made in China 2025 initiative is the Chinese government's ten-year plan to upgrade the Chinese manufacturing base by developing ten high-tech industries. Such developments in Europe and Asia-Pacific are promoting industrial automation, driving the growth of the SCADA market.
Growing Demand for Smart and Digitized Production Processes Driving the Adoption of SCADA Systems
Smart production refers to the integration of advanced technologies such as the Internet of Things (IoT), Artificial Intelligence (AI), and automation into manufacturing processes, whereas digitized production includes the digitization of production data, workflows, and communication channels to streamline operations, enhance visibility, and improve collaboration. In both these production scenarios, SCADA systems play a crucial role in facilitating data-driven decision-making, optimizing production efficiency, and ensuring seamless integration and coordination of manufacturing operations.
SCADA systems are used for data management, information management, energy management, and diagnostics management in digitized production processes. As a result, manufacturers across various industries are increasingly turning to SCADA systems to monitor, control, and automate their production operations. SCADA systems help in collecting and analyzing data from IoT devices, enabling predictive maintenance, remote monitoring, and intelligent decision-making to improve Overall Equipment Effectiveness (OEE) and reduce downtime. All these benefits, along with the need to optimize production operations and improve efficiency, are increasing the adoption of SCADA systems across various industries, driving market growth.
Table of contents
12 chapters · 129 sections · 226 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Networked SCADA Systems | Networked SCADA systems |
| By Component | Hardware | Software |
| By Deployment Mode | On-premise Deployments | Cloud-based deployments |
| By End-use Industry | Manufacturing | — |
By Type
- The networked SCADA systems segment is expected to account for the largest share of 47.5% of the global SCADA market.
- The large market share of this segment is attributed to the benefits offered by these systems including flexibility, scalability, and use of common communication protocol facilitating better data exchange.
- Various end-use industries, such as oil & gas, industrial manufacturing, and power & utility, have adopted this architecture.
- The networked SCADA systems segment is also projected to register the highest CAGR during the forecast period.
By Component
- The Hardware Segment to Dominate the SCADA Market
- The hardware segment is expected to account for the largest share of 55.9% the global SCADA market.
- The large market share of this segment is attributed to the rising adoption of automated technologies, the rising focus of players on innovative product offerings, and the growing demand for smart and digitized production processes.
- However, the software segment is expected to record the highest CAGR during the forecast period.
- The growth of this segment is attributed to the increasing focus of industry players on introducing innovative SCADA software.
By Deployment Mode
- The on-premise deployments segment is expected to account for the larger share of 65.4% of the global SCADA market.
- The large market share of this segment is attributed to the high preference for on-premise deployments among large enterprises due to the availability of trained IT professionals & infrastructure and security issues associated with cloud-based deployments.
- However, the cloud-based deployments segment is expected to record the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the benefits of cloud infrastructure, such as ease of adoption, minimal requirements for in-house infrastructure, high scalability, and easy installation of SCADA solutions.
By End-use Industry
- The Manufacturing Segment to Dominate the SCADA Market
- The manufacturing segment is expected to account for the largest share of 26.4% of the global SCADA market.
- The large market share of this segment is attributed to the rising adoption of industrial automation and control systems in the manufacturing sector, the growing demand for smart and digitalized production processes, and the proliferation of smart factories.
- However, the automotive segment is expected to register a higher CAGR during the forecast period.
- The growth of this segment is attributed to the rising need to gather real-time data to control and monitor industrial equipment and manufacturing processes and the rising adoption of industrial robots, machine vision systems, and industrial control systems.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 32.1% of the global SCADA market. The market growth in North America is driven by the presence of key market players in the region, the growing demand for automation and process control solutions, the increased use of automation in the industrial sectors, and the need to improve productivity, quality, and efficiency of production processes. In 2024, the North America Region to Dominate the SCADA Market
Asia-Pacific
Fastest growthAsia-Pacific SCADA market is estimated to be worth USD 3.3 billion in 2024. However, the Asia-Pacific region is projected to record the highest CAGR during the forecast period. The growth of this market is attributed to the increasing investment in smart factories, growing FDI in the industrial sector, increasing worker safety regulations, and rising demand for industrial control solutions in manufacturing companies.
Competitive landscape
- October 2022
ZPE Systems (U.S.) launched the Mini SR, a smartphone-size, cloud-orchestrated gateway that solves the operational challenges of running security and connectivity at the network edge. The Mini SR is perfect for managing remote manufacturing equipment, SCADA systems, medical imaging devices, and even oil & gas equipment sensors.
- December 2020
Hitachi ABB Power Grids launched the RTU530, an all-new Remote Terminal Unit (RTU) that builds on the established reliability and efficiency of the RTU500 series. The RTU introduced new advanced functionality, including faster processing capabilities and a simple and user-friendly interface.
- November 2022
Arduino launched its first micro PLC for Industrial IoT and building automation applications. The new PLC is designed to enable high-performance computing, a high level of data security, rapid development, and availability in three different variants to better suit end-user needs.
- Rockwell Automation, Inc. (U.S.)
- Siemens AG · Germany
- Eaton Corporation plc · Ireland
- Schneider Electric SE · France
- ABB Ltd · Switzerland
- Yokogawa Electric Corporation · Japan
- General Electric Company (U.S.)
- Emerson Electric Co. (U.S.)
- Honeywell International, Inc. (U.S.)
- Mitsubishi Electric Corporation · Japan
- OMRON Corporation · Japan
- Pilz GmbH & Co. KG · Germany
- Survalent Technology Corporation · Canada
- Valmet · Finland
- Hitachi, Ltd. · Japan
Frequently asked questions
The SCADA market study focuses on the market assessment and opportunity analysis through the sales of SCADA across different region, and countries across different market segmentation. This study is also focused on competitive analysis for SCADA based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). SCADA Market - Global Opportunity Analysis And Industry Forecast (2024-2031) (Report No. MRICT - 104492). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/scada-market-5186