Saudi Arabia Medical Devices Market (2025-2032)
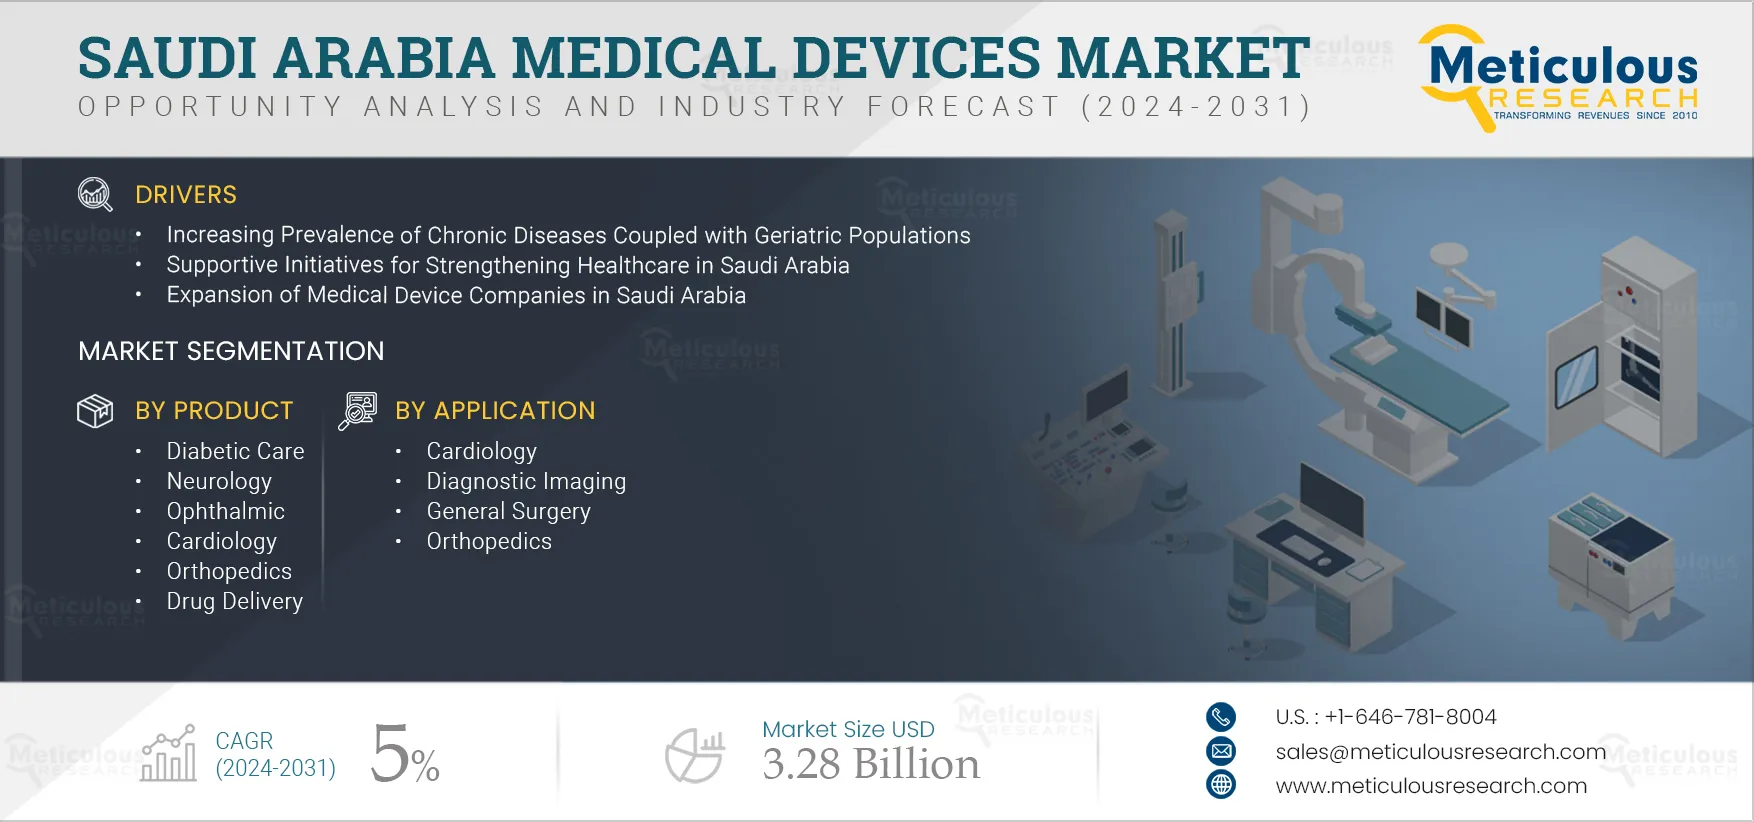
The Saudi Arabia Medical Devices Market was valued at $2.19 billion in 2024. This market is expected to reach $3.28 billion by 2032 from an estimated $2.33 billion in 2025, at a CAGR of 5% during the forecast period of 2025-2032. Saudi Arabia Medical Devices Market Size & Forecast The growth of the
- Published
- Nov 2024
- Pages
- 240
- Format
- PDF + Excel
- Report ID
- MRHC - 1041416
- Base year
- 2024
- 2024 · BASELINE
- $2.19B
- 2032
- $3.28B
- CAGR 2025–2032
- 5%
2024 baseline · 2025–2032 forecast at 5% CAGR · hover a bar for the value
Key highlights
By Product: The Monitoring Devices Segment to Dominate the Saudi Arabia Medical Devices Market in 2025
By Risk Type: The Low-Risk Medical Devices Segment to Dominate the Saudi Arabia medical devices Market in 2025
By Application: The Diagnostic imaging Segment is Expected to Dominate the Saudi Arabia medical devices Market in 2025
By End User: The Hospitals & Clinics Segment is Expected to Account for the Largest Share of the Saudi Arabia medical devices Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 350 |
| Format | |
| Forecast Period | 2025-2032 |
| Base Year | 2024 |
| CAGR | 5% |
| Estimated Market Size (Value) | $3.28 Billion by 2032 |
| Segments Covered | By Product · Monitoring Devices · Diabetic Care · Invitro Diagnostics (IVD) · Neurology · Ophthalmic · Diagnostic Imaging · Cardiology · Orthopedics · Drug Delivery · General and Plastic Surgery · Dental · Wound Management · Endoscopy · Ear, Nose & Throat · Nephrology · General Hospital & Healthcare · Skin Care & Aesthetics · Other Products · (Note: Other Products include immunoassay, Gynecology, Pediatric, Urology, and Cryogenic.) · By Risk Type · Low Risk Medical Devices · Moderate Risk Medical Devices · High Risk Medical Devices · By Application · Cardiology · Diagnostic Imaging · General Surgery · Orthopedics · Other Applications · (Note: Other Applications Includes Dental, Nephrology, and Neurology.) · By End User · Hospitals & Clinics · Ambulatory Surgery Centers · Diagnostic Centers & Laboratories · Pharmacies · Other End Users · (Note: Other End Users Include Dental Care Clinics, Blood Banks, Academic Institutes, and Pharmaceutical Firms.) |
| Key Companies Profiled | Koninklijke Philips N.V. (Netherlands), GE HealthCare Technologies Inc. (U.S.), Smith+Nephew. (U.K.), Zimmer Biomet. (U.S), Siemens Healthineers AG (Germany), F. Hoffmann-La Roche Ltd. (Switzerland), Becton, Dickinson and Company (U.S), Olympus Corporation (Japan), Johnson & Johnson (U.S.), Medtronic plc (Ireland), Drägerwerk AG & Co. KGaA (Germany) and Abbott Laboratories (U.S.). |
Report overview
Segments covered: product, monitoring device, diabetic care, neurology, ophthalmic, diagnostic imaging, cardiology, orthopedic, drug delivery, general, plastic surgery, dental, wound management, endoscopy, ear, nose & throat, nephrology, general hospital & healthcare, skin care & aesthetic, other product, risk type, low risk medical device, moderate risk medical device, high risk medical device, application, general surgery, other application, end user, hospitals & clinic, ambulatory surgery center, diagnostic centers & laboratory, pharmacy, other end user.
The growth of the Saudi Arabia medical devices market is primarily driven by the growing prevalence of chronic diseases coupled with the geriatric population, supportive initiatives for strengthening healthcare in Saudi Arabia, and the expansion of medical device companies in Saudi Arabia. Furthermore, the development and transformation of Saudi’s healthcare services and the growing emphasis on medical tourism are expected to generate growth opportunities for the stakeholders in this market.
Report infographic
Market dynamics
3 factors across 2 forcesGovernment Investment for Improving Healthcare
The Government of Saudi Arabia is making ongoing investments to enhance the country's healthcare infrastructure. Key outcomes of these investments include the increasing number of hospitals and healthcare systems, the growing adoption of digital health technologies, and improved access to healthcare services. Under Vision 2032, the government has committed to investing over USD 65 billion to develop healthcare infrastructure. In addition, the Ministry of Health (MoH) and other government agencies are supporting public-private partnerships (PPP) to develop healthcare facilities while minimizing financial burdens.
As part of these efforts, the MoH, in collaboration with private sector entities, is driving initiatives to strengthen healthcare services. For example, in June 2024, the Ministry granted Altakassusi Alliance Medical LLC—a joint venture between Alliance Medical Group, King Faisal Specialist Hospital & Research Center, and Nexus Gulf Healthcare—a project to enhance radiology and imaging services across seven hospitals in Saudi Arabia. This collaboration aims to transfer knowledge, upskill the local healthcare workforce through training programs, and improve the quality of care. The expansion of imaging services requires advanced diagnostic devices, further contributing to the growth of the medical device market in the region.
Expansion of Medical Device Companies in Saudi Arabia
The expansion of healthcare and medical device companies in Saudi Arabia is driving growth in the medical device sector. Companies are increasing their presence in the country due to strong government support, health initiatives, and a rapidly growing healthcare ecosystem. This expansion enhances accessibility to medical devices, allowing companies to meet the needs of an underserved customer base. Several medical device companies have already strengthened their foothold in Saudi Arabia. For example:
- In February 2025, Johnson & Johnson MedTech (U.S.) started direct operations in Saudi Arabia. The company offers high-tech medical and surgical equipment. This strategic development is in line with the company’s commitment to improving healthcare in Saudi Arabia.
- In February 2025, Siemens Healthineers partnered with Dallah Health (Saudi Arabia) to expand its strategic partnership in Saudi Arabia. This collaboration aims to transform healthcare delivery by integrating advanced technologies in various business units such as technology management, operations, workforce development, and facility design.
Table of contents
11 chapters · 95 sections · 240 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Product Type | Monitoring devices | Diabetic care devices |
By Product Type
- The Monitoring Devices segment is expected to account for the largest share of the Saudi Arabia Medical Devices Market.
- The large share of this segment is driven by the increasing burden of chronic diseases, widespread adoption of advanced medical practices, and high population density.
- As the population grows, coupled with a higher incidence of chronic conditions, there is a growing need for healthcare solutions to monitor health status and access real-time data.
- This demand is fueling the growth of the in vitro diagnostics (IVD) devices market.
- However, the diabetic care devices segment is slated to register the highest CAGR during the forecast period.
- The increasing prevalence of diabetes in Saudi Arabia, coupled with technological advancements in diabetic care devices, is driving market growth.
- The rising number of hospital admissions and growing awareness about diabetes among patients further contribute to the demand for diabetic care devices.
- For example, a study published in the *Cureus* journal indicates that approximately 49.9% of hospitalized patients in Riyadh have diabetes.
- This high rate of diabetes-related hospitalizations is prompting healthcare providers to invest in and adopt the latest diabetic care devices, thereby accelerating market growth.
Competitive landscape
- January 2025
Scientific & Medical Equipment House Co. (Saudi Arabia) signed a distribution agreement with Haier Germany to market and distribute operating room equipment in Saudi Arabia. This partnership aims to expand the company's customer base and portfolio of medical equipment agencies in the region.
- April 2024
Dr. Sulaiman AL Habib Medical Group (Saudi Arabia) invested USD 1.73 billion to construct six hospitals in Saudi Arabia with advanced medical facilities and innovative healthcare services.
- April 2021
Analytica Limited (Australia) signed an agreement with Al Marwa Medical Supplies (Marwa) to distribute and commercialize the enhanced infusion system to hospital systems in the Middle East region.
- Koninklijke Philips N.V. · Netherlands
- GE HealthCare Technologies Inc. (U.S.)
- Smith+Nephew. (U.K.)
- Zimmer Biomet. (U.S)
- Siemens Healthineers AG · Germany
- F. Hoffmann-La Roche Ltd. · Switzerland
- Becton
- Dickinson and Company (U.S)
- Olympus Corporation · Japan
- Johnson & Johnson (U.S.)
- Medtronic plc · Ireland
Frequently asked questions
The Saudi Arabia medical devices market size was valued at $ 2.19 billion in 2024.
Cite this report
Meticulous Research. (2024). Saudi Arabia Medical Devices Market - Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 1041416). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/saudi-arabia-medical-devices-market-6099