Robotic Welding Market (2022-2029)
Robotic Welding Market is expected to reach $6.77 billion by 2029, at a CAGR of 6.2% during the forecast period of 2022–2029. By volume, this market is expected to reach 163.3 thousand units by 2029, at a CAGR of 11.2% from 2022 to 2029.
- Published
- Sep 2022
- Pages
- 327
- Format
- PDF + Excel
- Report ID
- MRSE - 104617
- Base year
- 2021
- 2029 · FORECAST
- $6.77B
- 2029
- $6.77B
- CAGR 2022–2029
- 6.2%
2021 baseline · 2022–2029 forecast at 6.2% CAGR · hover a bar for the value
Key highlights
Robots Segment Expected to Account for Largest Market Share in 2022
Resistance Spot Welding Segment Slated to Register Fastest Growth Rate During Forecast Period
25 kg to 100 kg Segment Slated to Register Fastest Growth Rate During Forecast Period
Automotive & Transportation Segment Slated to Register Fastest Growth Rate During Forecast Period
Asia-Pacific: Fastest-growing Regional Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2021 |
| Estimated Year | 2022 |
| Forecast Period | 2022–2029 |
| Market Size (2029) | USD 6.77 billion |
| CAGR (2022–2029) | 6.2% |
| Format | PDF, Excel & Cloud Portal · 327 pages |
| Segments Covered | By Component: Robots Articulated Robots, Cartesian Robots, Cylindrical Robots, SCARA Robots, Collaborative Robots, Delta Robots, Other Robots, Welding Torches, Vision Systems, Sensors, Feeder Systems, Plasma Flow Controllers, Other EOAT Devices · By Payload: Less than 25 kg Payload, 25 kg to 100 kg Payload, More than 100 kg Payload · By Welding Process: Resistance Spot Welding, Arc Welding, Laser Welding, Plasma Welding, Ultrasonic Welding, Other Welding Processes · By End-use Industry: Automotive & Transportation, Oil & Gas, Electrical, Construction, Aerospace, Mining, Shipbuilding, Heavy Engineering Equipment, Defense, Other End-use Industries |
| Countries Covered | Asia-Pacific (Japan, South Korea, Australia & New Zealand, India, Thailand, Singapore, Taiwan, Rest of Asia-Pacific), North America (U.S., Canada), Europe (Germany, Norway, U.K.) |
| Key Companies | ABB Ltd, FANUC Corporation, KUKA AG, Yaskawa Electric Corporation, Kawasaki Heavy Industries, Ltd., DAIHEN Corporation, International AG, EVS Tech Co., Ltd, Panasonic Corporation, Estun Automation Co., Ltd., United ProArc Corporation, Nachi-Fujikoshi Corp., Robotersysteme AG |
Report overview
Segments covered: component, payload, welding process, end-use industry. Regions: Asia-Pacific, North America, Europe.
The growth of this market is driven by the increasing adoption of industry 4.0 principles and the rising adoption of welding robots in the automotive industry. However, the high initial cost of installing welding robots is expected to restrain the growth of this market.
Government initiatives to support digital transformation in Asia-Pacific and the emergence of laser & plasma welding technologies are expected to provide significant growth opportunities for stakeholders in this market. However, the lack of skilled workers for operating welding robots is expected to pose a major challenge to the growth of this market.
The COVID-19 outbreak caused a widespread economic downturn as several countries imposed strict lockdowns to contain the infection, resulting in the closure of manufacturing facilities and disruptions in supply chains and production schedules. The outbreak of the COVID-19 pandemic had a significant impact on technology and component supply chains globally. Furthermore, restrictions placed on transport led to the shortage of raw materials required for the production of advanced welding equipment
The top players in the welding robotics market are headquartered in Japan. These players witnessed a major decline in their revenue in 2019. For instance, in March 2020, FANUC (Japan) announced that its ROBOT division revenue was down 6.9% in 2019 compared to 2018. The COVID-19 pandemic disrupted the global supply chain and reduced the installation of industrial robots in various key industries, such as automotive, electrical, electronics, and metals & machinery.
The pandemic adversely affected the industrial sector due to the reduced demand for high-cost products. During the nationwide lockdowns, consumers limited their spending on only the most essential goods & services, reducing the demand for consumer goods, high-cost electronics, textiles, automobiles, and machinery, which impacted the major application sectors of the robotic welding market. With countries resuming trade and economic activity and stability in consumer lifestyles, the spending on these products and services is expected to increase, boosting the demand for automation solutions over the coming years. The market is expected to recover in 2022 due to restrictions on the number of personnel allowed at manufacturing facilities.
A laser welding robot uses a laser beam, which is developed using carbon dioxide and targeted with the help of optics at workpieces to weld different parts together. Laser welding technology offers numerous advantages in the production of medium- and large-batch sizes of output products at a low unit cost. It offers high welding speed, reduces rework, provides high reliability, ensures increased weld quality, and offers high precision. This technology allows narrow welds that require minimal changes to the welded items.
Laser welding technology is used in remote welding locations that are hard to reach. It can also be used in high-volume applications that require increased accuracy in the automotive & transportation, electrical and electronics, and aerospace & defense industries.
Similarly, plasma welding technology offers numerous advantages, including high power density, clean and smooth welds, high welding speed, low distortion, and improved gap bridging. The welds produced through plasma welding are durable and less noticeable. The numerous advantages offered by plasma welding technology drive its adoption in the automotive & transportation and electrical & electronics industries.
Report infographic
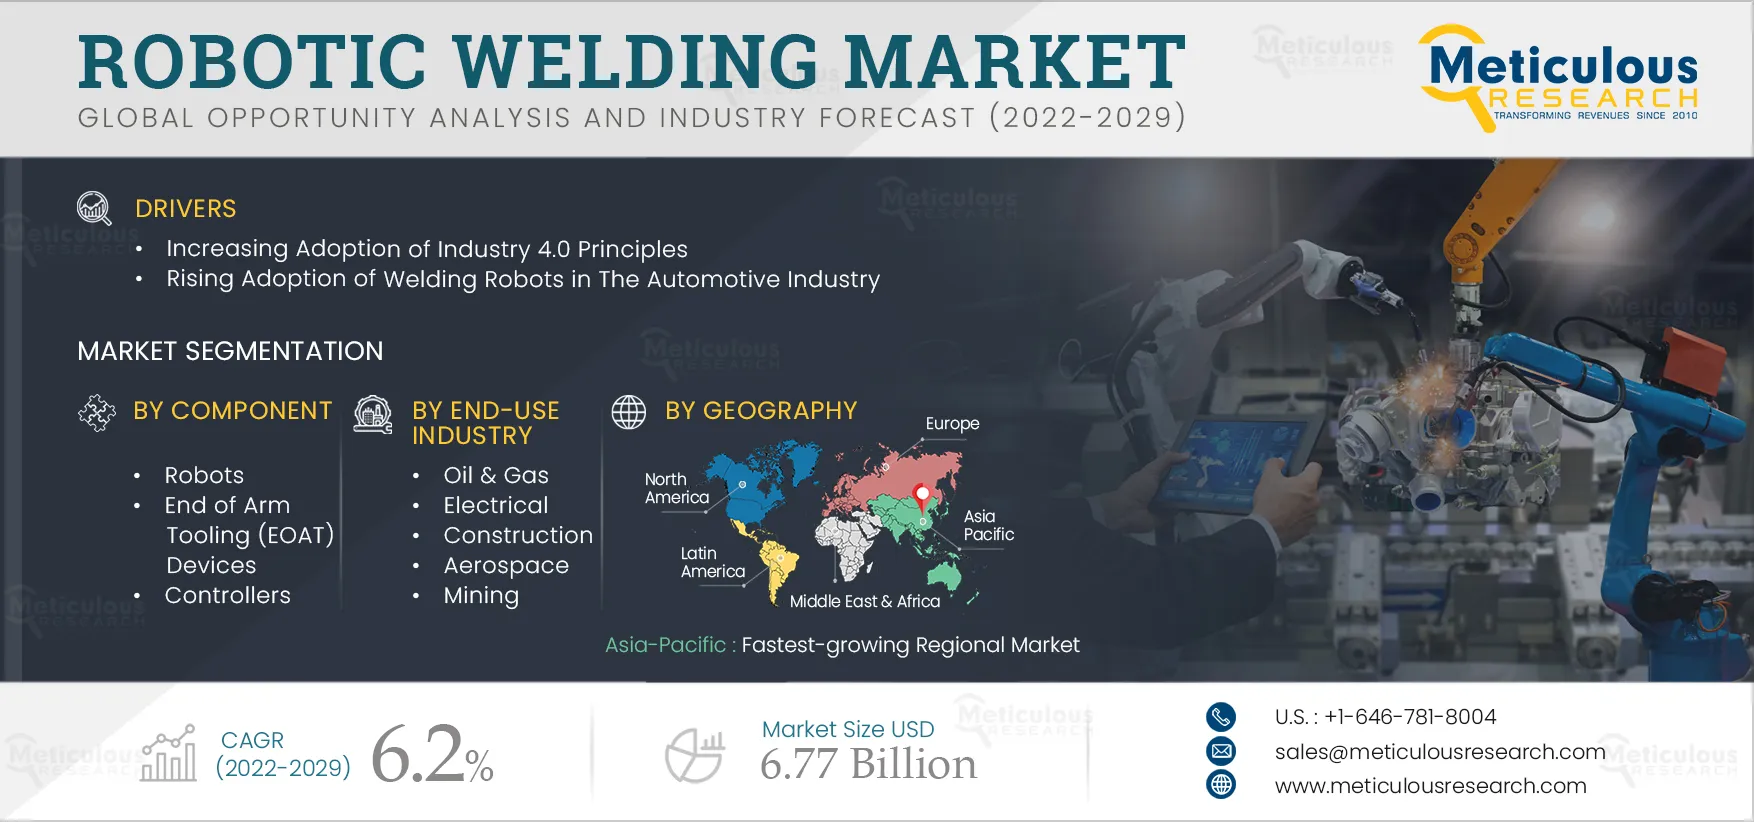
Table of contents
13 chapters · 121 sections · 327 pages · click to expandSegmental analysis
| Segment | Largest share (2022) | Fastest growth (2022–2029) |
|---|---|---|
| By Component | Robots Segment Expected | — |
| By Welding Process | — | Resistance spot welding |
| By Payload | — | 25 kg |
| By End-use Industry | — | Automotive & transportation |
By Component
- Robots Segment Expected to Account for Largest Market Share in 2022
- The robots segment is further subsegmented into articulated robots, cartesian robots, cylindrical robots, SCARA robots, collaborative robots, delta robots, and other robots.
- Furthermore, the end of arm tooling (EOAT) devices segment is subsegmented into welding torches, vision systems, sensors, feeder systems, plasma flow controllers, and other EOAT devices.
- The robots segment is expected to account for the largest share of the robotic welding market.
- The large market share of this segment is attributed to the wide usage of robots across various industries, including automobile, oil & gas, general manufacturing, and defense.
- These robots are highly flexible in their configurations, enabling users to adjust their speed, precision, stroke length, and size.
By Welding Process
- Resistance Spot Welding Segment Slated to Register Fastest Growth Rate During Forecast Period
- The resistance spot welding segment is slated to register the highest CAGR during the forecast period.
- High payload resistance spot welding robots are widely used in the automotive & transportation, construction, and metals & machinery industries for heavy-duty applications.
- Hence, the increased demand from these industries contributes to the growth of this segment.
By Payload
- 25 kg to 100 kg Segment Slated to Register Fastest Growth Rate During Forecast Period
- The 25 kg to 100 kg segment is slated to register the highest CAGR during the forecast period.
- The automotive & transportation, construction, and shipbuilding industries are the largest end users of welding robots with payloads of 25 kg to 100 kg.
- Thus, the increasing demand from these industries for welding heavy-body panels contributes to the high market growth of this segment.
By End-use Industry
- Automotive & Transportation Segment Slated to Register Fastest Growth Rate During Forecast Period
- The automotive & transportation segment is slated to register the highest CAGR during the forecast period.
- The growth of this segment is driven by the benefits offered by welding robots in the automotive industry’s manufacturing process, such as cost-effectiveness, high efficiency, safety, and speed & precision, resulting in the increased adoption of these welding robots.
- Furthermore, using robots enables car & automotive component makers to accelerate production, reduce costs, improve quality, and ensure workers' safety.
Geographic analysis
Asia-Pacific
Fastest growthAsia-Pacific is slated to register the highest CAGR during the forecast period. The high market growth in Asia-Pacific is attributed to the increasing labor costs, driving manufacturers to automate the manufacturing processes to maintain their cost advantage. Furthermore, Asia-Pacific is poised to retain a strong market position in the welding robots market due to cheap manufacturing costs attributable to the availability of cheap labor, high safety standards, and government initiatives to accelerate foreign direct investments (FDIs). Asia-Pacific: Fastest-growing Regional Market
Competitive landscape
- ABB Ltd
- FANUC Corporation
- KUKA AG
- Yaskawa Electric Corporation
- Kawasaki Heavy Industries, Ltd.
- DAIHEN Corporation
- International AG
- EVS Tech Co., Ltd
- Panasonic Corporation
- Estun Automation Co., Ltd.
- United ProArc Corporation
- Nachi-Fujikoshi Corp.
- Robotersysteme AG
Frequently asked questions
The
robotic welding market is expected to grow at a CAGR of 6.2% from 2022 to reach $6.77 billion by 2029.
Cite this report
Meticulous Research. (2022). Robotic Welding Market - Global Opportunity Analysis And Industry Forecast (2022-2029) (Report No. MRSE - 104617). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/robotic-welding-market-5303