Latin America Pharmaceutical Manufacturing Equipment Market (2026-2036)
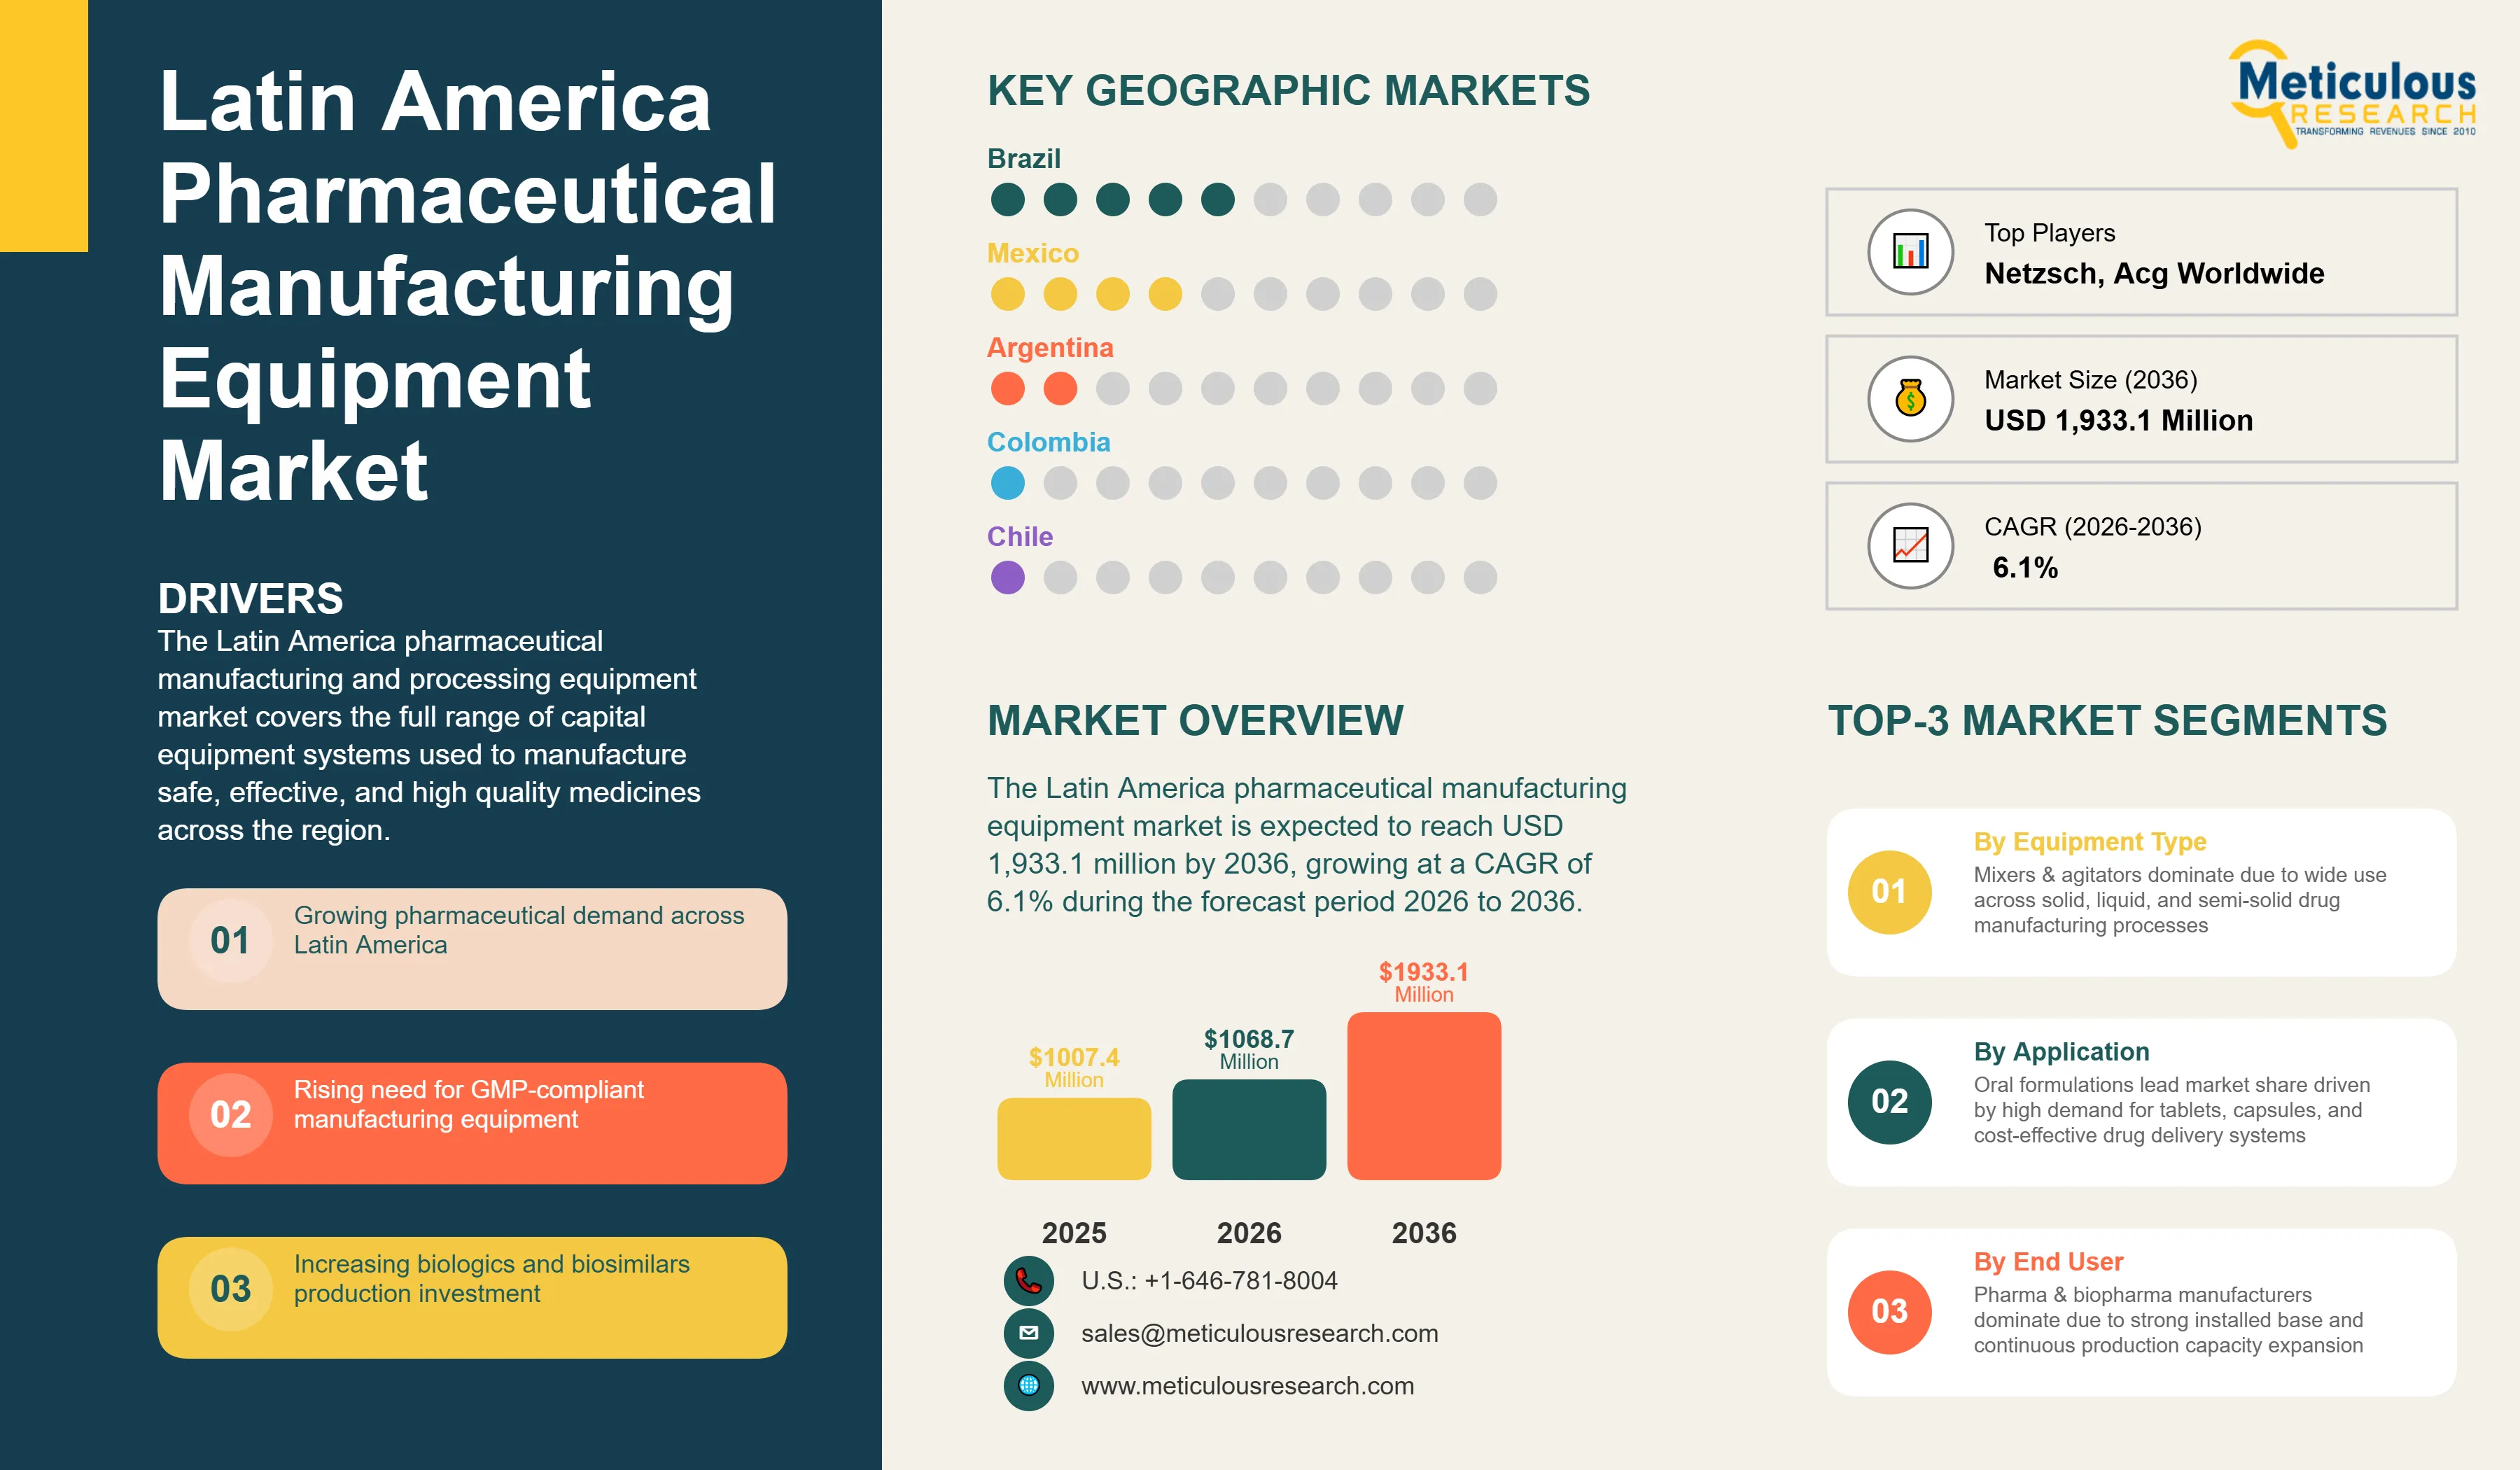
The Latin America pharmaceutical manufacturing equipment market was valued at USD 1,007.4 million in 2025. This market is expected to reach USD 1,933.1 million by 2036 from an estimated USD 1,068.7 million in 2026, growing at a CAGR of 6.1% during the forecast period 2026 to 2036.
- Published
- Apr 2026
- Pages
- 205
- Format
- PDF + Excel
- Report ID
- MR-1854
- Base year
- 2025
- 2025 · BASELINE
- $1.01B
- 2036
- $1.93B
- CAGR 2026–2036
- 6.1%
2025 baseline · 2026–2036 forecast at 6.1% CAGR · hover a bar for the value
Key highlights
The Latin America pharmaceutical manufacturing equipment market is projected to reach USD 1,933.1 million by 2036. The market is expected to grow at a CAGR of 6.1% during the forecast period 2026 to 2036. The market was estimated at USD 1,068.7 million in 2026.
Brazil is expected to dominate the market with the largest share in 2026, driven by its well established pharmaceutical industry, large domestic demand, significant public healthcare spending, and strong government support for local drug production. The country's mature generics industry, combined with increasing investments in biologics and vaccine manufacturing, continues to support facility modernization and capacity expansion across the region.
Mexico is projected to witness the fastest country level growth during the forecast period, driven by its strong position as an export oriented manufacturing hub, increasing contract manufacturing activities, and the nearshoring momentum generated by the USMCA trade framework. The country's proximity to the United States, cost advantages, and regulatory improvements are attracting significant foreign direct investment in pharmaceutical production infrastructure.
By equipment type, the mixers and agitators segment is expected to hold the largest share in 2026, driven by the widespread application of these systems across multiple stages of solid, liquid, and semi solid drug production. The homogenizers segment is projected to register the highest growth rate during the forecast period, driven by the increasing shift toward biologics, biosimilars, and injectable drug production across the region.
By Mode of Delivery, the oral formulations segment is expected to account for the largest share in 2026, indicate the dominance of solid oral dosage forms across all Latin American healthcare systems. The parenteral formulations segment is projected to register the highest CAGR during the forecast period, driven by the rapidly expanding production of injectable pharmaceuticals including biosimilars, monoclonal antibodies, vaccines, and sterile injectable generics.
By end user, the pharmaceutical and biopharmaceutical manufacturers segment is expected to account for the largest share in 2026, while the contract manufacturing organizations segment is projected to record the highest CAGR during the forecast period, supported by the growing trend of pharmaceutical outsourcing and the rapid scale up of CMO capacity to serve both regional and international demand.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 1,933.1 Million |
| Market Size in 2026 | USD 1,068.7 Million |
| Revenue Growth Rate (2026 to 2036) | CAGR of 6.1% |
| Format | PDF, Excel & Cloud Portal · 205 pages |
| Dominating Equipment Type | Mixers & Agitators |
| Fastest Growing Equipment Type | Homogenizers |
| Dominating Mode of Delivery | Oral Formulations |
| Fastest Growing Mode of Delivery | Parenteral Formulations |
| Dominating End User | Pharmaceutical & Biopharmaceutical Manufacturers |
| Fastest Growing End User | Contract Manufacturing Organizations (CMOs) |
| Dominating Country | Brazil |
| Fastest Growing Country | Mexico |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: equipment type, mode of delivery, end user.
The Latin America pharmaceutical manufacturing and processing equipment market covers the full range of capital equipment systems used to manufacture safe, effective, and high quality medicines across the region. These include milling equipment, dispersing equipment, homogenizers, mixers and agitators, blending equipment, fluidized bed machines, compression and press equipment, capsule filling equipment, coating equipment, preparation vessels, filtration units, sterilization tunnels, CIP and SIP systems, and aseptic inspection systems deployed across pharmaceutical manufacturers, contract manufacturing organizations, and research institutions throughout Brazil, Mexico, Argentina, Colombia, Chile, Peru, and the broader Latin American region.
The Latin American pharmaceutical manufacturing landscape is characterized by a strong foundation in generic drug production, increasing demand for affordable healthcare, and a gradual but accelerating advancement toward complex formulations including biologics and injectable therapies. As pharmaceutical companies expand their production capabilities to meet growing regional healthcare needs, the demand for advanced, efficient, and GMP compliant manufacturing equipment continues to increase.
The growth of this market is primarily driven by the growing pharmaceuticals market across Latin America, the rising demand for GMP compliant processing equipment to meet ANVISA, COFEPRIS, ANMAT, INVIMA, and DIGEMID regulatory requirements, the growing trend of contract manufacturing in the pharmaceutical sector, and growing investment in biologics and biosimilar manufacturing. Additionally, the USMCA nearshoring trend is driving new pharmaceutical manufacturing investment in Mexico, further propelling market growth.
However, the growth of this market is restrained by the preference for refurbished equipment among smaller regional manufacturers and currency volatility compressing local currency capital equipment budgets, both of which continue to limit the pace of new equipment procurement across certain market segments.
On the other hand, the aseptic injectable and biopharmaceutical manufacturing expansion across Brazil, Mexico, and Argentina, the emergence of pharmaceutical manufacturing hotspots in Colombia, Chile, and Peru, and GMP compliance upgrade cycles driving replacement of aging equipment fleets are expected to generate significant growth opportunities for stakeholders in this market. The limited GMP trained technical workforce outside primary manufacturing hubs and the multi country regulatory complexity across the region remain the major challenges impacting market growth.
Report infographic
Market dynamics
2 factors across 1 forceIncreasing Adoption of Continuous Manufacturing and Process Intensification
Regular adoption of continuous manufacturing technologies alongside process intensification approaches is the major structural shift transforming pharmaceutical manufacturing in Latin America. Traditionally, the region has relied on batch based production models which, despite being well understood and aligned with regulatory frameworks, face inherent challenges related to efficiency, scalability, and real time quality monitoring. Continuous manufacturing helps to overcome these constraints by allowing uninterrupted processing of drug substances and finished products, allowing companies to shorten production cycles, reduce material usage, and deliver more consistent quality through integrated process analytical technologies.
For Latin American manufacturers, this transition carries particular significance in the context of increasing competitive pressure from Asian generic manufacturers and the need to optimize cost structures while simultaneously meeting more stringent international GMP expectations. Leading multinational pharmaceutical companies with regional production facilities in Brazil and Mexico are among the early adopters of this technology, and their investment decisions are beginning to influence broader manufacturing norms across the region. Equipment suppliers are responding by developing modular continuous processing platforms better suited to the mid scale production volumes characteristic of Latin American operations, further supporting adoption.
Rising Focus on Single Use Technologies in Biopharmaceutical Manufacturing
The increasing disposition of single use technologies across biopharmaceutical manufacturing operations represents another important trend shaping equipment procurement patterns in Latin America. As regional manufacturers and contract manufacturing organizations expand their capabilities in biologics, biosimilars, and advanced injectable formulations, the operational and economic advantages of single use bioprocessing systems, including bioreactors, mixing bags, filtration assemblies, and fluid transfer systems, are becoming more widely recognized and adopted. Single use systems eliminate the need for cleaning validation, reduce cross contamination risk, and offer significant flexibility for multi product manufacturing facilities, making them particularly well suited to the contract manufacturing model that is gaining ground across Brazil, Mexico, and Argentina.
The progressive alignment of regional regulatory frameworks with EU GMP Annex 1 sterility requirements and the growing sophistication of ANVISA and COFEPRIS inspection standards are also encouraging manufacturers to invest in more advanced aseptic processing infrastructure, with single use technologies increasingly embedded within these investments. As the regional biologics and biosimilar pipeline deepens over the forecast period, the adoption of single use manufacturing technologies is expected to become more widespread, sustaining a positive demand outlook for the associated equipment categories.
Table of contents
11 chapters · 188 sections · 205 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Equipment Type | Mixers and agitators | Homogenizers |
| Other segments | Mixers and agitators | Parenteral formulations |
| By Mode of Delivery | Oral formulations | Oral formulations |
| By End User | Pharmaceutical and biopharmaceutical manufacturers | Contract manufacturing organizations |
By Equipment Type
- The Latin America pharmaceutical manufacturing equipment industry is segmented into milling equipment, dispersing equipment, homogenizers, mixers and agitators, and other manufacturing equipment.
- The other manufacturing equipment segment is further sub segmented into blending equipment, fluidized bed machines, compression and press equipment, capsule making equipment, capsule filling equipment, coating equipment, preparation vessels, melting vessels and storage tanks, filtration units, sterilization tunnels, CIP and SIP systems, aseptic inspection systems, and other equipment.
- However, the homogenizers segment is expected to witness the fastest growth during the forecast period.
- The high growth of this segment is primarily driven by the increasing shift toward biologics, biosimilars, and injectable drug production across the region.
- Homogenization plays a critical role in particle size reduction, emulsion stability, and formulation of complex drug products, especially in parenteral and advanced therapies.
- Rising investments in sterile manufacturing infrastructure, growing adoption of high pressure homogenization technologies, and increasing focus on high value formulations are accelerating demand for homogenizers.
- Markets such as Mexico and Brazil, which are witnessing growth in export oriented manufacturing and biologics capabilities, are particularly contributing to this trend.
Other segments
- The mixers and agitators segment is expected to account for the largest share of the pharmaceutical manufacturing equipment market in Latin America.
- The large share of this segment is mainly due to their widespread application across multiple stages of drug production, including solid, liquid, and semi solid formulations.
- These systems are essential for ensuring uniform blending, consistency, and stability of pharmaceutical products, making them indispensable across both generics and specialty drug manufacturing.
- Their relatively lower cost compared to high end sterile processing equipment and their applicability in large scale batch production further contribute to their dominant adoption across pharmaceutical manufacturers in the region.
- The oral formulations segment is expected to account for the largest share of the pharmaceutical manufacturing equipment market in Latin America.
- The large share of this segment is primarily attributed to the dominance of solid oral dosage forms tablets, capsules, and granules as the most widely prescribed, dispensed, and consumed pharmaceutical product category across all Latin American healthcare systems.
- Public health programs across Brazil, Mexico, Argentina, Colombia, Chile, and Peru disburse most of their essential medicines budgets through oral solid dosage forms, creating sustained high volume manufacturing requirements that in turn represent the largest installed base of pharmaceutical manufacturing equipment in the region.
- However, the parenteral formulations segment is projected to record the highest growth during the forecast period.
- The growth of this segment is primarily driven by the rapidly expanding production of injectable pharmaceuticals across Latin America, including the increasing manufacture of biosimilars, monoclonal antibodies, vaccines, and sterile injectable generics that require highly specialized and capital intensive aseptic manufacturing equipment.
- The growing investment in biologics manufacturing infrastructure, the progressive adoption of EU GMP Annex 1 aligned sterility standards by ANVISA, COFEPRIS, and other regional regulators, and the regional expansion of contract manufacturing organizations with sterile manufacturing capabilities are collectively generating the fastest growth in equipment demand within the parenteral formulations segment.
- The pharmaceutical and biopharmaceutical manufacturers segment is expected to account for the largest share of the market.
- The large share of this segment is primarily attributed to the region's extensive installed base of captive pharmaceutical manufacturing capacity across Brazil, Mexico, Argentina, Colombia, Chile, and Peru, where both multinational and domestic manufacturers operate dedicated production facilities spanning solid oral dosage forms, liquid formulations, semi solids, and increasingly sterile and biopharmaceutical products.
- However, the contract manufacturing organizations segment is projected to record the highest growth during the forecast period.
- The growth of this segment is primarily driven by the growing trend of pharmaceutical outsourcing across Latin America, the rapid scale up of CMO capacity to serve both regional domestic demand and North American and European pharmaceutical companies seeking cost competitive manufacturing partners in the USMCA zone and the broader Latin American region.
- The growing shift of Latin American CMOs toward higher complexity biopharmaceutical and sterile manufacturing is creating demand for particularly capital intensive equipment categories, including aseptic filling lines, lyophilizers, isolators, and bioreactor based upstream processing systems.
By Mode of Delivery
- The Latin America pharmaceutical manufacturing equipment industry is segmented into oral formulations, parenteral formulations, topical formulations, and other formulations.
By End User
- The Latin America pharmaceutical manufacturing equipment industry is segmented into pharmaceutical and biopharmaceutical manufacturers, contract manufacturing organizations, and research and academic institutions.
Geographic analysis
Latin America
Largest shareIn 2026, Brazil is expected to account for the largest share of the pharmaceutical manufacturing equipment market in Latin America. The large share of Brazil is mainly due to its well established pharmaceutical industry, large domestic demand, and strong government support for local drug production. As the largest pharmaceutical market in the region, Brazil benefits from a robust network of domestic manufacturers, significant public healthcare spending, and regulatory frameworks that encourage local manufacturing. Stringent regulatory standards enforced by ANVISA are driving pharmaceutical companies to upgrade their equipment and comply with international GMP requirements, further supporting sustained demand for advanced manufacturing and processing equipment. However, Mexico is witnessing the rapid growth in the Latin America pharmaceutical manufacturing equipment space. This growth is primarily driven by its strong position as an export oriented manufacturing hub and increasing contract manufacturing activities. The country's proximity to the United States, favorable trade agreements, and cost advantages have made it an attractive destination for global pharmaceutical companies seeking to outsource production. Regulatory improvements, rising foreign direct investment, and the expansion of pharmaceutical exports are accelerating the adoption of advanced and automated manufacturing equipment in Mexico.
Competitive landscape
- GEA Group Aktiengesellschaft · Germany
- IKA-Werke GmbH & Co. KG · Germany
- NETZSCH Group · Germany
- Silverson Machines Ltd. (U.K.)
- Hosokawa Micron Group (Japan and Netherlands)
- Syntegon Technology GmbH · Germany
- Romaco Group · Germany
- ACG Worldwide · India
- Cadmach Machinery Company Private Limited · India
- Kevin Process Technologies Private Limited · India
- SPX Flow Inc. and APV (U.S.)
- Fette Compacting GmbH · Germany
- KORSCH AG · Germany
- Marchesini Group S.p.A · Italy
- Willy A. Bachofen AG · Switzerland
- BECOMIX · Germany
- UNIMIX · Germany
Frequently asked questions
The Latin America pharmaceutical manufacturing equipment market is expected to reach USD 1,933.1 million by 2036 from an estimated USD 1,068.7 million in 2026, at a CAGR of 6.1% during the forecast period 2026 to 2036.
Cite this report
Meticulous Research. (2026). Latin America Pharmaceutical Manufacturing Equipment Market - Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1854). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/latin-america-pharma-equipment-market-6537