Language Learning Market (2026-2036)
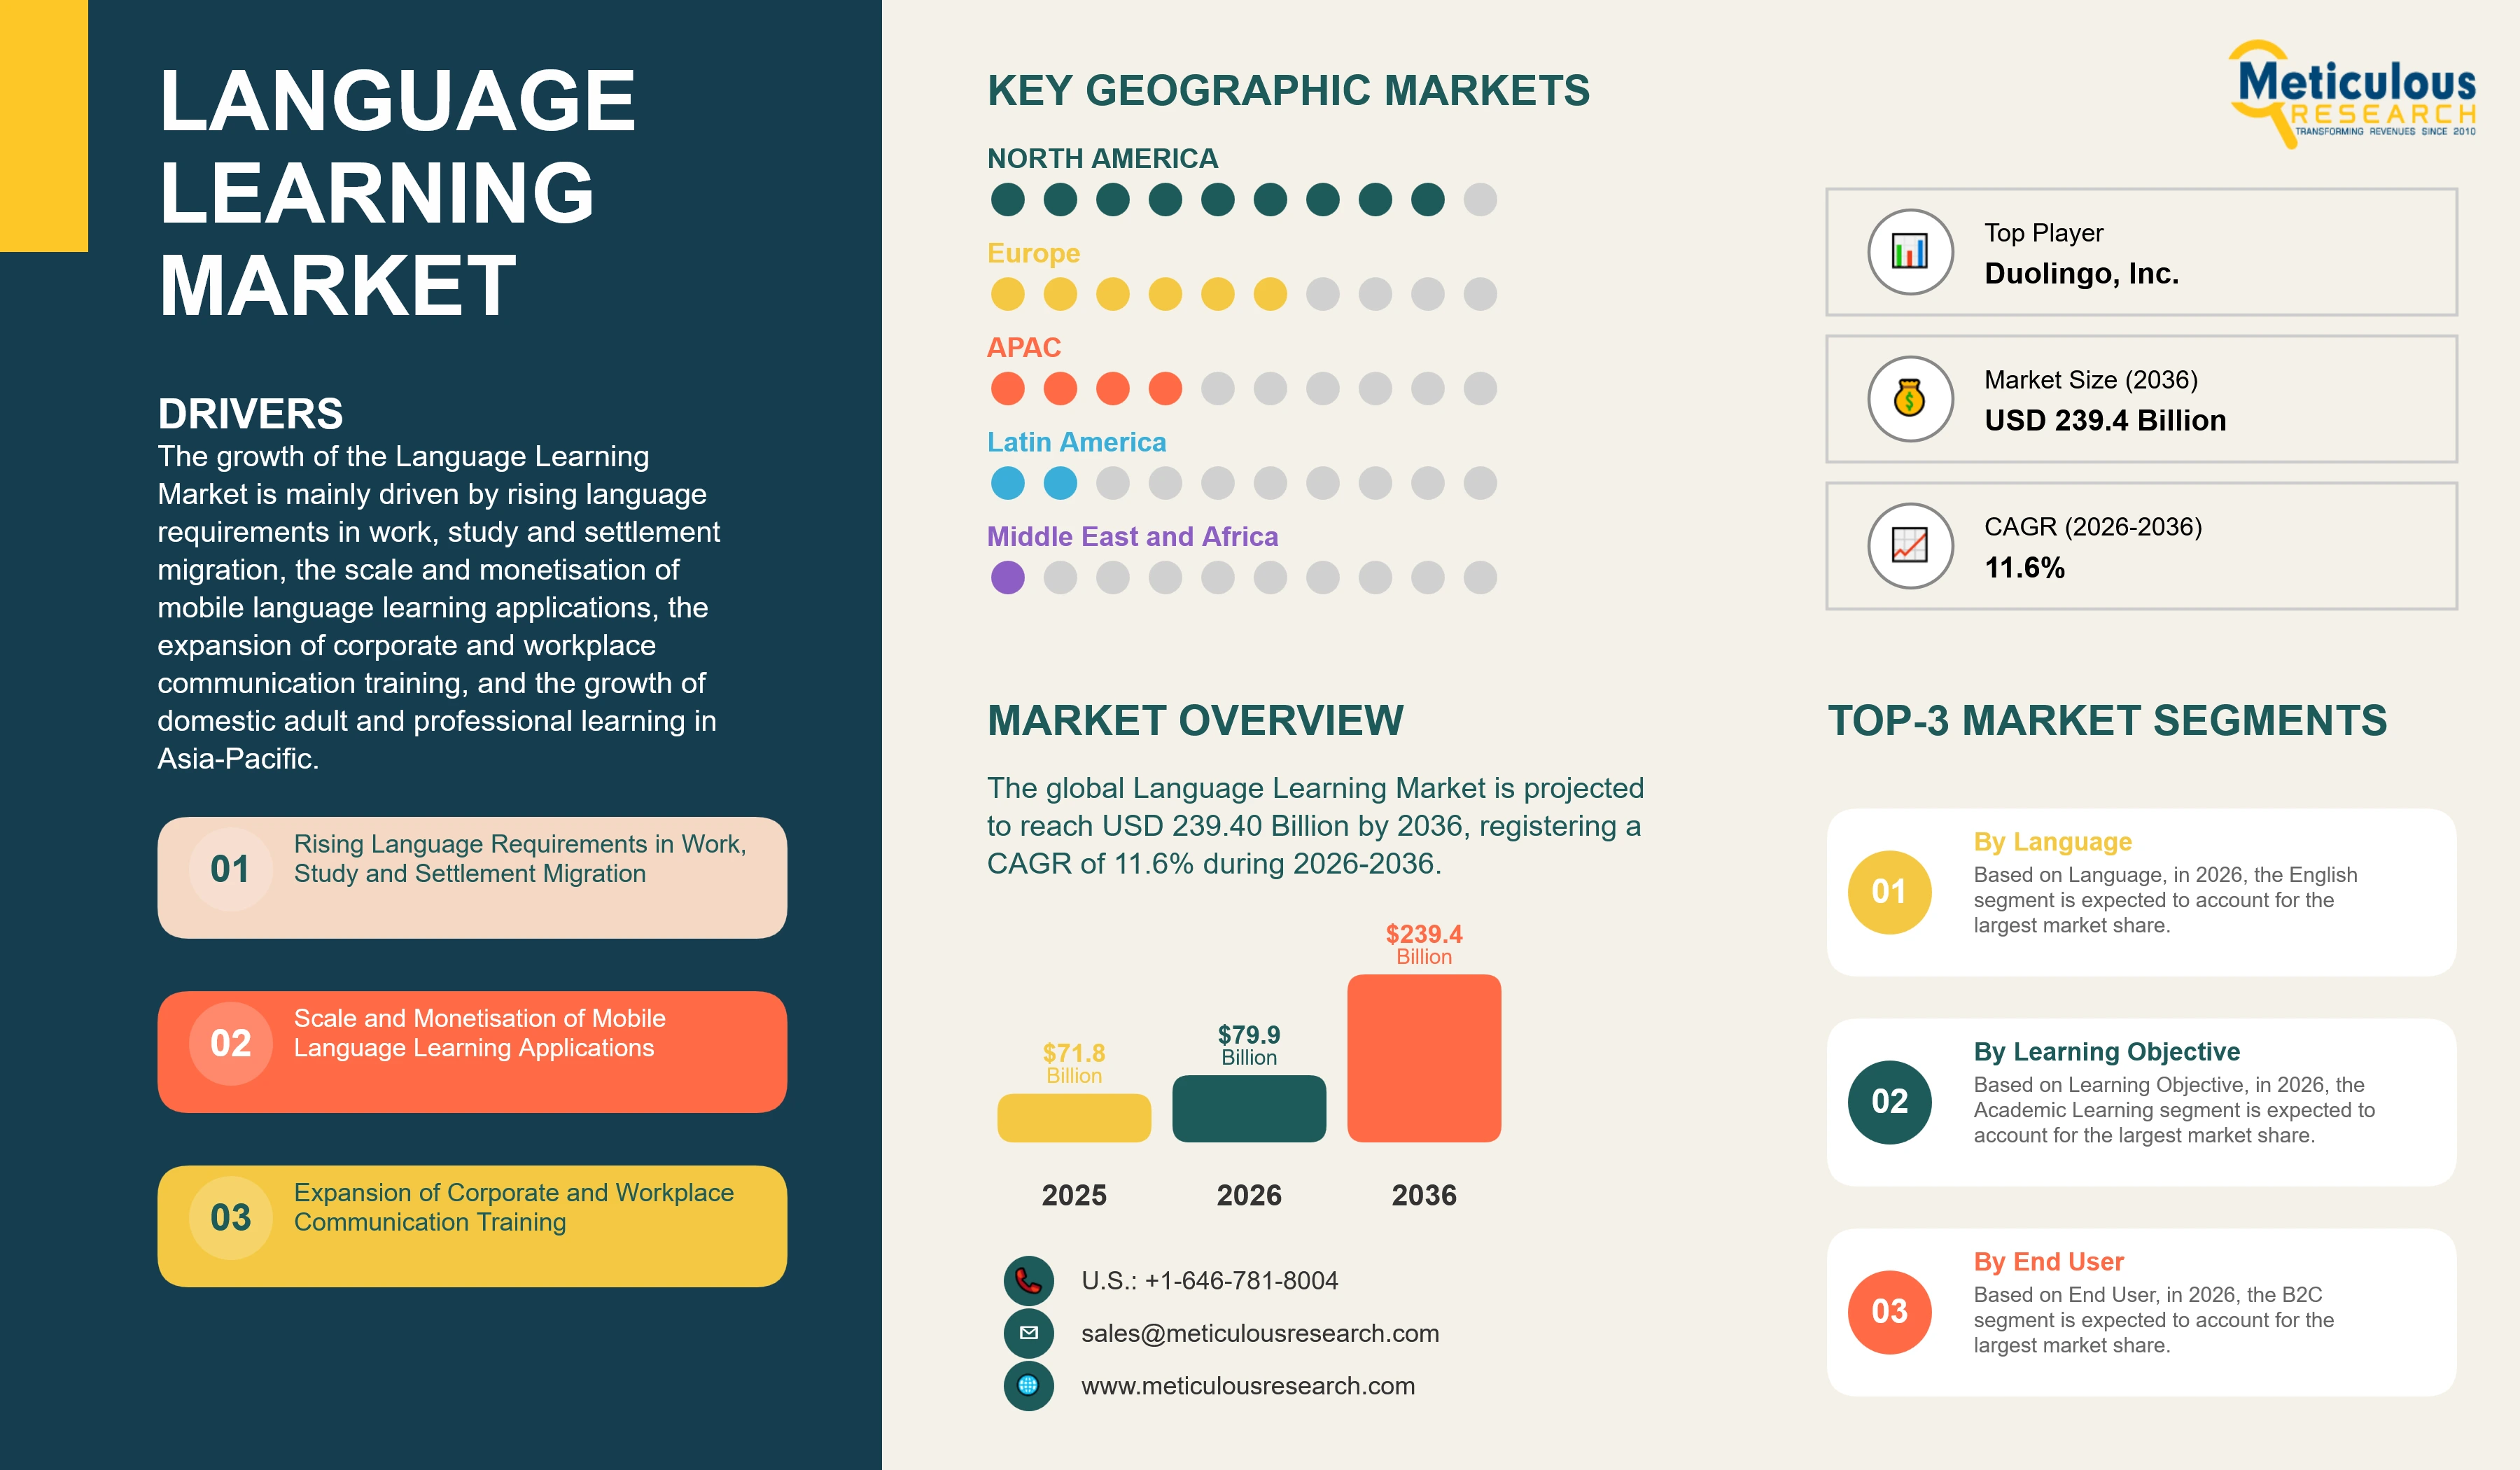
The global Language Learning Market was valued at USD 71.80 billion in 2025. This market is expected to reach USD 239.40 billion by 2036 from an estimated USD 79.90 billion in 2026, registering a CAGR of 11.6% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 410
- Format
- PDF + Excel
- Report ID
- MRICT - 104878
- Base year
- 2025
- 2025 · BASELINE
- $71.80B
- 2036
- $239.4B
- CAGR 2026–2036
- 11.6%
2025 baseline · 2026–2036 forecast at 11.6% CAGR · hover a bar for the value
Key highlights
The global Language Learning Market is projected to reach USD 239.40 billion by 2036, driven by migration-linked language requirements, mobile subscription monetisation, corporate communication training, and domestic adult learning in Asia-Pacific.
Consumer application scale continues to compound. In the second quarter of 2026, Duolingo, Inc. reported revenue of USD 298.5 million, up 18% year over year, with daily active users of 58.7 million, up 23%, monthly active users of 140.6 million, paid subscribers of 12.7 million, up 17%, and total bookings of USD 289.1 million, and guided to full-year 2026 revenue of approximately USD 1,207 million, representing growth of 16.3%.
Institutional demand is shifting toward domestic learners. In the fourth quarter of fiscal 2026, New Oriental reported revenue growth of approximately 29.1% in domestic test preparation for adults and university students, against approximately 3.6% growth in overseas test preparation and overseas study consulting, with about 1,072,000 enrollments in non-academic tutoring courses offered across approximately 60 cities.
Migration policy is raising the required proficiency level. From 8 January 2026, the U.K. raised the English language requirement for initial Skilled Worker applications from CEFR level B1 to level B2 across reading, writing, speaking and listening, and the English language requirement for settlement applications is scheduled to rise from level B1 to level B2 for applications made on or after 26 March 2027.
Asia-Pacific is expected to account for the largest market share in 2026, supported by the scale of English learning in China, India, Japan and South Korea and the size of the institutional tutoring sector, while the Middle East & Africa is projected to register the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 11.6% |
| Format | PDF, Excel & Cloud Portal · 410 pages |
| Market Size (Value) in 2026 | USD 79.90 Billion |
| Market Size (Value) in 2036 | USD 239.40 Billion |
| Segments Covered | By Age Group: Below 18 Years, 18-20 Years, 21-30 Years, 31-40 Years, Above 40 Years. By Language: English, Spanish, Mandarin, French, German, Japanese, Korean, Arabic, Italian, Portuguese, Other Languages. By Learning Objective: Academic Learning (K-12, Higher Education), Test Preparation (TOEFL, IELTS, PTE, Other Tests), Business & Workplace Communication, Travel & Cultural Immersion, Migration & Relocation. By End User: B2C (Online [One-to-One Tutoring, Group Learning, Web & Mobile Applications], Live [One-to-One Tutoring, Group Learning], Offline [One-to-One Tutoring, Group Learning]), B2B (Online [One-to-One Tutoring, Group Learning, Web & Mobile Applications], Live [One-to-One Tutoring, Group Learning], Offline [One-to-One Tutoring, Group Learning]). |
| Countries Covered | Asia-Pacific: China, Japan, India, South Korea, Indonesia, Australia & New Zealand, Taiwan, Hong Kong, Singapore, Malaysia, Vietnam, Rest of Asia-Pacific. Europe: Germany, France, Italy, U.K., Spain, Russia, Poland, Netherlands, Sweden, Belgium, Austria, Switzerland, Finland, Norway, Turkey, Ireland, Luxembourg, Rest of Europe. North America: U.S., Canada. Latin America: Brazil, Mexico, Rest of Latin America. Middle East & Africa: UAE, Saudi Arabia, Rest of Middle East & Africa. |
| Key Companies | Duolingo, Inc., Pearson plc, Cambridge University Press & Assessment, New Oriental Education & Technology Group Inc., EF Education First, Berlitz Corporation, Babbel GmbH, Chegg, Inc., IXL Learning, Preply, Inc., Memrise Inc., ELSA Corp., Mango Languages, Transparent Language, Inc., Inlingua International Ltd., Sanako Corporation, and McGraw Hill LLC. |
Report overview
Segments covered: age group, language, learning objective, end user, delivery mode.
The growth of this market is mainly driven by the rising English language requirements attached to work, study and settlement migration in destination countries; the scale and monetisation of mobile language learning applications, which are converting large free user bases into paying subscribers; the expansion of corporate and workplace communication training as organizations operate across borders; and the growth of domestic adult and professional language learning in Asia-Pacific, which is now outgrowing the study-abroad segment that historically led the market. In addition, the integration of conversational artificial intelligence into speaking and pronunciation practice, the growth of live online tutoring marketplaces, government language and employability programmes in the Middle East and Asia, and the continuing adoption of blended delivery by schools and universities are further supporting the growth of this market.
The Language Learning Market, also referred to as the language education market, language training market, or foreign language learning market, comprises the instruction, content, platforms and assessment services through which learners acquire a language other than their first. The market spans learning delivered online through web and mobile applications, delivered live through one-to-one tutoring and group classes conducted remotely, and delivered offline through classroom instruction at language schools, institutes and corporate premises. It covers academic learning in K-12 and higher education, test preparation for examinations used in admissions and immigration, business and workplace communication training, travel and cultural immersion learning, and language acquisition undertaken for migration and relocation. The market ecosystem extends from consumer application developers, tutoring marketplaces, language school networks, publishers and assessment bodies to schools, universities, employers, government agencies and the immigration authorities whose proficiency requirements shape a substantial part of demand.
The market has reorganised itself around two very different kinds of demand. On one side are consumer applications serving very large numbers of casual and self-directed learners at low prices, where the economics depend on retention and conversion rather than on price. In the second quarter of 2026, Duolingo, Inc. reported revenue of USD 298.5 million, up 18% year over year, with daily active users of 58.7 million, up 23%, monthly active users of 140.6 million, paid subscribers of 12.7 million, up 17%, and total bookings of USD 289.1 million, and guided to full-year 2026 revenue of approximately USD 1,207 million, representing growth of 16.3%. Daily active user growth of 23% against monthly active user growth of 10% indicates deepening engagement within the existing base rather than growth driven purely by new acquisition, which is the condition under which subscription conversion improves.
On the other side are institutional and high-stakes learners, where proficiency carries a consequence: admission to a university, eligibility for a visa, qualification for a role. This part of the market is served by language schools, tutoring providers, publishers and assessment bodies, and it commands far higher prices per learner because the outcome matters. For the fiscal year ended May 31, 2026, New Oriental Education & Technology Group Inc. reported total net revenues of USD 5,661.3 million, an increase of 15.5% year over year, and guided to fiscal 2027 net revenues of USD 6,453.9 million to USD 6,680.3 million, representing growth of 14% to 18%. Growth at this scale in a single national market indicates how much of global demand sits with institutional providers rather than with applications.
The composition of high-stakes demand is changing in a way that matters for providers. In the fourth quarter of fiscal 2026, New Oriental reported revenue growth of approximately 29.1% in domestic test preparation for adults and university students, against approximately 3.6% growth in overseas test preparation and overseas study consulting, with about 1,072,000 enrollments in non-academic tutoring courses offered across approximately 60 cities. Growth of 29.1% in domestic adult and university test preparation against 3.6% in overseas test preparation and study consulting shows demand moving from study-abroad preparation toward domestic qualification and employability, and providers whose capability is concentrated in overseas admissions counselling are exposed to that shift.
Immigration policy is the single most direct external influence on the market. From 8 January 2026, the U.K. raised the English language requirement for initial Skilled Worker applications from CEFR level B1 to level B2 across reading, writing, speaking and listening, and the English language requirement for settlement applications is scheduled to rise from level B1 to level B2 for applications made on or after 26 March 2027. Raising a requirement from B1 to B2 does not simply add a test; it adds months of instruction, because the gap between intermediate and upper-intermediate proficiency is not closed by test familiarisation. Each such change converts a population that previously needed a certificate into a population that needs tuition.
Policy is simultaneously contracting part of the market. According to Immigration, Refugees and Citizenship Canada, the number of study permit holders in Canada fell from 928,430 at the end of 2024 to 632,535 as at 30 June 2026, a decline of 31.9%, while the 2026 study permit cap was set at 408,000 approved permits, 7% below the 2025 target of 437,000. A decline of this magnitude in one of the largest study destinations removes a substantial volume of study-abroad test preparation and pre-departure language training, and comparable restrictions in other destinations have compounded the effect. The result is that migration policy is expanding demand for proficiency instruction among those already in or entering the labour market while contracting it among prospective international students, which is precisely the mix shift visible in institutional provider results.
Artificial intelligence has changed the product rather than the market size. Conversational practice, pronunciation assessment and adaptive review were previously constrained by the cost of human instruction, and their delivery through software has made speaking practice available at subscription prices. The commercial effect to date has been to improve engagement and retention in consumer applications rather than to displace human instruction in high-stakes preparation, where learners continue to pay for tutors, structured courses and accredited outcomes. The clearest evidence that these are distinct markets is that subscription revenue and assessment revenue at the same provider have diverged. Duolingo reported English Test revenue of USD 10.1 million in the second quarter of 2026, unchanged from the same quarter of 2025, while its subscription business grew 18%.
The market includes consumer and technology-led providers such as Duolingo, Babbel, Memrise, ELSA, Preply and Busuu under Chegg, publishers and assessment organizations including Pearson, Cambridge University Press & Assessment and McGraw Hill, international school and institute networks including EF Education First, Berlitz and Inlingua, large regional education groups including New Oriental, and specialist providers serving institutions and government including Mango Languages, Transparent Language and Sanako. Participants compete on learning outcomes and completion, recognition of certification by institutions and immigration authorities, instructor quality and availability, price and subscription value, breadth of language coverage, and the ability to serve employers and public agencies under procurement.
At the same time, the market faces challenges, including low completion and retention among self-directed learners, the difficulty of demonstrating measurable proficiency gain rather than engagement, the exposure of study-abroad linked revenue to immigration policy in a small number of destination countries, pricing pressure in the consumer application segment, and the cost and availability of qualified instructors for live delivery at scale. As a result, providers that combine credible proficiency outcomes, recognised certification, cost-efficient delivery of speaking practice, and diversified exposure across consumer, institutional and public-sector demand are expected to capture the largest share of growth over the forecast period.
Report infographic
Market dynamics
15 factors across 5 forcesRising Language Requirements in Work, Study and Settlement Migration
Rising language requirements in work, study and settlement migration is a major factor driving the Language Learning Market, as proficiency has become a condition of eligibility rather than an advantage. From 8 January 2026, the U.K. raised the English language requirement for initial Skilled Worker applications from CEFR level B1 to level B2 across reading, writing, speaking and listening, and the English language requirement for settlement applications is scheduled to rise from level B1 to level B2 for applications made on or after 26 March 2027. A requirement raised from intermediate to upper-intermediate proficiency across all four skills cannot be satisfied by test preparation alone, and it converts a certification requirement into an instruction requirement measured in months.
The effect extends across the migration pathway. Where a settlement requirement rises, it applies to individuals who are already resident and employed, which creates demand for part-time, evening and online instruction delivered around work rather than for pre-departure courses. Employers of migrant workers in sectors such as health and social care, logistics and construction are correspondingly drawn into funding or facilitating language training, which expands the business-to-business segment of the market.
Scale and Monetisation of Mobile Language Learning Applications
The scale and monetisation of mobile language learning applications is significantly driving market growth. In the second quarter of 2026, Duolingo, Inc. reported revenue of USD 298.5 million, up 18% year over year, with daily active users of 58.7 million, up 23%, monthly active users of 140.6 million, paid subscribers of 12.7 million, up 17%, and total bookings of USD 289.1 million, and guided to full-year 2026 revenue of approximately USD 1,207 million, representing growth of 16.3%. A base of 140.6 million monthly active users converting to 12.7 million paid subscribers illustrates both the reach of the category and the headroom that remains, and revenue growth of 18% against monthly active user growth of 10% shows that growth is now being driven by monetisation rather than acquisition alone.
Engagement is the mechanism. Daily active user growth of 23% against monthly active user growth of 10% indicates that users are returning more frequently, and frequency is what converts a free learner into a subscriber and what sustains a subscription once taken. Providers have therefore invested in features that increase daily return, including conversational practice, streaks and social mechanics, and the resulting improvement in retention is what supports full-year revenue growth guidance of 16.3%.
Expansion of Corporate and Workplace Communication Training
The expansion of corporate and workplace communication training is an important driver of demand and of value per learner. Organizations operating across borders require employees to work in a shared language, and the cost of miscommunication in customer-facing, technical and safety-critical roles is high enough to justify funded instruction. Corporate buyers purchase measurable outcomes, administrative reporting and cohort management rather than individual subscriptions, which supports higher prices and multi-year contracts than the consumer segment sustains.
This segment also benefits from the migration dynamic described above, because employers recruiting internationally have a direct interest in the proficiency of candidates and new joiners. Where a visa route requires upper-intermediate proficiency, the employer bears the consequence of a failed application, which makes employer-funded preparation an investment in recruitment rather than a staff benefit.
Growth of Domestic Adult and Professional Learning in Asia-Pacific
The growth of domestic adult and professional language learning in Asia-Pacific supports market growth and is reshaping its composition. In the fourth quarter of fiscal 2026, New Oriental reported revenue growth of approximately 29.1% in domestic test preparation for adults and university students, against approximately 3.6% growth in overseas test preparation and overseas study consulting, with about 1,072,000 enrollments in non-academic tutoring courses offered across approximately 60 cities. Growth of 29.1% in domestic test preparation for adults and university students demonstrates that language learning in the region is increasingly undertaken for domestic qualification, employment and professional advancement rather than for overseas study.
The scale of the regional market reinforces the effect. For the fiscal year ended May 31, 2026, New Oriental Education & Technology Group Inc. reported total net revenues of USD 5,661.3 million, an increase of 15.5% year over year, and guided to fiscal 2027 net revenues of USD 6,453.9 million to USD 6,680.3 million, representing growth of 14% to 18%. Guidance for growth of 14% to 18% in the following fiscal year, issued by a provider of this size, indicates that regional demand is expanding from a large base rather than recovering from a low one, and that the domestic segment is large enough to offset slower growth in overseas-linked services.
Table of contents
12 chapters · 196 sections · 410 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Learning Objective | Academic Learning | Migration & Relocation |
| By Language | English | English |
| By Age Group | 21-30 Years | 31-40 Years |
| By End User | B2C | B2B |
By Learning Objective
- Language Learning Market Analysis by Learning Objective
- Academic Learning is further segmented into K-12 and Higher Education, while Test Preparation is further segmented into TOEFL, IELTS, PTE, and Other Tests.
- The Academic Learning segment is expected to account for the largest share of the global Language Learning Market.
- The large share of this segment is mainly due to the inclusion of foreign language instruction in school and higher education curricula across most national education systems, the scale of institutional and government procurement of language programmes and materials, and the volume of learners served through formal education relative to any discretionary channel.
- However, the Migration & Relocation segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the raising of English language requirements for work visas and settlement in major destination countries, including the increase in the U.K. requirement for initial Skilled Worker applications from CEFR level B1 to level B2 from 8 January 2026, and the conversion of certification requirements into sustained instruction demand among resident and working populations.
By Language
- Language Learning Market Analysis by Language
- The English segment is expected to account for the largest share of the market and is also projected to register one of the highest growth rates during the forecast period.
- The large share and continued growth of this segment are mainly due to the position of English as the language specified in work, study and settlement requirements across the principal migration destinations, its status as the working language of multinational employers, its inclusion in school curricula across most of Asia, Europe, Latin America and the Middle East, and the concentration of high-stakes assessment volume in English.
- Spanish, Korean and Japanese are projected to register the highest growth rates.
- The growth of Spanish is attributed to its scale in school curricula and its use across the Americas, while the growth of Korean and Japanese is attributed to cultural and media-driven demand among younger learners and to labour mobility into both countries, where language proficiency is a condition of several employment and residency pathways.
By Age Group
- Language Learning Market Analysis by Age Group
- The 21-30 Years segment is expected to account for the largest share of the market.
- The large share of this segment is mainly due to the concentration of migration, employment and higher education decisions in this age band, the willingness of learners in this group to pay for instruction with a defined professional or mobility outcome, and the high rate of adoption of mobile and online learning among this cohort.
- However, the 31-40 Years segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the raising of language requirements for settlement and skilled employment, which affect established workers rather than new entrants, to employer-funded workplace communication training delivered to mid-career employees, and to relocation undertaken with families.
By End User
- Language Learning Market Analysis by End User and Delivery Mode
- Each is further segmented by delivery mode into Online, Live, and Offline.
- Online is further segmented into One-to-One Tutoring, Group Learning, and Web & Mobile Applications; Live is further segmented into One-to-One Tutoring and Group Learning; and Offline is further segmented into One-to-One Tutoring and Group Learning.
- The B2C segment is expected to account for the largest share of the global Language Learning Market.
- The large share of this segment is mainly due to the volume of individual learners purchasing subscriptions, courses and tutoring directly, demonstrated by paid subscribers of 12.7 million at a single application provider in the second quarter of 2026, and the breadth of discretionary learning undertaken for travel, culture and personal interest.
- However, the B2B segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to employer-funded workplace communication training, the drawing of employers into language provision by visa proficiency requirements for internationally recruited staff, and government and institutional procurement of language and employability programmes.
- Within delivery modes, Online Web & Mobile Applications are expected to account for the largest share, while Online One-to-One Tutoring is projected to grow fastest, reflecting the premium learners place on speaking practice with an instructor.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Language Learning Market. The large share of this region is mainly attributed to the scale of English learning in China, India, Japan, South Korea and Southeast Asia, the size of the institutional tutoring and test preparation sector, the inclusion of English in national curricula and public examinations, and outbound labour mobility from the region. For the fiscal year ended May 31, 2026, New Oriental Education & Technology Group Inc. reported total net revenues of USD 5,661.3 million, an increase of 15.5% year over year, and guided to fiscal 2027 net revenues of USD 6,453.9 million to USD 6,680.3 million, representing growth of 14% to 18%. In the fourth quarter of fiscal 2026, New Oriental reported revenue growth of approximately 29.1% in domestic test preparation for adults and university students, against approximately 3.6% growth in overseas test preparation and overseas study consulting, with about 1,072,000 enrollments in non-academic tutoring courses offered across approximately 60 cities.
Europe
Europe is expected to account for a significant share of the market, supported by the multilingual character of the region, the inclusion of two or more foreign languages in many national curricula, the use of the Common European Framework of Reference as the basis for both instruction and policy, and intra-regional labour mobility. Migration policy in the region is a direct influence on demand. From 8 January 2026, the U.K. raised the English language requirement for initial Skilled Worker applications from CEFR level B1 to level B2 across reading, writing, speaking and listening, and the English language requirement for settlement applications is scheduled to rise from level B1 to level B2 for applications made on or after 26 March 2027.
North America
North America is expected to account for a substantial share of the market, supported by Spanish instruction in schools and universities, English instruction for immigrant and English-learner populations, corporate communication training, and the concentration of leading consumer application providers in the region. In the second quarter of 2026, Duolingo, Inc. reported revenue of USD 298.5 million, up 18% year over year, with daily active users of 58.7 million, up 23%, monthly active users of 140.6 million, paid subscribers of 12.7 million, up 17%, and total bookings of USD 289.1 million, and guided to full-year 2026 revenue of approximately USD 1,207 million, representing growth of 16.3%.
Middle East & Africa
Fastest growthThe Middle East & Africa is projected to register the highest CAGR during the forecast period. The growth of this region is driven by national economic diversification and workforce development programmes in Saudi Arabia and the United Arab Emirates that include English proficiency as a component of employability, the scale of the expatriate workforce in the Gulf, the expansion of English-medium education, and population growth and school enrolment expansion across Africa.
Latin America
Latin America is expected to grow steadily, supported by English instruction for employability in services and technology sectors and by the scale of school-based language provision.
Competitive landscape
The global Language Learning Market is fragmented, with consumer application providers, tutoring marketplaces, international school and institute networks, publishers and assessment organizations, and large regional education groups each holding leading positions in different parts of the market and competing only partially with one another. Market participants compete on learning outcomes and completion, recognition of certification by institutions and immigration authorities, instructor quality and availability, price and subscription value, breadth of language coverage, and the ability to serve employers and public agencies under procurement.
Leading companies are integrating conversational artificial intelligence into speaking and pronunciation practice, adding live instruction to subscription products and structured self-study to tutoring offerings, building occupational and sector-specific content for employer-funded training, pursuing institutional and government procurement, and strengthening certification recognised by immigration authorities and employers. Recent market context includes revenue growth of 18% and daily active user growth of 23% at Duolingo in the second quarter of 2026 alongside a decline in adjusted EBITDA margin from 31.2% to 25.9% as the company invested in user growth, and revenue growth of 15.5% for the fiscal year ended May 2026 at New Oriental with guidance for a further 14% to 18%.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Language Learning Market. The key players profiled in the report include Duolingo, Inc. (U.S.), Pearson plc (U.K.), Cambridge University Press & Assessment (U.K.), New Oriental Education & Technology Group Inc. (China), EF Education First (Switzerland), Berlitz Corporation (U.S.), Babbel GmbH (Germany), Chegg, Inc. (U.S.), IXL Learning (U.S.), Preply, Inc. (U.S.), Memrise Inc. (U.K.), ELSA Corp. (U.S.), Mango Languages (U.S.), Transparent Language, Inc. (U.S.), Inlingua International Ltd. (Switzerland), Sanako Corporation (Finland), and McGraw Hill LLC (U.S.).
- Duolingo, Inc.
- Pearson plc
- Cambridge University Press & Assessment
- New Oriental Education & Technology Group Inc.
- EF Education First
- Berlitz Corporation
- Babbel GmbH
- Chegg, Inc.
- IXL Learning
- Preply, Inc.
- Memrise Inc.
- ELSA Corp.
- Mango Languages
- Transparent Language, Inc.
- Inlingua International Ltd.
- Sanako Corporation
- McGraw Hill LLC
Expert perspectives
The Language Learning Market is no longer a single market with a single growth rate. Consumer applications are growing on monetisation of very large installed bases, with revenue up 18% against monthly active users up 10% at the largest provider, while institutional demand is growing on a different mechanism entirely, with 29.1% growth in domestic adult test preparation against 3.6% in overseas test preparation at a leading regional group. The binding constraint is shifting from access to instruction to evidence of proficiency, because policy, employers and institutions now specify a CEFR level rather than a course, and a provider that cannot demonstrate movement between levels is excluded from the part of the market where price is not the deciding factor.
Three structural changes are expected to shape competitive positions through 2036. First, migration policy is expected to remain the strongest single driver, and because requirements are rising to upper-intermediate proficiency, the demand created is for months of instruction rather than for test familiarisation. Second, the shift of test preparation from overseas admissions to domestic qualification is expected to continue, favouring providers with domestic delivery networks over those built around international admissions counselling. Third, conversational artificial intelligence is expected to continue improving engagement and retention in consumer products without displacing paid human instruction in high-stakes preparation, which means the two halves of the market will converge on blended models rather than one absorbing the other.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in migration and settlement proficiency instruction tied to recognised certification, occupational language training sold to employers of internationally recruited workforces, government language and employability programmes in the Gulf and Asia, blended products combining application practice with live instruction, and assessment and certification recognised by immigration authorities. For established providers, the principal priorities are demonstrating proficiency gain rather than engagement, diversifying away from single-destination study-abroad exposure, and sustaining engagement investment without permanently compressing margins.
Overall, the market is expected to grow strongly, with academic learning, English, learners aged 21 to 30, business-to-consumer online delivery and Asia-Pacific providing the core of demand, and migration and relocation learning, learners aged 31 to 40, business-to-business delivery, online one-to-one tutoring and the Middle East & Africa providing the fastest growth.
Customer perspectives
Insights gathered during primary interviews with corporate learning leaders, language school operators, and migration-focused training providers highlight where priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects proficiency gain rather than engagement as the purchasing basis.”
“This indicates the shift from study-abroad to resident learner demand.”
“This points to raised requirements creating instruction demand.”
Frequently asked questions
The global Language Learning Market is estimated at USD 79.90 billion in 2026.
Cite this report
Meticulous Research. (2026). Language Learning Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRICT - 104878). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/language-learning-market-5561