Hyperscale Data Centers Market (2026-2036)
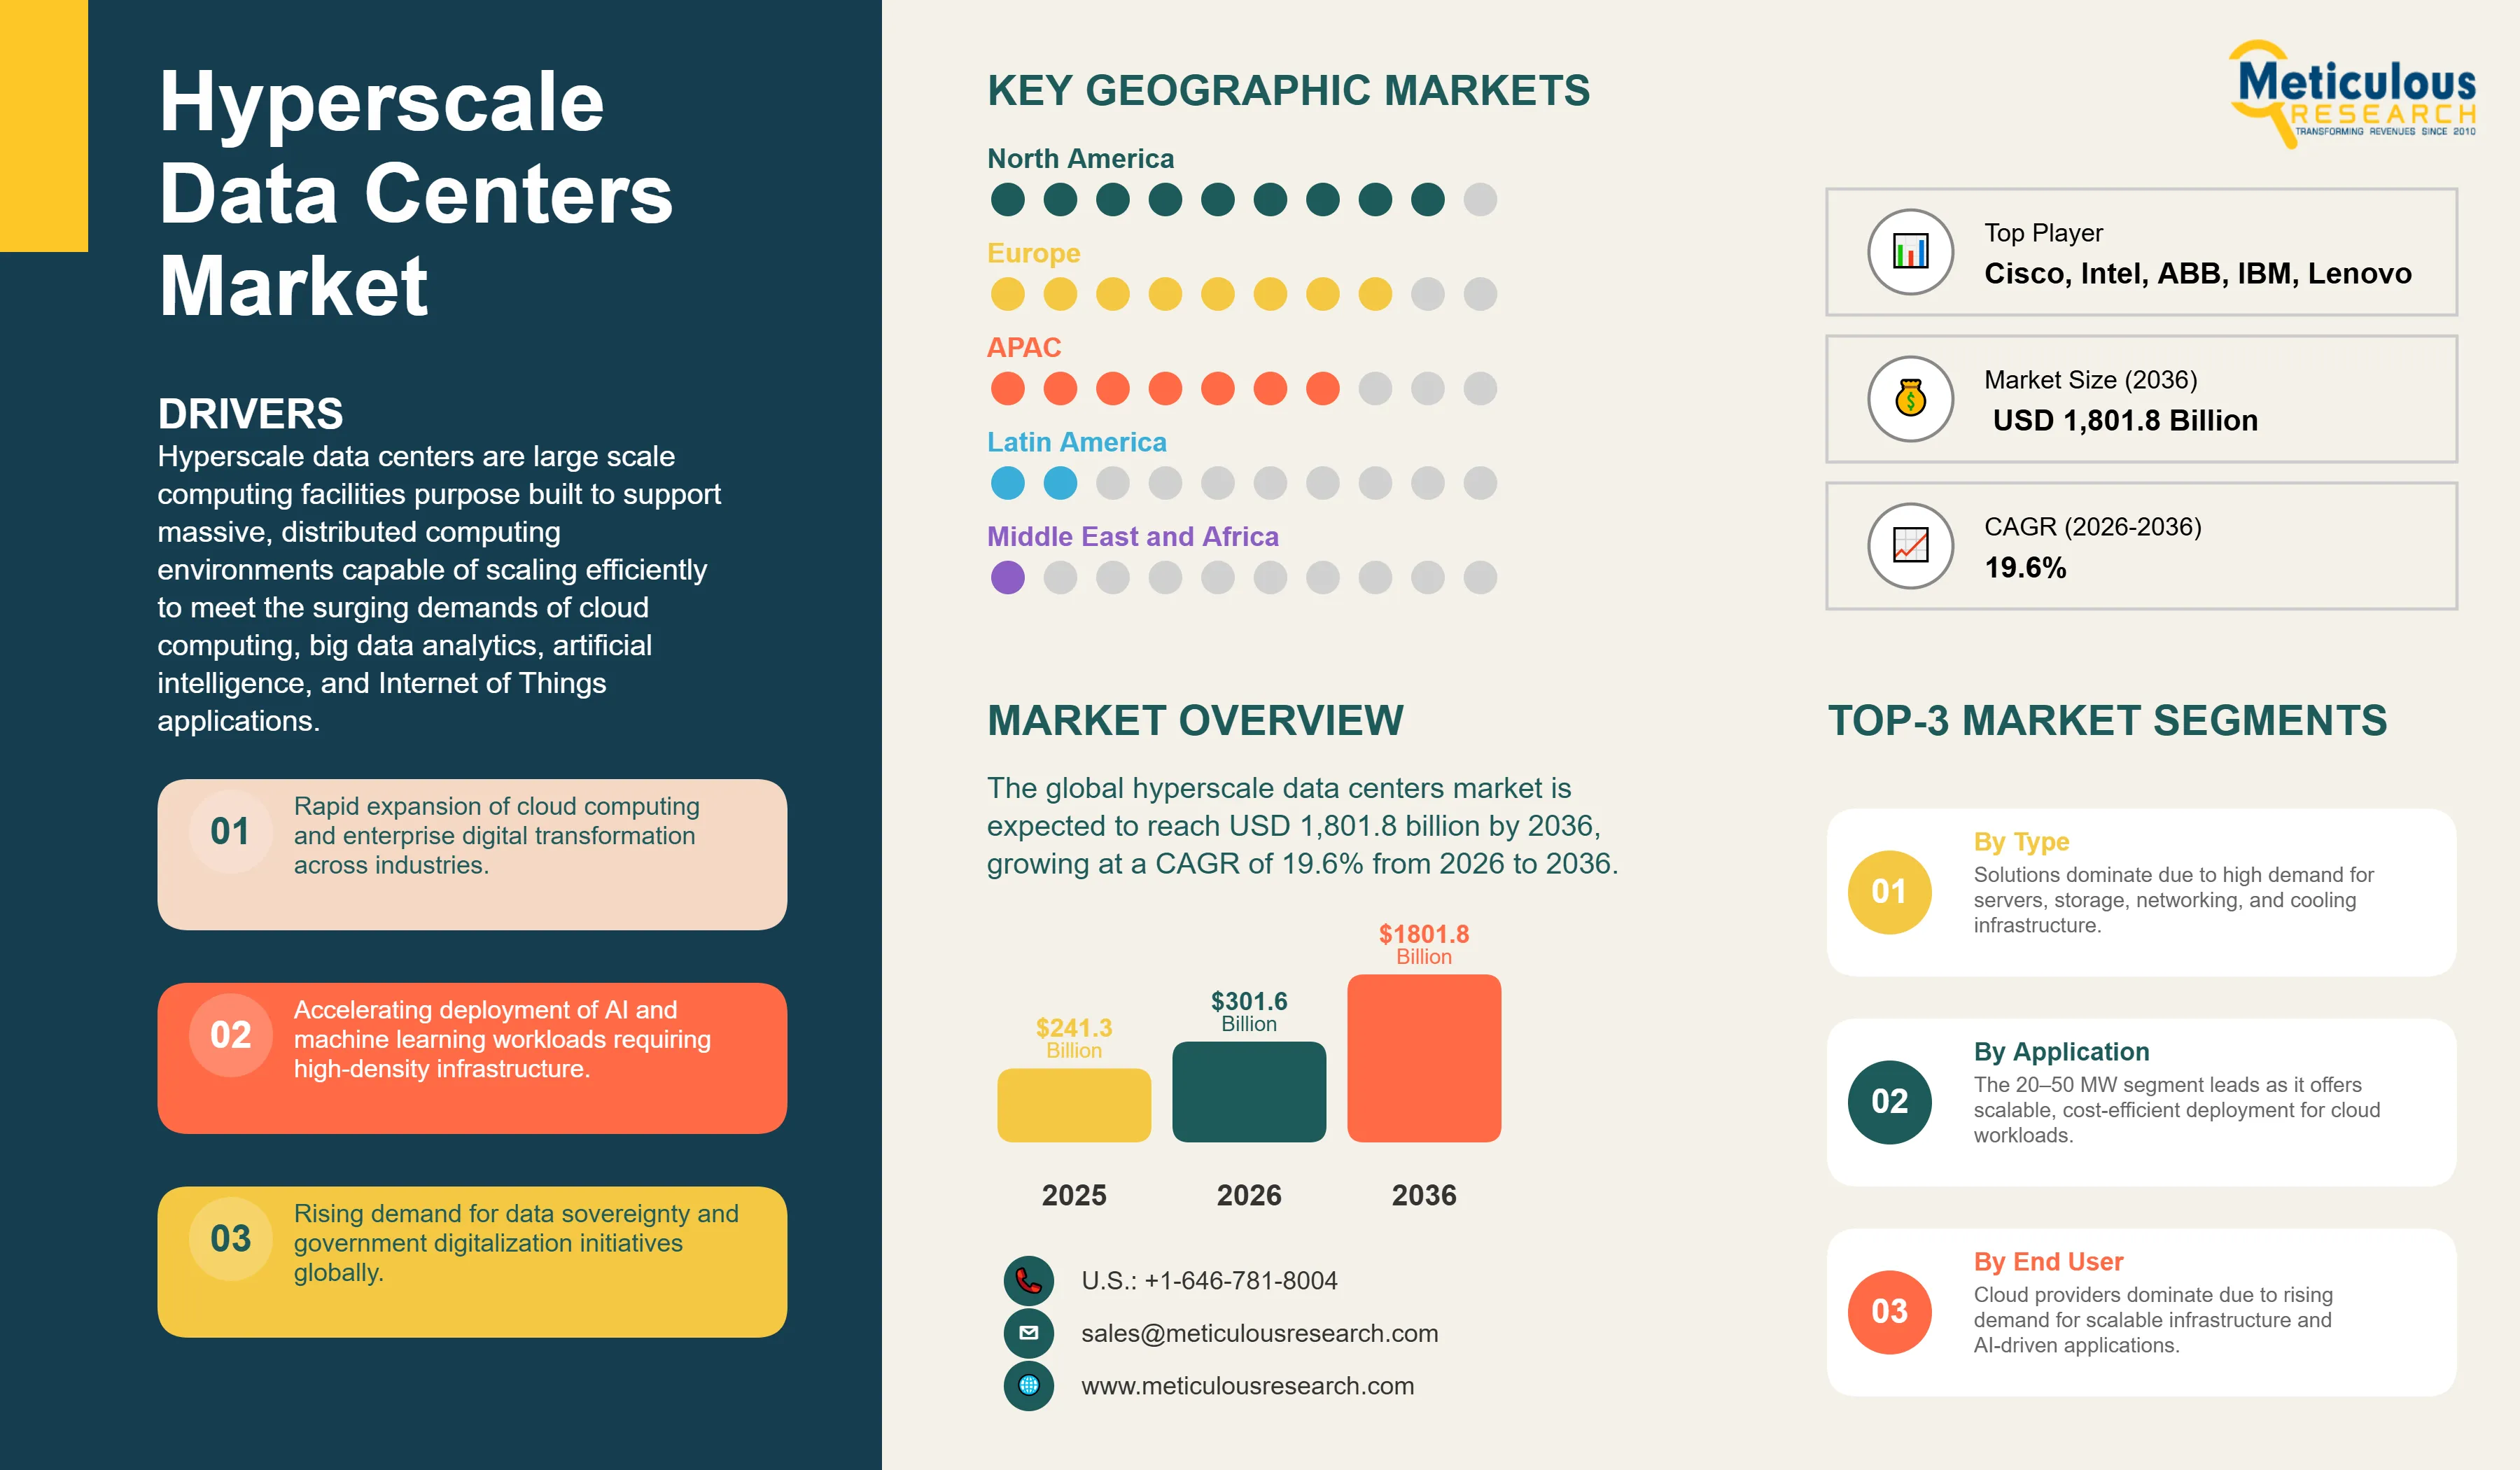
The global hyperscale data centers market was valued at USD 241.3 billion in 2025. This market is expected to reach USD 1,801.8 billion by 2036 from USD 301.6 billion in 2026, growing at a CAGR of 19.6% from 2026 to 2036.
- Published
- Mar 2026
- Pages
- 399
- Format
- PDF + Excel
- Report ID
- MR-1714
- Base year
- 2025
- 2025 · BASELINE
- $241.3B
- 2036
- $1.80T
- CAGR 2026–2036
- 19.6%
2025 baseline · 2026–2036 forecast at 19.6% CAGR · hover a bar for the value
Key highlights
By Component: The Solutions Segment to Dominate the Hyperscale Data Centers Market in 2026
By Power Capacity: The 20 MW–50 MW Segment to Dominate the Hyperscale Data Centers Market in 2026
By End User: The Cloud Providers Segment to Dominate the Hyperscale Data Centers Market in 2026
By Geography: North America Dominates the Hyperscale Data Centers Market in 2026
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026–2036 |
| Base Year | 2025 |
| CAGR (Value) | 19.6% |
| Format | PDF, Excel & Cloud Portal · 399 pages |
| Market Size (Value) in 2026 | USD 301.6 Billion |
| Market Size (Value) in 2036 | USD 1,801.8 Billion |
| Segments Covered | By Component: Solutions, Services; By Power Capacity: 20 MW–50 MW, 50 MW–100 MW, 100 MW–150 MW, 150 MW and Above; By End User: Cloud Providers, Colocation Providers, Technology Providers, Enterprises |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, and Rest of Europe), Asia-Pacific (China, India, Japan, South Korea, Australia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, Argentina, and Rest of Latin America), and the Middle East & Africa (Saudi Arabia, South Africa, UAE) |
| Key Companies | NVIDIA Corporation (U.S.), Cisco Systems, Inc. (U.S.), Intel Corporation (U.S.), Lenovo (China/U.S.), Eaton (Ireland), ABB Ltd. (Switzerland), Rittal GmbH & Co. KG (Germany), IBM Corporation (U.S.), Microsoft Corporation (U.S.), VMware, Inc. (U.S.), Nutanix, Inc. (U.S.), Dell Technologies Inc. (U.S.), Super Micro Computer/Supermicro (U.S.), Schneider Electric SE (France), Vertiv Holdings Co. (U.S.), Huawei Technologies Co., Ltd. (China), Hewlett Packard Enterprise (U.S.), Arista Networks, Inc. (U.S.), NTT DATA Corporation (Japan), Accenture plc (Ireland), and Kyndryl Holdings, Inc. (U.S.) |
Market dynamics
8 factors across 2 forcesRapid Expansion of Cloud Computing and Enterprise Digital Transformation
Increasing adoption of cloud computing remains the key driver of the growth of the hyperscale data center market. As enterprises across banking, telecommunications, healthcare, and manufacturing increasingly rely on cloud-native applications, multi-cloud strategies, and hybrid architectures, the need for large-scale, highly available, and geographically distributed infrastructure continues to grow.
Global public cloud spending reached around USD 679 billion in 2024 and is projected to reach nearly USD 723 billion in 2025, indicating a steady shift in enterprise IT spending toward cloud-based services. The three leading cloud providers, such as Amazon Web Services, Microsoft Azure, and Google Cloud, together account for about 58% of global hyperscale data center capacity and continue to expand their infrastructure to meet rising demand.
The enterprise segment is expected to dominate the hyperscale data center market. Organizations in regulated and capital-intensive industries are increasingly adopting hyperscale environments to modernize legacy systems, improve operational agility, and strengthen cybersecurity. Multi-cloud strategies are now standard among large enterprises, driving sustained demand for both colocation facilities and cloud provider infrastructure.
Accelerating Deployment of AI and Machine Learning Workloads
The rapid deployment of artificial intelligence (AI) and machine learning (ML) workloads is another factor driving the growth of the overall hyperscale data center market. The growing use of large language models, generative AI, deep learning, and high-performance computing is significantly increasing requirements for compute density, power capacity, and advanced cooling systems compared to traditional cloud workloads. This shift is reshaping data center design and accelerating investments in hyperscale data center infrastructure. Major strategic initiatives further drive this momentum. The Stargate Project, backed by OpenAI, Oracle, and SoftBank, deployed initial capacity at its Abilene, Texas site, in September 2025 and targets up to USD 500 billion in total investment across 10 GW of capacity over four years globally. Meanwhile, Microsoft has committed around USD 80 billion toward AI-enabled data center capacity in FY2025 alone.
According to the International Energy Agency, global electricity consumption from accelerated servers, primarily driven by AI workloads, is projected to grow at around 30% annually under the base case scenario. These workloads are expected to account for nearly half of the total increase in global data center electricity consumption through 2030.
Growing Demand for Data Sovereignty and Government Digitalization
Data sovereignty regulations have become another key driver of the growth of the hyperscale data center market. Governments across major markets, such as the European Union under GDPR, India through the Digital Personal Data Protection Act (2023), and China under the Data Security Law (2021), are increasingly requiring that citizen and public sector data be stored and processed within national or regional boundaries. Similar regulatory trends are emerging across Southeast Asia, the Middle East, and Latin America. As a result, global cloud providers are expanding into new national markets by building localized cloud regions, accelerating hyperscale deployment beyond traditional hubs such as North America and Western Europe.
At the same time, large-scale government digitalization initiatives are reinforcing demand for sovereign cloud infrastructure. In the GCC region, Saudi Arabia’s Vision 2030 and the UAE’s national AI strategy are driving significant investments in regional data center capacity by companies such as Microsoft, Google, and Oracle. In Europe, initiatives such as GAIA-X and various national cloud programs are driving the development of infrastructure aligned with regional data protection standards.
As data sovereignty requirements become more stringent and enforcement strengthens, demand for compliant, geographically distributed hyperscale infrastructure is expected to increase significantly over the forecast period.
Expansion of 5G Infrastructure and Edge Cloud Integration
The global rollout of 5G networks is enabling a new wave of latency-sensitive applications, such as autonomous vehicles, smart cities, industrial IoT, remote healthcare, and augmented reality. These use cases are driving demand for both edge infrastructure and centralized hyperscale data centers.
The number of connected IoT devices reached around 17 billion in 2024 and is expected to reach 29 billion by 2030, significantly increasing data generation and processing requirements. This increase in data is driving the need for large-scale storage, computing, and AI-based analytics, most of which are supported by hyperscale facilities.
AI models are typically trained in hyperscale data centers using aggregated data from IoT and 5G networks, and then deployed at the edge for real-time processing. This model indicates the importance of hyperscale infrastructure, even as edge computing continues to expand.
In addition, the growing adoption of private 5G networks across manufacturing, logistics, and industrial sectors is driving demand for colocation and hyperscale infrastructure capable of supporting mission-critical operations.
Table of contents
11 chapters · 232 sections · 399 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Solutions | Services |
| By Power Capacity | 20 MW–50 MW | 150 MW and above |
| By End User | Cloud Providers | Colocation providers |
By Component
- The Solutions Segment to Dominate the Hyperscale Data Centers Market in 2026
- The solutions segment is expected to account for the largest share, primarily due to the high capital investment required for core infrastructure.
- This includes IT hardware such as servers, storage, and networking equipment, along with facility infrastructure like power and cooling systems, as well as software platforms that enable data center operations.
- The continued expansion of cloud infrastructure and the rapid adoption of AI-driven workloads are driving strong demand for high-performance servers, advanced cooling technologies, and scalable architectures.
- As a result, solutions spending is expected to remain the dominant revenue contributor throughout the forecast period.
- However, the services segment is projected to register the fastest growth rate from 2026 to 2036.
- This growth is driven by the increasing complexity of hyperscale environments and the rising need for specialized capabilities in design, deployment, and operations.
- Demand for maintenance, support, and managed services is also increasing as operators expand across regions and adopt advanced technologies such as AI and liquid cooling.
By Power Capacity
- The 20 MW–50 MW Segment to Dominate the Hyperscale Data Centers Market in 2026
- The 20 MW–50 MW segment is expected to hold the largest market share, driven by its balance of scalability, cost efficiency, and deployment flexibility.
- This capacity range is widely preferred by hyperscale operators as it supports phased expansion while allowing better control over power availability and capital investment.
- It also aligns well with current enterprise cloud and digital workload requirements, making it the most practical and widely adopted deployment size.
- However, the 150 MW and above segment is projected to register the fastest CAGR during the forecast period.
- This growth is driven by rising demand for large-scale AI and high-performance computing workloads, which require significantly higher power capacity and dense infrastructure.
- To support these needs, hyperscale operators are increasingly investing in mega-campus developments designed for GPU clusters, generative AI training, and large-scale data processing.
- Economies of scale and long-term capacity planning are further encouraging the development of ultra-large facilities.
By End User
- The Cloud Providers Segment to Dominate the Hyperscale Data Centers Market in 2026
- The cloud providers segment is expected to account for the largest market share, driven by the continuous expansion of cloud infrastructure to meet rising demand for public, private, and hybrid cloud services.
- Growing enterprise dependence on cloud platforms, increasing data volumes, and the need for scalable, on-demand computing resources are key factors supporting this dominance.
- In addition, the rapid deployment of AI and data-intensive applications on cloud platforms is further strengthening the position of cloud providers as the primary users of hyperscale infrastructure.
- However, the colocation providers segment is expected to register the fastest CAGR from 2026 to 2036.
- Colocation enables faster market entry without significant upfront capital investment, making it an attractive option, mainly in emerging markets and for hybrid cloud strategies.
- Hyperscale operators are also increasingly partnering with colocation providers to expand into new regions more quickly, further driving the growth of this segment.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global hyperscale data centers market. The growth of the hyperscale data center market in North America is mainly driven by the strong presence of leading hyperscale operators, high adoption of cloud computing, early deployment of AI and advanced digital technologies, and continuous investments in large-scale data center campuses, mainly across the U.S. The concentration of major technology companies and the ongoing expansion of AI-driven infrastructure further drive the growth of this market. North America Dominates the Hyperscale Data Centers Market in 2026
Asia-Pacific
Fastest growthHowever, the Asia-Pacific region is expected to register the highest growth rate during the forecast period. The rapid growth of the hyperscale data center market in Asia-Pacific is driven by increasing internet penetration, rising cloud adoption, and strong government initiatives supporting digital transformation across China, India, and Southeast Asian nations. Growing demand for data localization, expansion of 5G networks, and increasing investments by global hyperscalers in emerging markets are further driving data center development across the region. As digital economies continue to expand and enterprise cloud adoption deepens, Asia-Pacific is positioned to emerge as the fastest-growing market for hyperscale data centers over the forecast period.
Competitive landscape
- NVIDIA Corporation (U.S.)
- Cisco Systems, Inc. (U.S.)
- Intel Corporation (U.S.)
- Lenovo (China/U.S.)
- Eaton · Ireland
- ABB Ltd. · Switzerland
- Rittal GmbH & Co. KG · Germany
- IBM Corporation (U.S.)
- Microsoft Corporation (U.S.)
- VMware, Inc. (U.S.)
- Nutanix, Inc. (U.S.)
- Dell Technologies Inc. (U.S.)
- Super Micro Computer/Supermicro (U.S.)
- Schneider Electric SE · France
- Vertiv Holdings Co. (U.S.)
- Huawei Technologies Co., Ltd. · China
- Hewlett Packard Enterprise (U.S.)
- Arista Networks, Inc. (U.S.)
- NTT DATA Corporation · Japan
- Accenture plc · Ireland
- Kyndryl Holdings, Inc. (U.S.)
Frequently asked questions
The global hyperscale data centers market is estimated at USD 301.6 billion in 2026.
Cite this report
Meticulous Research. (2026). Hyperscale Data Centers Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1714). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/hyperscale-data-centers-market-6397