Optical Transceivers Market (2023-2030)
is expected to reach $5.31 billion by 2030, at a CAGR of 12.4% during the forecast period of 2023 to 2030. Based on volume, the optical transceiver market is projected to reach 42,923 thousand units by 2030, at a CAGR of 13.1% during the forecast period.
- Published
- Feb 2023
- Pages
- 403
- Format
- PDF + Excel
- Report ID
- MR-775
- Base year
- 2022
- 2030 · FORECAST
- $5.31B
- 2030
- $5.31B
- CAGR 2023–2030
- 12.4%
2022 baseline · 2023–2030 forecast at 12.4% CAGR · hover a bar for the value
Key highlights
In terms of value, in 2023, the QSFP, QSFP+, QSFP-DD, and QSFP28 Segment is Expected to Dominate the Optical Transceivers Market
In terms of value, in 2023, the Single Mode Fiber Segment is Expected to Dominate the Optical Transceiver Market
In terms of value, in 2023, the Data Centers Segment is Expected to Dominate the Optical Transceiver Market
Asia-Pacific to be the Fastest-growing Regional Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2022 |
| Estimated Year | 2023 |
| Forecast Period | 2023–2030 |
| Market Size (2030) | USD 5.31 billion |
| CAGR (2023–2030) | 12.4% |
| Format | PDF, Excel & Cloud Portal · 403 pages |
| Segments Covered | By Form Factor: QSFP, QSFP+, QSFP-DD, and QSFP28, SFP, SFP+ and SFP28, CFP, CFP2, and CFP4, XFP (10 Gigabit Small Form Factor Pluggable), CXP, SFF (Small Form Factor) · By Type: Single Mode Fiber, Multimode Fiber · By Wavelength: Long-range, Extended-range, Short-range, Other Wavelengths · By Protocol: Ethernet, FTTx (Fiber to the x), Fiber Channel, Other Protocols · By Distance: Less than 550m, 551m to 20 km, 21 Km to 50 km, 51 Km to 120 km, More than 120km · By Application: Data Centers Data Center Interconnects, Intra-data Center Connections, Ultra-long-haul Networks, Long-haul Networks, Metro Networks · By Data Rate |
| Countries Covered | North America (Canada), Europe (Germany, U.K., France, Italy, Spain, Netherlands, Denmark, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea) |
| Key Companies | Hisense Broadband, Inc., Huawei Technologies Co., Ltd., Juniper Networks, Inc., HG Genuine Co., Ltd., Eoptolink Technology Inc., Accelink Technologies Co., Ltd., Broadcom Inc., Coherent Corp., Sumitomo Electric Industries, Ltd., SUHNER AG, Luxshare Precision Industry Co., Ltd., Acacia Communications, Inc., Fujitsu Optical Components Co., Ltd., Intel Corporation |
Report overview
Segments covered: form factor, type, wavelength, protocol, distance, application, data rate. Regions: North America, Europe, Asia-Pacific.
The growth of this market is mainly driven by the factors such as the growing adoption of optical modules among data centers and the rising need for optical transceivers for extended wavelengths over long distances. However, government regulations and certifications restrain the growth of this market.
The growing adoption of 5G and cloud technologies in emerging countries and the increasing demand for high-speed internet and data-intensive applications are expected to create market growth opportunities. However, the lack of standardization is a major challenge for the players operating in this market.
The COVID-19 pandemic impacted the worldwide economy. The lockdowns and restrictions on international trade and travel disrupted global supply chains. Workforce and raw material shortages further intensified the situation. Governments forced the closure of manufacturing plants and halted all import-export activities. As a result, several industries, including the optical transceivers industry, witnessed a decline in production. However, the increasing investments in advancing optical modules, developments in 5g technology, and the deployment of hyperscale data centers boosted the demand for optical transceivers in some regions. The shift to remote work and online learning increased the use of internet-based communication and data transfer. Furthermore, the pandemic accelerated digitalization across various industries, driving the demand for high-speed and reliable communication infrastructure. These factors supported the demand for optical transceiver devices, which are an essential component of such infrastructures.
Growth in data-intensive applications such as cloud computing, big data, and the Internet of Things (IoT) and the need for higher bandwidth and longer distance communication supported the growth of the optical transceivers market during the COVID-19 pandemic. Technology companies were focused on developing cost-effective, flexible, and advanced optical transceiver solutions to expand their product offerings and increase their market shares. For instance, in April 2020, HUBER+SUHNER AG (Switzerland) launched the outdoor fiber optic connector Q-ODC-2 Mini to enable cost-effective, flexible, and higher-capacity deployments of wireless infrastructure for industrial and communication applications. Similarly, in February 2020, Huawei Technologies Co., Ltd. (China) launched the 800G tunable ultra-high-speed optical module to help operators cope with the bandwidth challenges of 5G networks and help improve the transmission performance of optical networks. Thus, such developments, along with the growth in remote work and online learning, helped sustain the market during the COVID- 19 pandemic.
Data centers are critical infrastructures that support the growing demand for data-intensive applications, including cloud computing and big data analytics. As more businesses move their data and applications to the cloud, there is an increasing demand for high-speed and reliable optical networks. Hence, companies are adopting optical modules to support the increased data traffic generated by cloud applications. Optical modules are becoming increasingly important for data centers as they connect servers, storage, and networking equipment in data centers. They are a high-speed, low-latency and low-power alternative to traditional copper-based networks and allow data centers to handle the increasing data traffic generated by data-intensive applications. These factors are boosting the adoption of optical modules among data centers, driving the growth of this market.
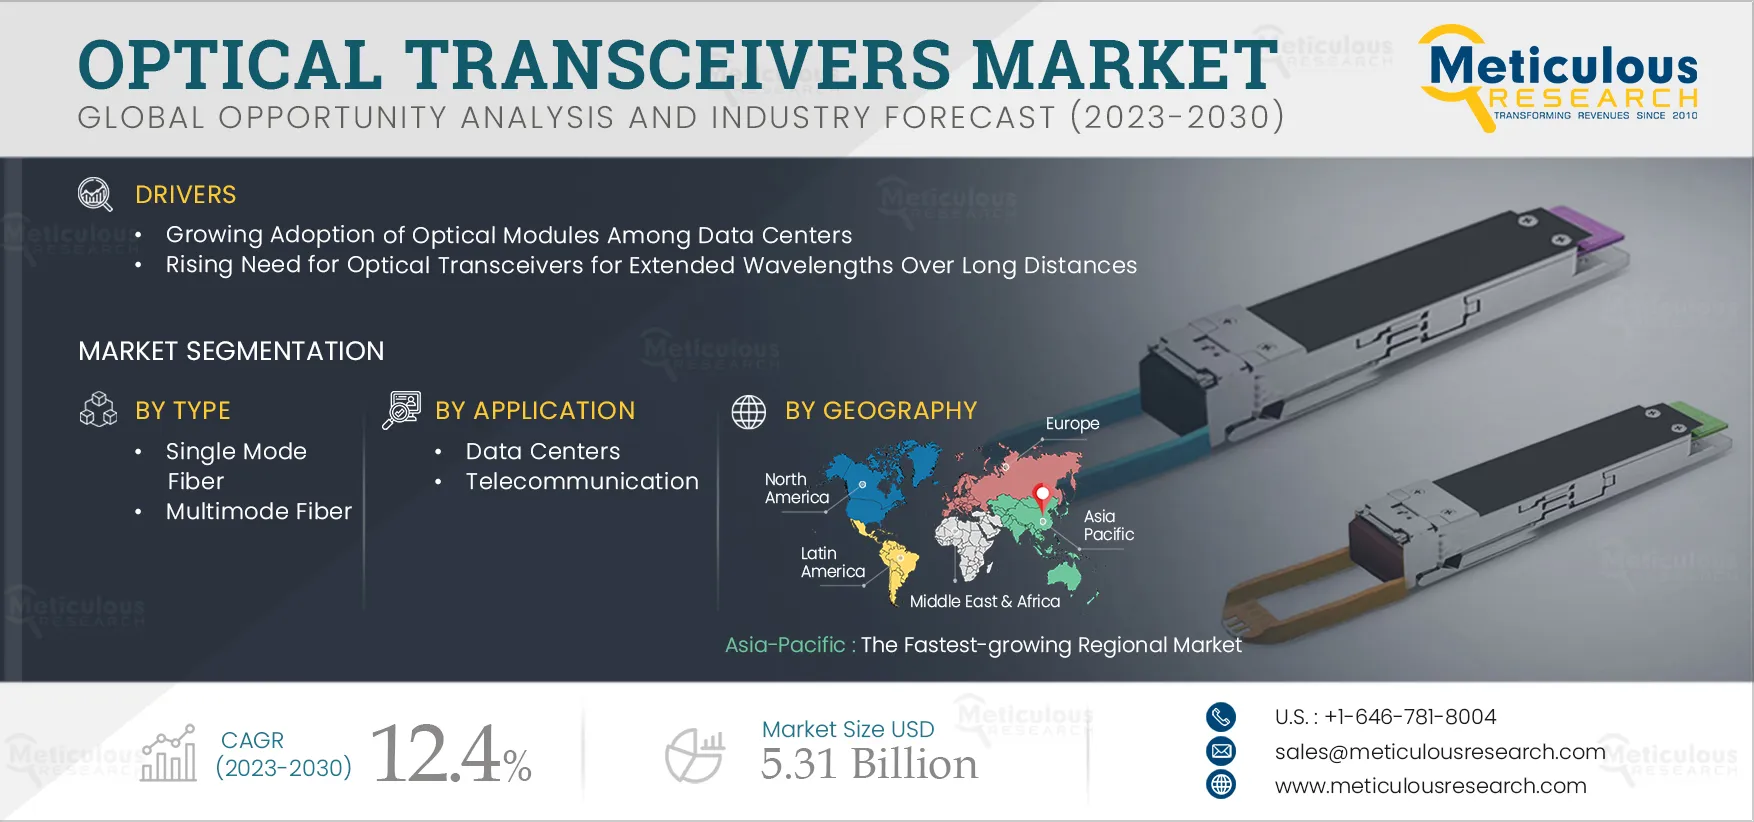
Table of contents
16 chapters · 219 sections · 403 pages · click to expandSegmental analysis
| Segment | Largest share (2023) | Fastest growth (2023–2030) |
|---|---|---|
| By Form Factor | Large market share of this | CFP, CFP2, & CFP4 |
| By Type | — | — |
| By Application | Large market share and high growth of this | — |
By Form Factor
- In terms of value, in 2023, the QSFP, QSFP+, QSFP-DD, and QSFP28 Segment is Expected to Dominate the Optical Transceivers Market
- In terms of value, in 2023, the QSFP, QSFP+, QSFP-DD, and QSFP28 segment is expected to account for the largest share of the optical transceivers market.
- The large market share of this segment is mainly attributed to the factors such as the increasing installation of optical transceivers for data center aggregation and backplane applications and the growing demand for compact and energy-efficient transceivers and high-speed data transmission.
- However, the CFP, CFP2, & CFP4 segment is projected to register the highest CAGR during the forecast period.
By Type
- In terms of value, in 2023, the Single Mode Fiber Segment is Expected to Dominate the Optical Transceiver Market
- In terms of value, in 2023, the single mode fiber segment is expected to account for the largest share of the optical transceivers market and grow at a higher CAGR during the forecasted period.
- This segment's large market share and high growth are attributed to the high-volume adoption of high-data-rate modules, rising demand for high data transmission, growing demand for optical communications for low signal attenuation and high bandwidth, and expansion of telecom infrastructure.
By Application
- In terms of value, in 2023, the Data Centers Segment is Expected to Dominate the Optical Transceiver Market
- In terms of value, in 2023, the data centers segment is expected to account for the largest share of the optical transceivers market and is expected to grow at the highest CAGR during the forecasted period.
- The large market share and high growth of this segment are attributed to the growing need to improve the power efficiency of data center infrastructure, the growing use of datacom applications, the need to connect more data centers over distances, the rising utilization of cloud services, and data centers’ need for high bandwidth.
Geographic analysis
Asia-Pacific
Fastest growthAsia-Pacific is slated to register the highest CAGR during the forecast period due to factors such as the increasing adoption of optical modules in data centers and 5G & cloud technologies in the region and increasing demand for high-speed data transmission and communication networks. Furthermore, rising development and initiatives towards enhancing digital infrastructure and the growing need for higher bandwidths drive the growth of this regional market. Asia-Pacific to be the Fastest-growing Regional Market
Competitive landscape
- Hisense Broadband, Inc.
- Huawei Technologies Co., Ltd.
- Juniper Networks, Inc.
- HG Genuine Co., Ltd.
- Eoptolink Technology Inc.
- Accelink Technologies Co., Ltd.
- Broadcom Inc.
- Coherent Corp.
- Sumitomo Electric Industries, Ltd.
- SUHNER AG
- Luxshare Precision Industry Co., Ltd.
- Acacia Communications, Inc.
- Fujitsu Optical Components Co., Ltd.
- Intel Corporation
Frequently asked questions
The optical transceivers market is projected to reach $5.31 billion by 2030 at a CAGR of 12.4% during the forecast period.
Cite this report
Meticulous Research. (2023). Optical Transceivers Market - Global Opportunity Analysis And Industry Forecast (2023-2030) (Report No. MR-775). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/reports/optical-transceivers-market-5459