Europe Plant-based Food Market (2024-2031)
The European Plant-based Foods Market was valued at $9.78 billion in 2023. It is expected to reach $21.62 billion by 2031 from an estimated $10.85 billion in 2024, at a CAGR of 10.3% during the forecast period from 2024 to 2031. Europe Plant-based Foods Market Size & Forecast The growth of this market
- Published
- Sep 2024
- Pages
- 190
- Format
- PDF + Excel
- Report ID
- MRFB - 104574
- Base year
- 2024
- 2023 · HISTORICAL
- $9.78B
- 2031
- $21.62B
- CAGR 2024–2031
- 10.3%
2023 baseline · 2024–2031 forecast at 10.3% CAGR · hover a bar for the value
Key highlights
The European Plant-based Foods Market was valued at $9.78 billion in 2023.
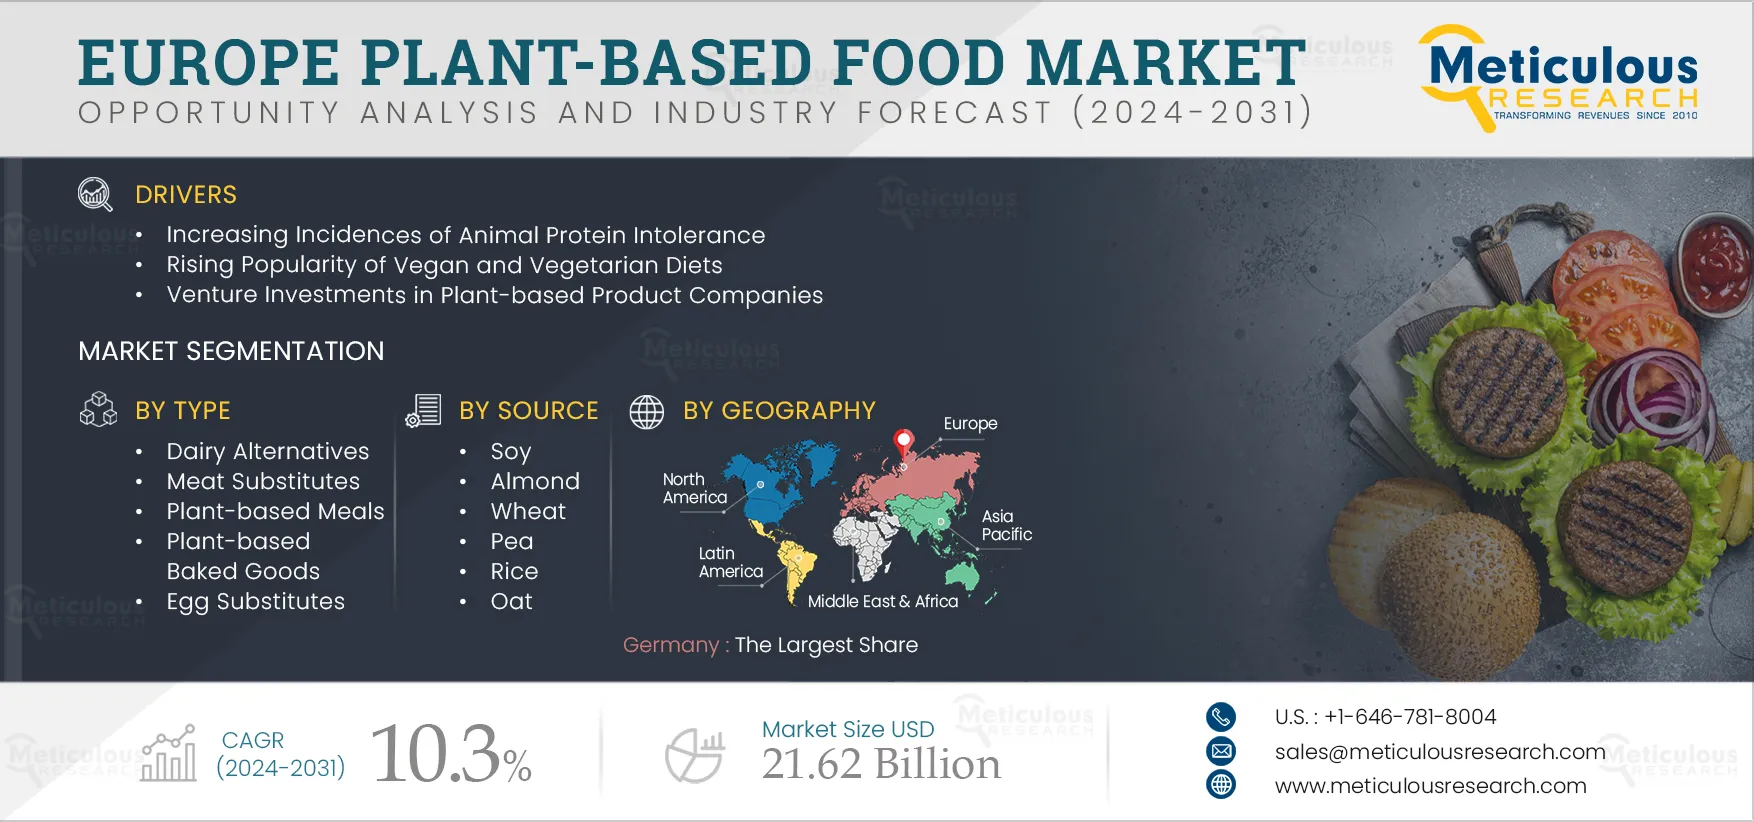
It is expected to reach $21.62 billion by 2031 from an estimated $10.85 billion in 2024, at a CAGR of 10.3% during the forecast period from 2024 to 2031.
The dairy alternatives segment is expected to account for the largest share of 67.2% of the Europe plant-based foods market.
The business-to-consumer segment is expected to account for a larger share of 70.2% of the Europe plant-based foods market.
In 2024, Germany is expected to account for the largest share of 23.9% of the Europe plant-based foods market. Germany’s plant-based foods market is estimated to be worth USD 2.59 billion in 2024.
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 190 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2024 |
| CAGR (Value) | 10.3% |
| Market Size (Value) | USD 21.65 Billion by 2031 |
| Segments Covered | By Type · Dairy Alternatives · Milk · Cheese · Yogurt · Butter · Ice Cream · Creamer · Other Dairy Alternatives · Meat Substitutes · Tofu · Textured Vegetable Protein (TVP) · Burger Patties · Tempeh · Hot Dogs & Sausages · Seitan · Meatballs · Ground Meat · Nuggets · Crumbles · Shreds · Other Meat Substitutes · Plant-based Meals · Plant-based Baked Goods · Plant-based Confectionery · Plant-based Beverages · Egg Substitutes · Fish and Seafood Alternatives · Other Plant-based Meal Alternatives · By Source · Soy · Almond · Wheat · Pea · Rice · Oat · Other Sources · By Distribution Channel · Business-to-business · Business-to-consumer · Modern Groceries/Supermarkets and Hypermarkets · Convenience Stores · Specialty Stores · Online Retail Stores · Other B2C Distribution Channels |
| Countries Covered | Germany, U.K., Spain, Italy, France, Netherlands, Belgium, Austria, Poland, Portugal, Denmark, Romania, Sweden, and Rest of Europe |
| Key Companies | Beyond Meat Inc. (U.S.), Danone S.A. (France), Amy’s Kitchen Inc. (U.S.), The Hain Celestial Group, Inc. (U.S.), Daiya Foods Inc. (Canada), Marlow Foods Ltd. (U.K.), Taifun –Tofu GmbH (Germany), Vbite Food Ltd (U.K.), Plamil Foods Ltd (U.K.), Plant & Bean Ltd (U.K.), Unilever PLC (U.K.), Berief Food GmbH (Germany), Nestlé S.A. (Switzerland), The Meatless Farm (U.K.), and Veganz Group AG (Germany) |
Report overview
Segments covered: type, source, distribution channel.
The growth of this market is driven by the increasing prevalence of animal protein intolerance, the surging interest in vegan and vegetarian diets, increased venture capital investments in plant-based foods enterprises, and ongoing innovations in food technology. In addition, the launch of new products by manufacturers of plant-based foods and protein alternatives is anticipated to generate significant opportunities for market players.
However, factors such as the higher cost of plant-based foods and a strong consumer preference for animal-based products are expected to pose significant challenges to market growth.
Report infographic
Market dynamics
3 factors across 2 forcesRising Popularity of Vegan and Vegetarian Diets Driving Market Growth
In recent years, vegetarianism and veganism have gained popularity in Europe, driven by increased health awareness, environmental concerns, and compassion for animals. According to the European Vegetarian Union, around 10% of the European population identified as vegetarian in 2023, up from 3% in 2007, while 3% were vegan. A study by Veganz, a German vegan supermarket, found that the number of vegans in Germany has doubled since 2016, reaching 2.8 million in 2023.
Vegetarian and vegan consumers increasingly favor plant-based foods. The Academy of Nutrition and Dietetics indicates that well-planned vegetarian (including vegan) diets are healthy and nutritionally sufficient. These diets can lower the risk of various health issues, such as ischemic heart disease, type 2 diabetes, hypertension, obesity, and certain cancers. They are suitable for all life stages, including pregnancy, lactation, infancy, childhood, adolescence, and older adulthood, as well as for athletes. Additionally, lactose-intolerant consumers seek dairy alternatives due to their difficulty in digesting lactose, the sugar present in milk and dairy products (Source: National Institutes of Health).
Lactose tolerance is prevalent in Northern European countries like Sweden and Finland. In contrast, Turkey, Italy, Germany, and Spain have some of the highest rates of lactose intolerance. The target market for plant-based food and beverage products extends beyond vegans to include flexitarians, lactose-intolerant consumers, and those seeking clean-label food and beverage options. Consequently, the increasing popularity of vegan and vegetarian diets is fueling the growth of the plant-based foods market in Europe.
Innovation in Food Technologies
Plant-based products are increasingly becoming integral to modern diets. Consumer demand for ethical, sustainable, and healthy protein sources is driving significant investments and innovation in the meat and dairy substitute industry. Innovative food encompasses novel products and ingredients, including alternative meats (both plant-based and cell-culture-based), insect protein, alternative sugars, and flavor enhancers. According to the Good Food Institute, the global alternative proteins sector attracted USD 523 million in disclosed investments in 2023, with approximately USD 190 million allocated for R&D. Additionally, although the number of start-ups in the AgriFood Tech sector is relatively small, the food research and innovation sector secured around USD 6.8 billion in total investment in 2023 (Source: European Commission). This category is led by animal-free meat and dairy alternatives, and healthy ingredients, indicating a strong commitment to supporting alternative proteins in Europe.
Advancements in plant-based products are boosting consumer interest and expanding shelf space in retail settings. According to the World Resources Institute (WRI), even the most efficient meat source, chicken, converts only about 11% of gross feed energy into animal protein (WRI 2022). This inefficiency highlights the need for a systemic change within the industry. As a result, a technological revolution is underway, producing a variety of plant-based products that can effectively compete with their animal-based counterparts. Consequently, innovation in food technologies is a key driver of market growth.
Table of contents
11 chapters · 129 sections · 190 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Type | Dairy Alternatives | Fish and seafood alternatives |
| By Distribution Channel | Business-to-consumer | Business-to-consumer |
By Type
- The dairy alternatives segment is expected to account for the largest share of 67.2% of the Europe plant-based foods market.
- This segment's large market share can be attributed to the rising number of lactose-intolerant individuals, growing ethical concerns among consumers regarding animal welfare in modern dairy farming, and the nutritional advantages provided by plant-based dairy products.
- However, the fish and seafood alternatives segment is anticipated to register the highest CAGR of 28.7% during the forecast period.
- This segment's growth is driven by the increasing consumer demand for vegan seafood, increased investment and food innovation in species-specific seafood alternatives, and increased new product launches.
By Distribution Channel
- The business-to-consumer segment is expected to account for a larger share of 70.2% of the Europe plant-based foods market.
- This segment's large market share can be attributed to several factors, including the rising sales of plant-based foods in established supermarkets and hypermarkets, consumer preference for shopping at brick-and-mortar stores due to their accessibility and availability, and increasing consumer spending on vegan products.
- Moreover, the business-to-consumer segment is anticipated to register the highest CAGR of 11.7% during the forecast period.
- This growth is attributed to the rapidly expanding online retail sector, which offers enhanced accessibility, convenience, and cost-effectiveness.
Geographic analysis
Europe
Largest shareIn 2024, Germany is expected to account for the largest share of 23.9% of the Europe plant-based foods market. Germany’s plant-based foods market is estimated to be worth USD 2.59 billion in 2024. Several key factors, including the modernization of the F&B industry, increased consumer awareness of the benefits of plant-based foods, growing concerns about animal welfare, and a rise in new product launches within the plant-based foods sector, drive Germany's large market share. Moreover, Germany is poised to register the highest CAGR of 11.3% during the forecast period. This growth is attributed to the rapidly expanding vegetarian population and the increasing number of vegan and vegetarian restaurants in Germany. Veganism is emerging as a significant trend, with the number of vegans doubling from 1.3 million in 2016 to 2.8 million in 2023. Additionally, nearly 75% of German households express a desire for a wider variety of vegetarian products in supermarkets, although less than two-thirds actively purchase these products. Germany Dominates the Europe Plant-based Foods Market
Competitive landscape
- March 2024
Gosh! Food Limited (U.K.), a plant-based food brand, launched street food and glaze & grill BBQ kits.
- October 2021
Nestlé S.A., based in Switzerland, launched Garden Gourmet vEGGie, a plant-based egg alternative, alongside Garden Gourmet Vrimp, a plant-based shrimp alternative.
- May 2021
Unilever PLC, based in the U.K., partnered with ENOUGH (formerly known as 3F BIO), a U.K.-based food-tech company, to introduce new plant-based meat products to the market.
- February 2021
Danone SA, a French company, acquired Follow Your Heart, a U.S.-based manufacturer of plant-based products. This acquisition strengthened Danone's plant-based portfolio.
- Beyond Meat Inc. (U.S.)
- Danone S.A. · France
- Amy’s Kitchen Inc. (U.S.)
- Hain Celestial Group, Inc. (U.S.)
- Daiya Foods Inc. · Canada
- Marlow Foods Ltd. (U.K.)
- Taifun –Tofu GmbH · Germany
- Vbite Food Ltd (U.K.)
- Plamil Foods Ltd (U.K.)
- Plant & Bean Ltd (U.K.)
- Unilever PLC (U.K.)
- Berief Food GmbH · Germany
- Nestlé S.A. · Switzerland
- Meatless Farm (U.K.)
- Veganz Group AG · Germany
Frequently asked questions
This study focuses on market analysis and opportunity assessment based on the sales of Europe plant-based foods across various countries and market segments. It also includes a competitive analysis based on key market players’ product portfolios, geographic presence, and growth strategies adopted in the last three to four years.
The Europe plant-based foods market study provides valuable insights, market sizes, and forecasts in terms of value by type, source, distribution channel, and country.
Cite this report
Meticulous Research. (2024). Europe Plant-based Food Market - Opportunity Analysis And Industry Forecast (2024-2031) (Report No. MRFB - 104574). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/europe-plant-based-food-market-5260