Cardiovascular Information Systems (CVIS) Market (2026-2036)
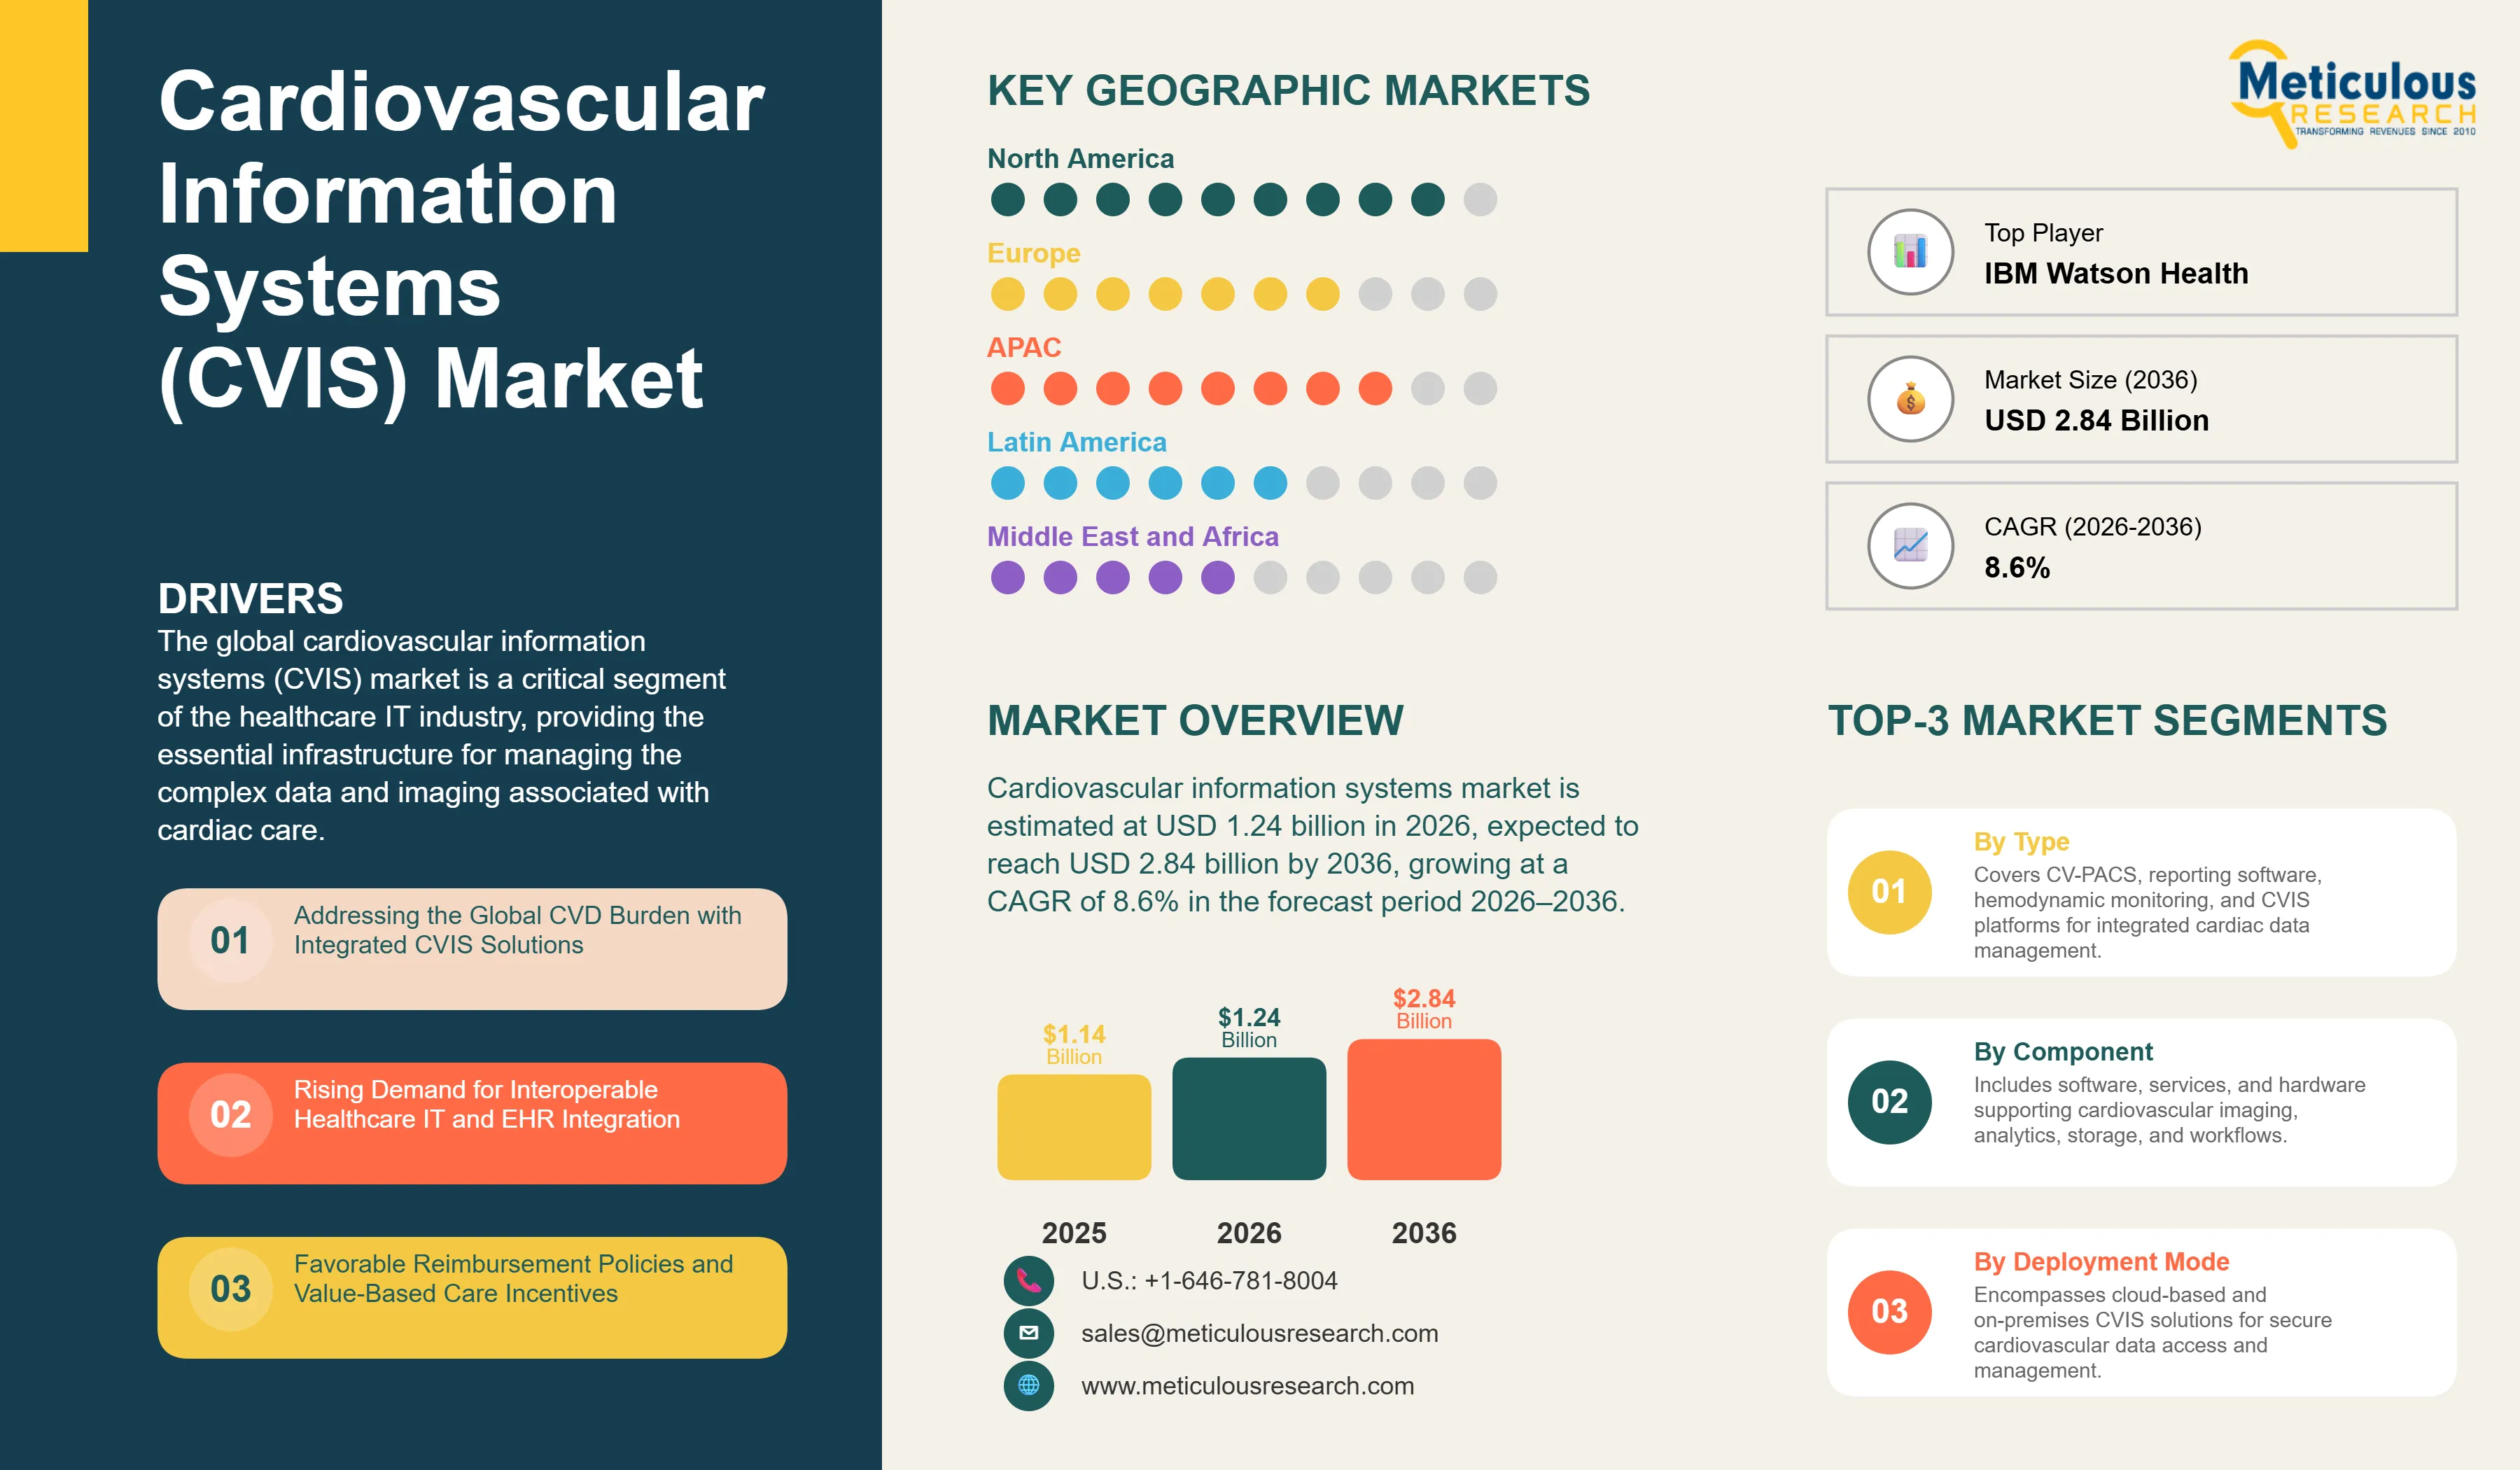
The global cardiovascular information systems (CVIS) market is estimated at USD 1.24 billion in 2026. This market is expected to reach USD 2.84 billion by 2036, growing at a CAGR of 8.6% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 276
- Format
- PDF + Excel
- Report ID
- MRHC - 1042040
- Base year
- 2025
- 2026 · ESTIMATED
- $1.24B
- 2036
- $2.84B
- CAGR 2026–2036
- 8.6%
2025 baseline · 2026–2036 forecast at 8.6% CAGR · hover a bar for the value
Key highlights
The global cardiovascular information systems (CVIS) market is projected to reach USD 2.84 billion by 2036, growing at a CAGR of 8.6% during the forecast period 2026–2036.
North America is expected to dominate the global market in 2026, driven by a high prevalence of cardiovascular diseases (CVD), a mature healthcare IT infrastructure, and significant investments in cardiac care modernization.
Asia Pacific is projected to witness the fastest growth, fueled by the rising burden of CVD and government initiatives to improve healthcare access and digital health adoption across China and India.
By type, the CV-PACS (Cardiovascular Picture Archiving and Communication System) segment is expected to hold the largest share in 2026, as hospitals prioritize integrated imaging and reporting solutions.
By deployment mode, the cloud-based segment is expected to account for the largest share in 2026, with approximately 68% of new installations favoring SaaS models for cross-departmental data access.
By component, the software segment is expected to dominate the market in 2026, reflecting the increasing reliance on advanced analytics and AI-driven diagnostic tools for cardiac care.
By end user, the hospitals segment is expected to hold the largest share in 2026, as these facilities manage the highest volumes of cardiac procedures and patient data.
Key players operating in the global market include GE HealthCare Technologies Inc., Koninklijke Philips N.V., Siemens Healthineers AG, Fujifilm Holdings Corporation, and IBM Watson Health (Merative).
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 1.24 billion |
| Market Size (2036) | USD 2.84 billion |
| CAGR (2026–2036) | 8.6% |
| Format | PDF, Excel & Cloud Portal · 276 pages |
| Segments Covered | By Type · By Deployment Mode · By Component · By End User |
| Key Companies | GE HealthCare Technologies Inc., Koninklijke Philips N.V., Siemens Healthineers AG, Lunit Inc., ScImage, Inc. |
Report overview
Segments covered: type, deployment mode, component, end user.
The global cardiovascular information systems (CVIS) market is a critical segment of the healthcare IT industry, providing the essential infrastructure for managing the complex data and imaging associated with cardiac care. CVIS solutions, including CV-PACS, hemodynamic monitoring systems, and cardiovascular reporting software, enable clinicians to aggregate data from various diagnostic modalities—such as echocardiography, cardiac catheterization, and electrophysiology—into a unified patient record. As of 2026, the market is undergoing a significant transformation, driven by the global imperative to address the rising prevalence of cardiovascular diseases (CVD), which remains the leading cause of death worldwide. According to the World Health Organization (WHO), CVDs claim an estimated 17.9 million lives each year, accounting for 32% of all global deaths. The transition toward integrated and interoperable CVIS platforms is essential for improving clinical productivity and patient outcomes in cardiology. Modern CVIS solutions leverage advanced analytics and AI-driven tools to provide clinicians with actionable insights, facilitating more accurate diagnoses and personalized treatment planning. Furthermore, the integration of CVIS with Electronic Health Records (EHRs) and other hospital information systems ensures that stakeholders have immediate access to a comprehensive view of the patient's cardiovascular health. As healthcare systems transition toward value-based care models, the demand for CVIS solutions that can demonstrate improved operational efficiency and reduced diagnostic turnaround times is expected to surge.
The primary driver for the CVIS market is the escalating global burden of cardiovascular diseases, which necessitates a more efficient and data-driven approach to cardiac care. According to the American Heart Association (AHA) 2026 Statistical Update, nearly half of all adults in the U.S. have some form of CVD. This massive patient population is driving the adoption of integrated CVIS platforms to manage the high volume of diagnostic images and clinical data. Furthermore, the shift toward digital health and the increasing demand for interoperable healthcare systems are significant drivers. Government initiatives promoting the adoption of EHRs and the exchange of health information, such as the 21st Century Cures Act in the U.S., are compelling hospitals to invest in CVIS solutions that can seamlessly integrate with broader healthcare IT ecosystems.
Market growth is restrained by the high cost of implementing comprehensive CVIS solutions and the technical challenges of achieving seamless data interoperability across disparate diagnostic modalities and legacy IT systems. For many hospitals, the initial capital investment and ongoing maintenance costs of a CVIS can be a significant barrier. Additionally, the lack of standardized data protocols between different medical device manufacturers often leads to data silos, making it difficult to achieve a truly unified cardiovascular record. Concerns regarding data privacy and cybersecurity in centralized information hubs also act as deterrents to market expansion. Furthermore, the significant organizational change management and staff training required for successful CVIS implementation can lead to operational disruptions and slower adoption rates.
The integration of artificial intelligence (AI) and machine learning (ML) into CVIS platforms offers substantial growth opportunities. AI-powered tools can analyze complex cardiac images and physiological data to identify subtle anomalies, facilitating earlier diagnosis and more precise treatment planning. By 2026, AI-driven predictive analytics are being used to forecast the risk of acute cardiac events, enabling proactive intervention and improving patient safety. Furthermore, the shift toward cloud-native (SaaS) CVIS platforms provides health systems with superior scalability, flexibility, and lower upfront costs. Cloud-based solutions also facilitate remote access to cardiac data, supporting telehealth and multi-facility collaboration, which is particularly beneficial for regional cardiac care networks.
Report infographic
Market dynamics
2 factors across 1 forceEvolution toward Holistic and AI-Powered Cardiac Care Orchestration
A defining trend in 2026 is the evolution of CVIS from siloed reporting tools into holistic, AI-powered cardiac care orchestration hubs. These platforms aggregate data from across the cardiovascular continuum—including non-invasive imaging, interventional cardiology, and cardiac surgery—to provide a unified view of the patient journey. Advanced AI engines are increasingly capable of automating routine reporting tasks and providing clinical decision support, reducing the cognitive load on cardiologists and improving diagnostic consistency. This trend reflects a strategic shift toward proactive, enterprise-wide cardiac management, prioritizing clinical safety and operational efficiency.
Integration of Advanced Visualization and Virtual Reality for Cardiac Planning
The integration of advanced visualization tools, including 3D/4D imaging and virtual reality (VR), into CVIS platforms is gaining significant traction. These technologies allow clinicians to perform more detailed pre-procedural planning and simulation for complex cardiac interventions, such as structural heart procedures and electrophysiology mapping. In 2026, VR-enabled CVIS modules are being used to enhance surgeon training and improve patient communication by providing immersive views of cardiac anatomy. This trend is supported by clinical evidence demonstrating that advanced visualization leads to shorter procedure times and improved clinical outcomes for high-risk cardiac patients.
Table of contents
12 chapters · 117 sections · 276 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Type | CV-PACS | Cardiovascular reporting software |
| By Deployment Mode | Cloud-based | — |
By Type
- The CV-PACS segment is expected to hold the largest share in 2026.
- This dominance is driven by the foundational role of CV-PACS in managing and archiving cardiac images from various diagnostic modalities.
- The cardiovascular reporting software segment is projected to register the highest CAGR, reflecting the increasing demand for structured reporting and AI-driven documentation to improve clinical productivity and regulatory compliance.
- Hemodynamic monitoring systems remain a critical segment, providing real-time physiological data during interventional procedures.
By Deployment Mode
- The cloud-based segment is expected to account for the largest share in 2026.
- The advantages of cloud deployment, such as scalability, reduced IT burden, and ease of cross-departmental data access, make it highly attractive to healthcare organizations.
- Approximately 68% of new CVIS installations in 2026 are opting for SaaS models.
- The on-premises segment continues to serve large hospital networks with specific data sovereignty requirements and those with significant existing IT infrastructure.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global CVIS market in 2026. The region's leadership is supported by a high prevalence of CVD, a mature healthcare IT landscape, and significant investments in cardiac care modernization by large hospital networks. Favorable reimbursement policies and a strong regulatory focus on interoperability and clinical quality continue to drive market growth in the U.S. and Canada. The presence of leading CVIS vendors and a robust ecosystem for medical innovation also contribute to North America's dominant position.
Asia-Pacific
Fastest growthThe Asia Pacific region is projected to witness the fastest growth during the forecast period. This growth is fueled by the rising burden of CVD and government initiatives to modernize healthcare infrastructure across China, India, and Australia. As these countries implement large-scale digital health initiatives and increase their focus on expanding access to specialized cardiac care, the demand for integrated CVIS solutions is expected to rise significantly. The increasing adoption of cloud-based platforms and the digital transformation of public health agencies in the region are creating substantial opportunities for global and local CVIS vendors.
Competitive landscape
The competitive landscape of the global CVIS market is characterized by intense innovation and strategic consolidations as vendors seek to provide end-to-end cardiac care orchestration platforms. Leading players are differentiating themselves through the sophistication of their AI engines and their ability to provide seamless integration with EHRs and other hospital information systems. Strategic acquisitions of niche imaging and analytics companies are a common trend as vendors seek to enhance their diagnostic capabilities. The market is also seeing increased collaboration between CVIS vendors and medical device manufacturers to ensure seamless data flow from the point of care. Key players operating in the global CVIS market include GE HealthCare Technologies Inc. (U.S.), Koninklijke Philips N.V. (Netherlands), Siemens Healthineers AG (Germany), Fujifilm Holdings Corporation (Japan), IBM Watson Health (Merative) (U.S.), Agfa-Gevaert Group (Belgium), Change Healthcare (UnitedHealth Group) (U.S.), Lunit Inc. (South Korea), Intelerad Medical Systems Incorporated (Canada), and ScImage, Inc. (U.S.).
- GE HealthCare Technologies Inc.
- Koninklijke Philips N.V.
- Siemens Healthineers AG
- Lunit Inc.
- ScImage, Inc.
Frequently asked questions
The market is projected to reach USD 2.84 billion by 2036, growing at a CAGR of 8.6% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Cardiovascular Information Systems (CVIS) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1042040). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/cardiovascular-information-systems-market-6723