Automotive LiDAR Market (2025-2032)
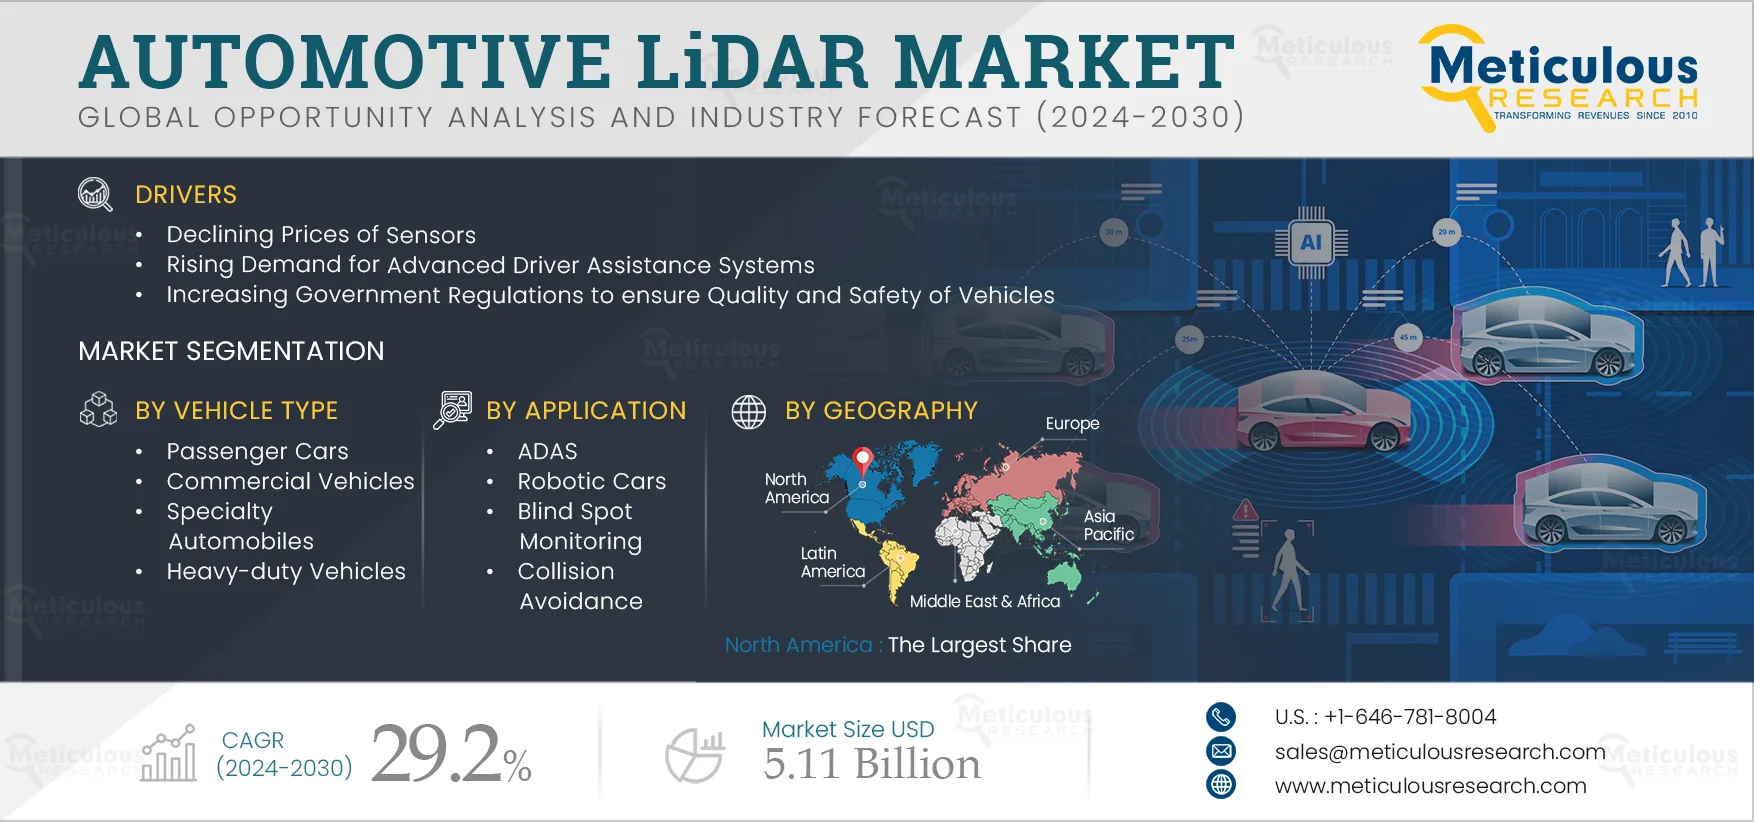
The Automotive LiDAR Market is projected to reach $5.11 billion by 2032, at a CAGR of 29.2% during the forecast period of 2025 to 2032.
- Published
- Jan 2025
- Pages
- 300
- Format
- PDF + Excel
- Report ID
- MRSE - 104790
- Base year
- 2024
- 2032 · FORECAST
- $5.11B
- 2032
- $5.11B
- CAGR 2025–2032
- 29.2%
2024 baseline · 2025–2032 forecast at 29.2% CAGR · hover a bar for the value
Key highlights
In 2025, the Passenger Cars Segment is Expected to Dominate the Automotive LiDAR Market
In 2025, the Mechanical LiDAR Segment is Expected to Dominate the Automotive LiDAR Market
In 2025, North America is Expected to Dominate the Automotive LiDAR Market
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2024 |
| Estimated Year | 2025 |
| Forecast Period | 2025–2032 |
| Market Size (2032) | USD 5.11 billion |
| CAGR (2025–2032) | 29.2% |
| Format | PDF, Excel & Cloud Portal · 300 pages |
| Segments Covered | By Vehicle Type: Passenger Cars, Commercial Vehicles Commercial Trucks Semi-trucks, Box Trucks, Pick-up Trucks, Cargo Vans, Passenger Vans, Passenger Buses, Motor coaches and RVs, Agriculture Vehicles, Mining Vehicles, Construction Vehicles · By Imaging: Mechanical LiDAR, Solid-state LiDAR Microelectromechanical Systems (MEMS), Optical-phased Array (OPA), Flash, Other Solid-state LiDAR · By Ranging Method: Pulse, Frequency-modulated Continuous Wave (FMCW), Other Ranging Methods · By Application: ADAS, Robotic Cars, Blind Spot Monitoring, Collision Avoidance, Parking Assistance, Lane Departure Warning, Adaptive Cruise Control, Pedestrian Detection, Other Applications · By Autonomy: Autonomous, Semi-autonomous, Manual-driven Vehicles · By Type: Passenger Cars, Commercial Vehicles · By Ranging |
| Countries Covered | Asia-Pacific (Japan, India, South Korea, Australia & New Zealand, Rest of Asia-Pacific), Europe (Germany, U.K., France, Italy, Spain, Switzerland, Netherlands, Sweden) |
| Key Companies | Ouster, Inc., Luminar Technologies, Inc., Quanergy Systems, Inc., LeddarTech Inc., Continental AG, Baraja Pty Ltd., MicroVision, Inc., Aeva Inc., Waymo LLC, Innoviz Technologies Ltd., Cepton, Inc., Robert Bosch GmbH |
Report overview
Segments covered: vehicle type, imaging, ranging method, application, autonomy, type, ranging. Regions: Asia-Pacific, Europe.
The growth of this market is attributed to the declining prices of sensors, the rising demand for advanced driver assistance systems, and the increasing government regulations to ensure the quality and safety of vehicles. In addition, the rising demand for electric vehicles, the development of autonomous vehicles, the emergence of 4D LiDAR, and increasing investments by OEMs in LiDAR start-ups are expected to offer significant opportunities for the growth of this market.
However, the low adoption of LiDAR in economy-class vehicles hampers the growth of this market. In addition, the limitations of LiDAR, such as lack of visibility in bad weather conditions, are a major challenge to the growth of this market.
Report infographic
Development in Autonomous Vehicles
Advancements in LiDAR technology have led to innovations such as autonomous vehicles. Technological advancements have made autonomous vehicles a real-world possibility, with many automotive manufacturers heavily investing in developing such vehicles due to the increasing demand. Autonomous vehicles are completely driven by sensors and electronics, ensuring a complete driverless experience. LiDAR sensors are crucial in such vehicles as they are major components of essential systems such as blind-spot monitoring, lane-keep assistance, lane-departure warning, and collision warning to prevent accidents.
According to the World Health Organization, more than 90% of road traffic deaths occur due to human error, overspeeding, driving under the influence of alcohol or other psychoactive substances, and not using motorcycle helmets, seat belts, and child restraints, among many other reasons. To address these issues, many OEMs are integrating LiDAR sensors into autonomous vehicles, enabling them to detect objects and provide emergency braking assistance alongside many other features. For instance, in January 2022, German automotive giant Mercedes-Benz Group AG acquired a stake in LiDAR manufacturing company Luminar Technologies, Inc. (U.S.). The acquisition will enable Mercedes to produce vehicles with autonomous driving capabilities. Such developments are expected to offer growth opportunities for companies operating in this market.
Table of contents
13 chapters · 129 sections · 300 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Vehicle Type | Passenger Cars | Passenger cars |
| By Imaging | Mechanical LiDAR | Solid-state LiDAR |
| By Ranging Method | FMCW | — |
| By Application | Advanced Driver Assistance System | — |
| By Autonomy | Semi-Autonomous | Autonomous |
By Vehicle Type
- The passenger cars segment is expected to account for the largest share and is projected to register the highest CAGR during the forecast period.
- This segment's large market share and rapid growth are attributed to the increased adoption of LiDAR sensors in passenger cars to prevent collisions.
By Imaging
- The mechanical LiDAR segment is expected to account for the larger share of the market.
- A mechanical LiDAR can collect data over a wide area of up to 360 degrees to provide a detailed mapping of the environment, increasing its applications in mapping, surveying, and robotics.
- These benefits contribute to the large market share of this segment.
- However, the solid-state LiDAR segment is projected to register the highest CAGR during the forecast period.
By Ranging Method
- The automotive LiDAR market is segmented into pulse, FMCW, and other ranging methods.
- The FMCW segment is expected to account for the largest share of the automotive LiDAR market.
- This segment is also projected to register the highest CAGR during the forecast period.
- This segment’s large market share and rapid growth are attributed to the advantages of frequency-modulated continuous-wave (FMCW) LiDAR over other methods in providing high-resolution distance & velocity measurements under limited visibility conditions.
By Application
- The Advanced Driver Assistance System Segment is Expected to Dominate the Automotive LiDAR Market
- The ADAS segment is expected to account for the largest share of the automotive LiDAR market.
- This segment is also projected to register the highest CAGR during the forecast period.
- This segment’s large market share and rapid growth are attributed to the growing need for efficient systems that offer data accuracy across all weather and lighting conditions to prevent accidents and provide additional support to drivers in areas where detailed map information is unavailable.
By Autonomy
- The semi-autonomous segment is expected to account for the largest share of the automotive LiDAR market.
- The large market share of this segment is attributed to rapid technological advancements due to rising collaborations between vehicle manufacturers and tech firms.
- However, the autonomous segment is projected to register the highest CAGR during the forecast period.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of the market. North America’s major market share is attributed to stringent government regulations in the region mandating the installation of specific automotive safety technologies in vehicles and the rising advancements in LiDAR technologies, increasing their applications in core 3D imaging and ranging. In 2025, North America is Expected to Dominate the Automotive LiDAR Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is projected to register the highest CAGR during the forecast period.
Competitive landscape
- Ouster, Inc.
- Luminar Technologies, Inc.
- Quanergy Systems, Inc.
- LeddarTech Inc.
- Continental AG
- Baraja Pty Ltd.
- MicroVision, Inc.
- Aeva Inc.
- Waymo LLC
- Innoviz Technologies Ltd.
- Cepton, Inc.
- Robert Bosch GmbH
Frequently asked questions
The automotive LiDAR market is projected to reach $5.11 billion by 2032, at a CAGR of 29.2% from 2025 to 2032.
Cite this report
Meticulous Research. (2025). Automotive LiDAR Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRSE - 104790). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/automotive-lidar-market-5474