Automotive 3D Printing Market (2025-2032)
The Automotive 3D Printing Market was valued at $3.7 billion in 2024. This market is expected to reach $17.9 billion by 2032 from an estimated $4.5 billion in 2025, at a CAGR of 22% during the forecast period of 2025-2032. Automotive 3D Printing Market Size & Forecast The growth of this market is driven
- Published
- Oct 2024
- Pages
- 300
- Format
- PDF + Excel
- Report ID
- MRSE - 1041355
- Base year
- 2024
- 2024 · BASELINE
- $3.70B
- 2032
- $17.90B
- CAGR 2025–2032
- 22%
2024 baseline · 2025–2032 forecast at 22% CAGR · hover a bar for the value
Key highlights
By Offering: In 2025, the Hardware Segment is Expected to Dominate the Automotive 3D Printing Market
By Technology: In 2025, the Fused Deposition Modeling (FDM) Segment is Expected to Dominate the Automotive 3D Printing Market
By Component: In 2025, the Exterior Components Segment is Expected to Dominate the Automotive 3D Printing Market
By Vehicle Type: In 2025, the ICE Vehicles Segment is Expected to Dominate the Automotive 3D Printing Market
By Application: In 2025, the Prototyping Segment is Expected to Dominate the Automotive 3D Printing Market
By Geography: In 2025, North America to Dominate Automotive 3D Printing
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 300 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 22% |
| Market Size (Value) | USD 17.9 Billion by 2032 |
| Segments Covered | By Offering · Hardware · Software · Services · Material · Polymers · Metals · Ceramics · Composites · Other Materials · By Technology · Fused Deposition Modeling (FDM) · Selective Laser Sintering (SLS) · Stereo Lithography (SLA) · Digital Light Processing (DLP) · Direct Metal Laser Sintering (DMLS) · Electronic Beam Melting (EBM) · Selective Laser Melting (SLM) · Multi Jet Fusion (MJF) · Other Technologies · By Component · Interior Components · Exterior Components · By Vehicle Type · ICE Vehicles · Passenger Vehicles · Commercial Vehicles · Electric Vehicles · Passenger Vehicles · Commercial Vehicles · By Application · Prototyping · Production Parts · Tooling and Manufacturing Aids · Customization and Personalization · R&D and Innovations · Spare Parts and Maintenance · Lightweighting · Other Applications |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, U.K., France, Italy, Spain, Netherlands, Sweden, Switzerland, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Malaysia, Australia & New Zealand, Indonesia, Vietnam, and Rest of Asia-Pacific), Latin America (Mexico, Brazil, and Rest of Latin America), and Middle East & Africa (UAE, Saudi Arabia, Israel, and Rest of Middle East & Africa) |
| Key Companies | 3D Systems Corporation (U.S.), Stratasys Ltd (U.S.), Desktop Metal, Inc. (ETEC) (U.S.), Dassault Systèmes S.E. (France), EOS GmbH (Germany), ExOne Operating, LLC (U.S.), Autodesk, Inc. (U.S.), Hoganas AB (Sweden), Proto Labs, Inc. (U.S.), Formlabs Inc. (U.S.), voxeljet AG (Germany), Markforged Holding Corporation (U.S.), MATERIALISE NV (Belgium), Ultimaker B.V. (Netherland), IC3D, Inc. (U.S.), Moog Inc. (U.S.), and Zortrax S.A. (Poland) |
Report overview
Segments covered: offering, technology, component, vehicle type, application. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
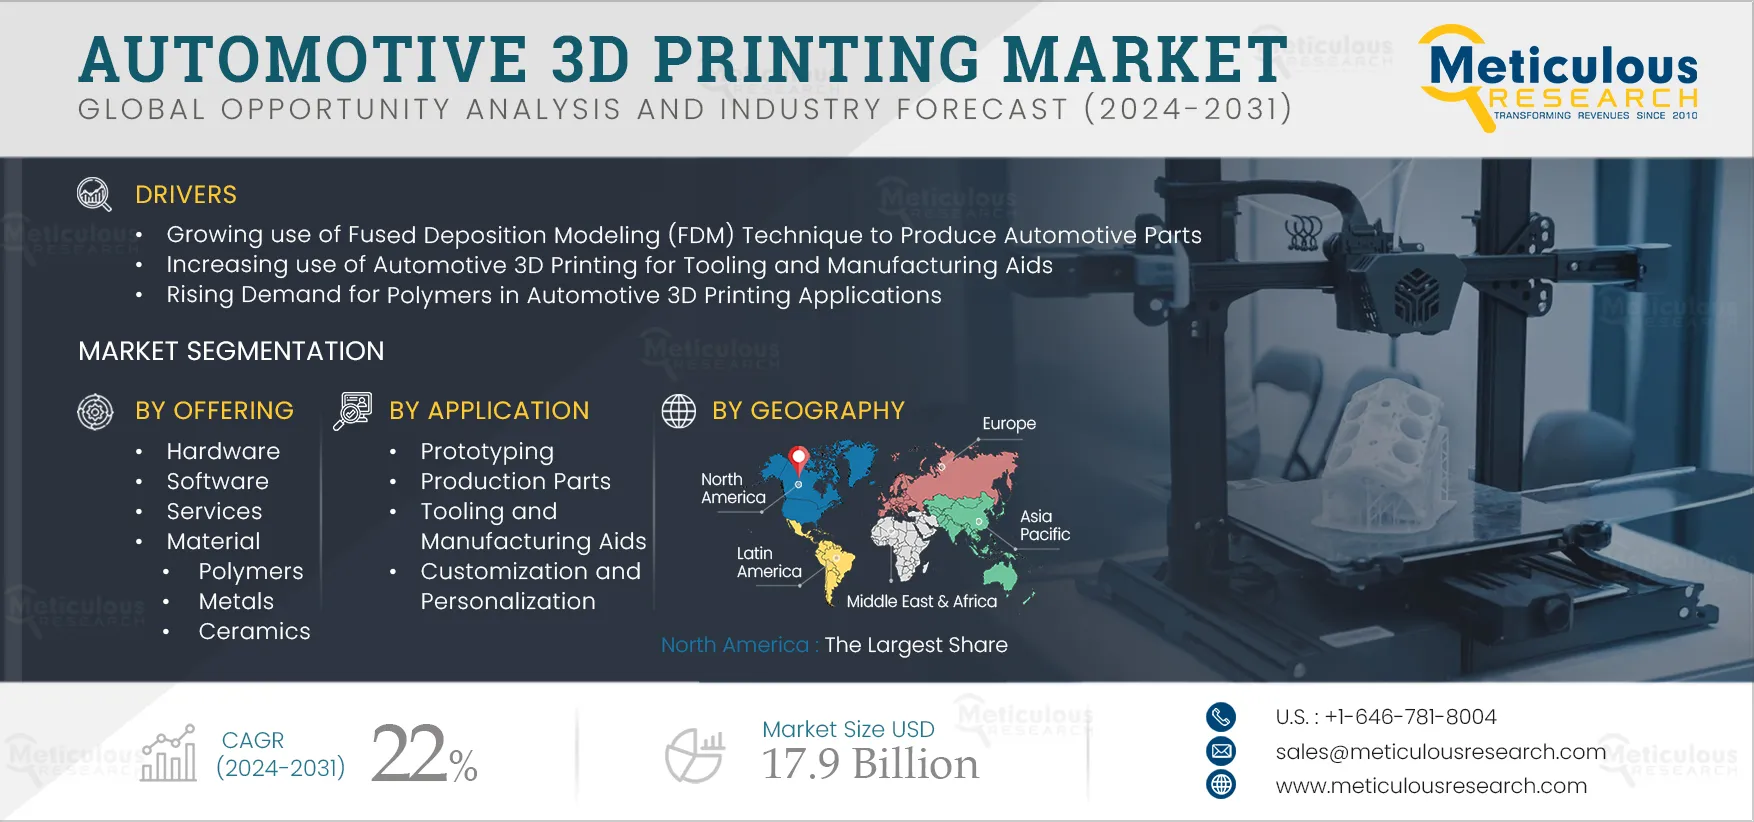
The growth of this market is driven by the growing use of the fused deposition modeling (FDM) technique to produce automotive parts, the Increasing use of 3D printing for tooling and manufacturing aids, and the rising demand for polymers in automotive 3D printing applications. Furthermore, rising customer preference for customized and personalized automotive parts and government initiatives supporting the adoption of 3D printing technologies are expected to generate growth opportunities for the stakeholders in this market.
Report infographic
Market dynamics
3 factors across 2 forcesRising Customer Preference for Customized and Personalized Automotive Parts
In the automotive sector, the demand for customized and personalized parts is significantly driving the growth of automotive 3D printing. Manufacturers are responding to customer preferences by leveraging 3D printing to enhance the car experience and explore new avenues for innovation. As consumer demand rises for modifications, such as custom exhaust systems, suspension enhancements, and specialized engine components, 3D printing techniques facilitate easier and more cost-effective customization of parts. This capability is encouraging automotive manufacturers to expand their offerings and meet the evolving needs of their customers.
Additionally, 3D printing empowers automotive manufacturers to provide bespoke solutions, ranging from custom interiors to limited-edition vehicles. This capability enables companies to more effectively meet customer demands while gaining a competitive advantage in the market. By utilizing 3D printing, manufacturers can streamline the entire production cycle, from design approval to final manufacturing. These growing benefits are driving increased demand for automotive 3D printing for customized and personalized parts.
Table of contents
13 chapters · 153 sections · 300 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Offering | Hardware | — |
By Offering
- The Hardware Segment is Expected to Dominate the Automotive 3D Printing Market in 2025
- The hardware segment is estimated to account for the largest share of the automotive 3D printing market.
- The large share of this segment is attributed to advancements in 3D printers and related equipment that enable efficient and scalable production processes.
- In the automotive sector, the development of next-generation 3D printers has significantly improved precision, speed, and material compatibility.
- These advanced machines facilitate the production of highly complex, lightweight parts that enhance vehicle performance and minimize material waste.
- Additionally, the growth of 3D printing hardware is fueled by the availability of metal 3D printers capable of producing strong, heat-resistant components for automotive applications, such as engine parts, brake systems, and exhaust components.
- As these printers become more affordable and accessible, they are promoting wider adoption of 3D printing technology throughout the automotive industry.
- Furthermore, the use of 3D printing hardware in the automotive industry has increased for prototyping, tooling, and mass production, creating new opportunities for customization, enhanced efficiency, and sustainable manufacturing practices.
- Several manufacturers are introducing 3D printing hardware to produce parts.
- For example, in October 2025, McLaren Automotive (U.K.) launched its new W1 hybrid hypercar, utilizing titanium 3D printing for the front uprights and wishbones of the advanced suspension system.
- These ongoing advancements in the hardware segment are expected to further drive the growth and adoption of 3D printing technology across the automotive market.
Geographic analysis
North America
Largest shareIn 2025, North America is estimated to account for the largest share of the automotive 3D printing market. This large share is primarily driven by the presence of key market players and the increasing demand for customized 3D-printed products in the region. Additionally, the growing adoption of Industry 4.0 principles and expanding collaborations and investments by enterprises in the development of advanced 3D printing technologies and materials further contribute to this trend. North America Dominates the Automotive 3D Printing Market in 2025
Asia-Pacific
Fastest growthHowever, Asia-Pacific is slated to register the highest CAGR during the forecast period. The growth of this market is driven by several factors, including the emergence of automotive manufacturing hubs in countries such as China, Japan, South Korea, and India. Additionally, the low cost of raw materials for automotive 3D printing and the increasing adoption of 3D printing technologies to enhance vehicle design, reduce production costs, and comply with stringent environmental regulations are significant contributors to market growth.
Competitive landscape
- June 2025
Stratasys Ltd (U.S.) partnered with BASF SE (Germany) to introduce SAF Polypropylene for the H350 3D printing system. This SAF PP material is designed for a variety of applications in the automotive, medical, consumer sports, and industrial sectors.
- February 2024
Ford Motor Company (U.S.) announced the opening of a new 3D printing center aimed at enhancing efficiency and quality in its production processes. The facility features twelve 3D printers that produce tools and fixtures for vehicle production in Cologne and can also print components for pilot and small-series vehicles.
- July 2022
Toyota Motor Corporation (Japan) partnered with SOLIZE Corporation (Japan) to launch a 3D printing project for automotive spare parts. Toyota is now utilizing HP Multi Jet Fusion 3D printing technology to produce stock parts, which are sold alongside traditionally manufactured spares.
- Stratasys Ltd (U.S.)
- Desktop Metal, Inc. (ETEC) (U.S.)
- Dassault Systèmes S.E · France
- EOS GmbH · Germany
- ExOne Operating, LLC (U.S.)
- Autodesk, Inc. (U.S.)
- Hoganas AB · Sweden
- Proto Labs, Inc. (U.S.)
- Formlabs Inc. (U.S.)
- Markforged Holding Corporation (U.S.)
- MATERIALISE NV · Belgium
- Ultimaker B.V. · Netherland
- IC3D, Inc. (U.S.)
- Moog Inc. (U.S.)
- Zortrax S.A. · Poland
Frequently asked questions
The global automotive 3D printing market size was valued at $3.7 billion in 2024.
Cite this report
Meticulous Research. (2024). Automotive 3D Printing Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRSE - 1041355). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/automotive-3d-printing-market-6038