Automotive Intrusion Detection & Prevention Systems (IDPS) Market (2026-2036)
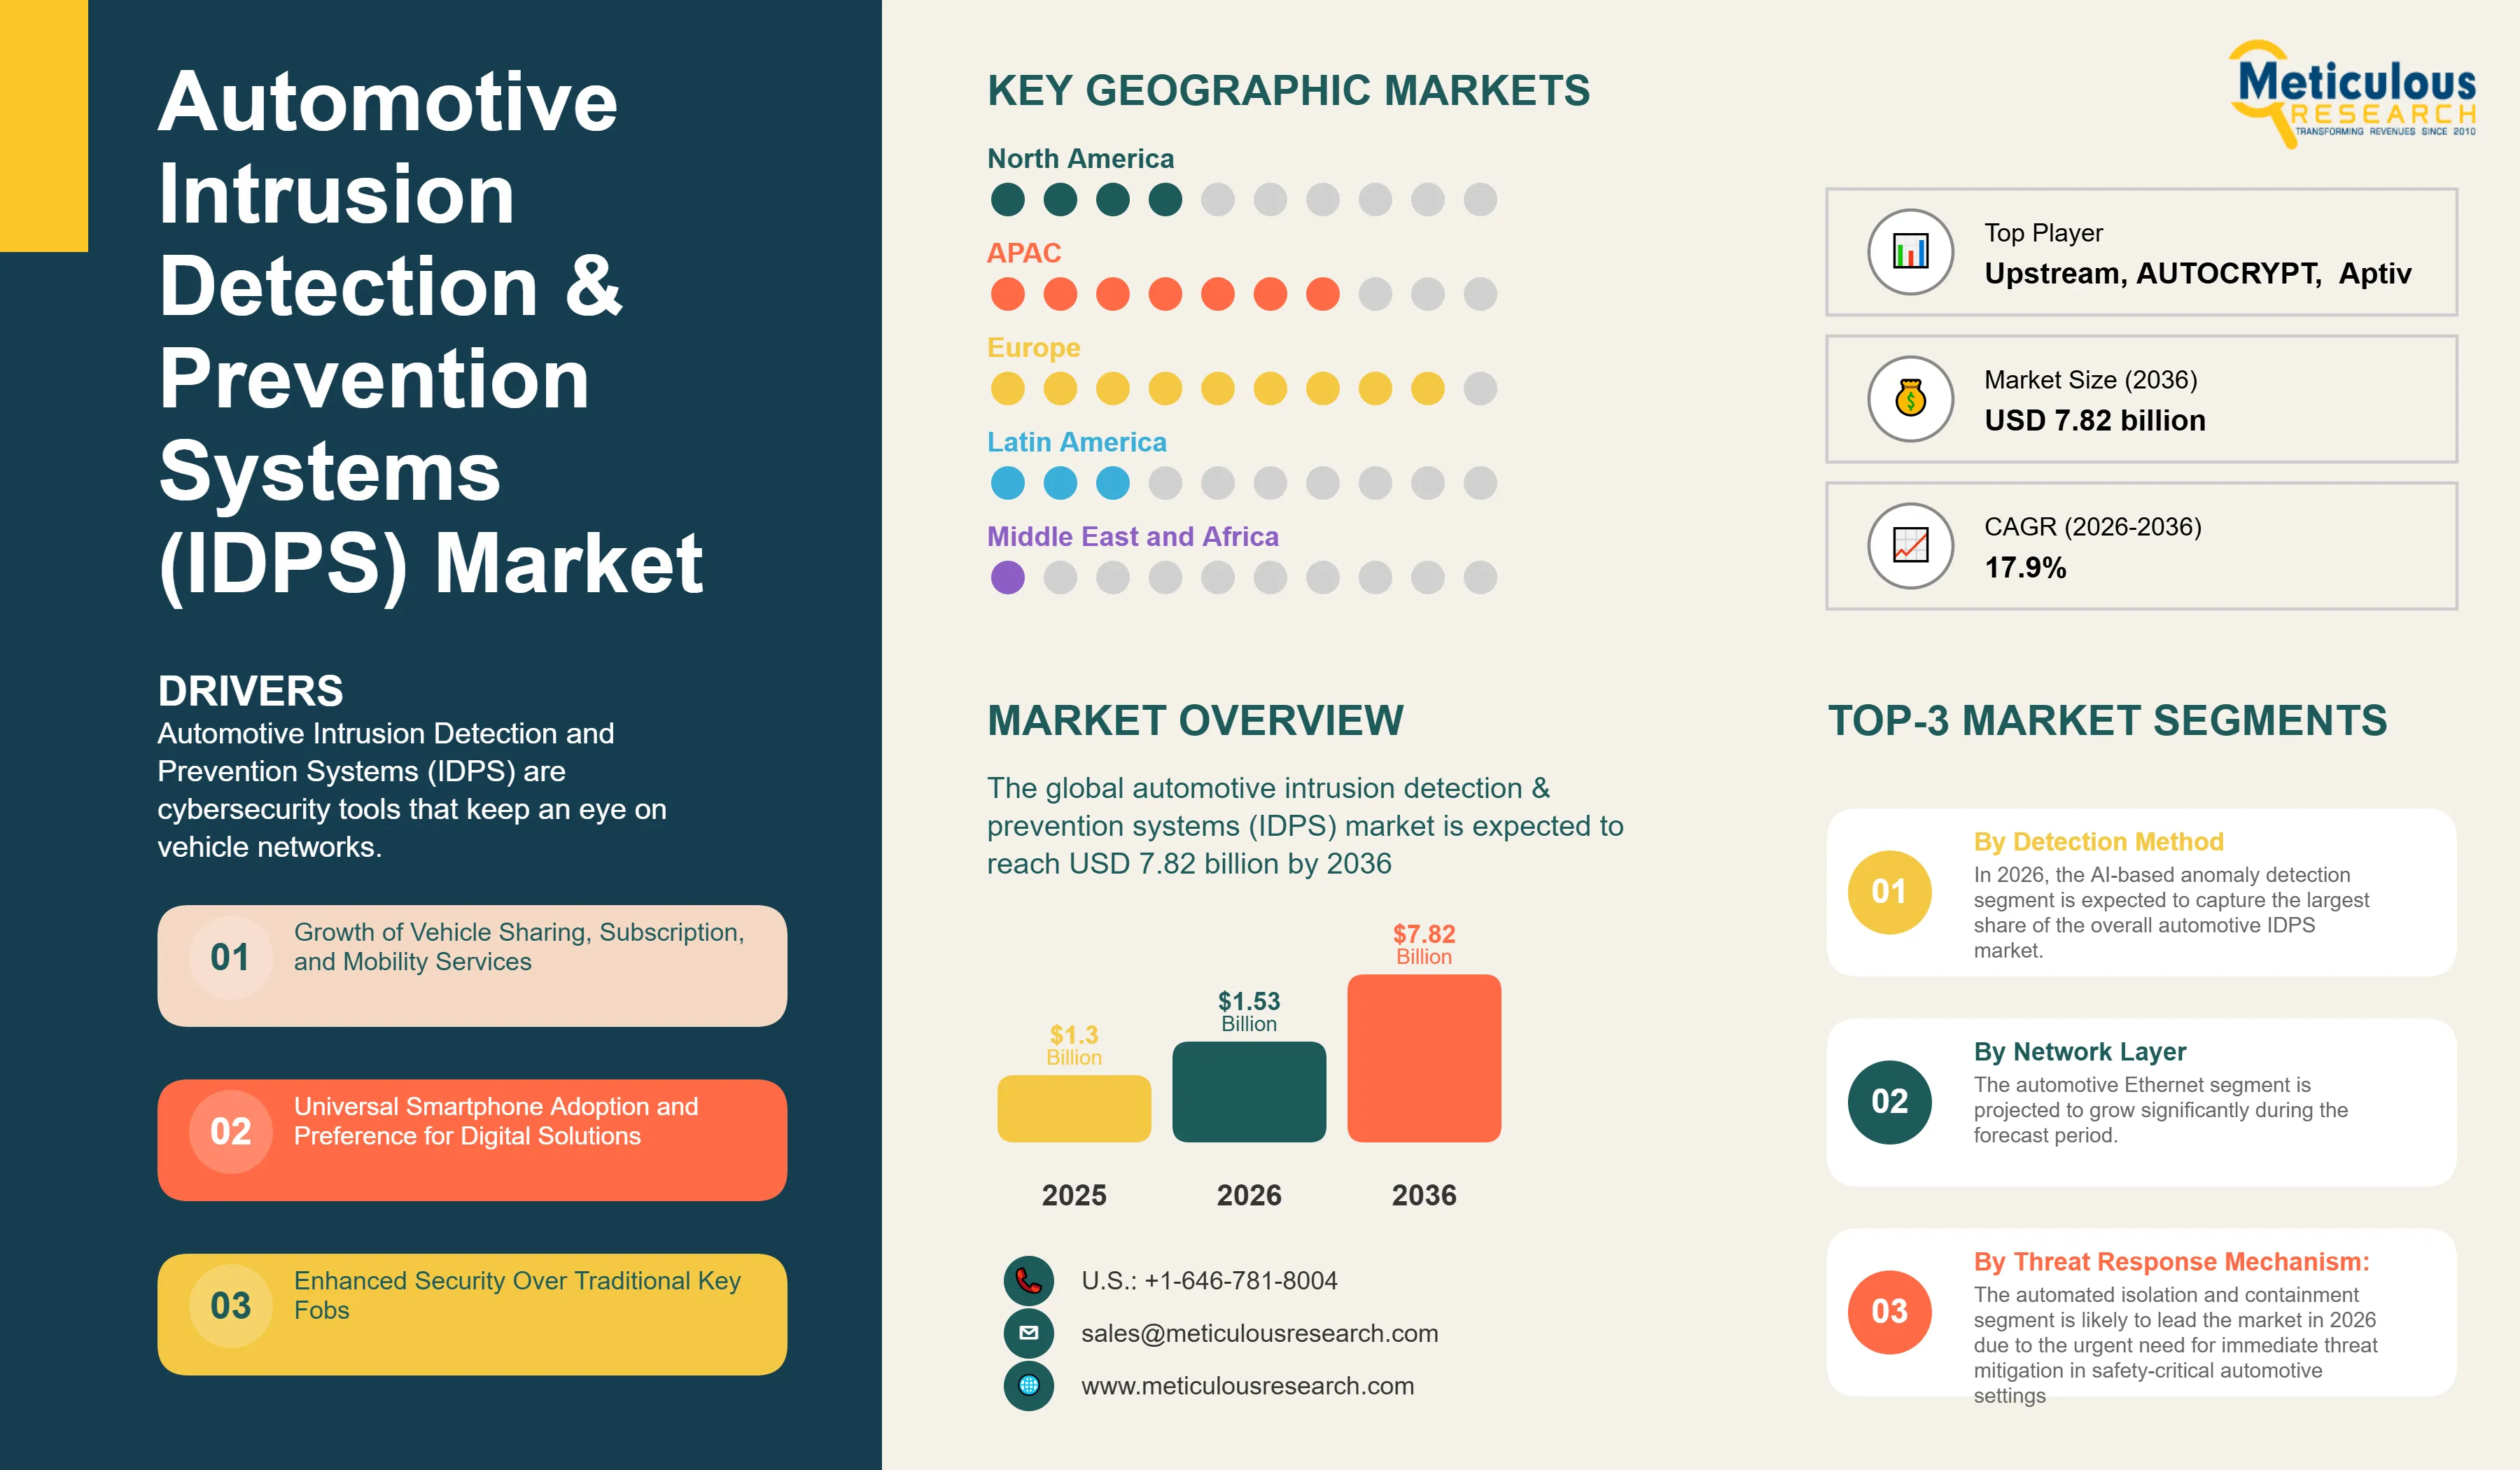
The global automotive intrusion detection & prevention systems (IDPS) market is expected to reach USD 7.82 billion by 2036 from USD 1.53 billion in 2026, at a CAGR of 17.9% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041663
- Base year
- 2025
- 2026 · ESTIMATED
- $1.53B
- 2036
- $7.82B
- CAGR 2026–2036
- 17.9%
2025 baseline · 2026–2036 forecast at 17.9% CAGR · hover a bar for the value
Key highlights
In 2026, Europe is estimated to account for the largest share of the global automotive IDPS market, driven by UNECE WP.29 regulations requiring security monitoring and threat detection capabilities, premium vehicle concentration implementing comprehensive security architectures, and strong automotive cybersecurity engineering expertise.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by massive connected and electric vehicle production requiring security monitoring, Chinese cybersecurity regulations mandating threat detection, and growing awareness of automotive cyber risks.
Based on detection method, the AI-based anomaly detection segment is estimated to hold the largest share of the market in 2026, driven by superior capability to identify unknown threats, adaptive learning from fleet data, and effectiveness against zero-day attacks.
Based on network layer, the automotive Ethernet segment is expected to witness significant growth during the forecast period, owing to high bandwidth enabling detailed traffic inspection and increasing adoption in next-generation vehicle architectures.
Based on threat response mechanism, the automated isolation and containment segment is estimated to dominate the market in 2026, driven by need for immediate threat mitigation without human intervention and safety-critical nature of automotive systems.
Based on deployment architecture, the distributed IDPS with centralized management segment is expected to account for the largest share, fueled by optimal balance between local threat response speed and fleet-wide security visibility.
The gateway-integrated IDPS segment is expected to grow at a significant CAGR during the forecast period, driven by strategic positioning at network boundaries and critical role in multi-domain vehicle architectures.
The U.S. automotive IDPS market is projected to grow at a CAGR of around 17% during the forecast period 2026 to 2036, driven by increasing cybersecurity awareness, NHTSA guidance on security monitoring, and autonomous vehicle development requiring comprehensive threat detection.
China is expected to lead the Asia-Pacific automotive IDPS market, driven by government cybersecurity regulations for intelligent connected vehicles, massive EV production volumes with extensive connectivity, and domestic cybersecurity technology development.
In 2026, Germany is projected to account for the largest share of the European automotive IDPS market, driven by premium automakers BMW, Mercedes-Benz, and Audi implementing sophisticated security monitoring systems and early UNECE WP.29 compliance leadership.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 1.53 Billion |
| Revenue Forecast in 2036 | USD 7.82 Billion |
| Growth Rate | CAGR of 17.9% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 280 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | Detection Method, Network Layer, Threat Response Mechanism, Deployment Architecture, Detection Scope, ECU Integration, Vehicle Segment, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Germany, U.K., France, Italy, Spain, Sweden, China, Japan, South Korea, India, Australia, Brazil, Mexico, Saudi Arabia, UAE, South Africa |
| Key Companies Profiled | Continental AG, Aptiv PLC, Argus Cyber Security (Continental), Upstream Security, GuardKnox Cyber Technologies Ltd., Karamba Security, AUTOCRYPT Co. Ltd., Cymotive Technologies (Stellantis/Volkswagen Group), ESCRYPT GmbH (ETAS/Bosch), Arilou Technologies (NNG), NXP Semiconductors N.V., Infineon Technologies AG, STMicroelectronics N.V., Robert Bosch GmbH, Denso Corporation, Vector Informatik GmbH, ETAS GmbH (Bosch), Panasonic Automotive Systems Co. Ltd., Trend Micro Inc., Cisco Systems Inc. |
Report overview
Segments covered: detection method, network layer, threat response mechanism, deployment architecture, threat response, centralized management.
Automotive Intrusion Detection and Prevention Systems (IDPS) are cybersecurity tools that keep an eye on vehicle networks. They spot harmful activities or unusual behaviors. These systems automatically react to threats by blocking, isolating, or reducing cyber attacks in real time. Their goal is to safeguard vehicles from unauthorized access, stop malware injection, identify compromised Electronic Control Units (ECUs), block command injection attacks, and uphold the operational integrity of safety-critical systems.
These AI-powered systems use advanced technologies such as anomaly detection algorithms, signature-based threat identification, machine learning for behavioral analysis, real-time network traffic monitoring, and automated threat response methods. IDPS can track several vehicle network protocols at once, including CAN, CAN-FD, Automotive Ethernet, FlexRay, and LIN. They detect known attack patterns and zero-day threats, recognize unusual ECU behaviors that might indicate a compromise, and implement automated countermeasures to isolate affected components. The systems generate security alerts for centralized monitoring and keep detailed security logs for forensic analysis.
The system offers constant security monitoring that goes beyond simple defenses. It adjusts to new threats through machine learning and enables quick responses to reduce the impact of attacks. It also supports compliance with cybersecurity lifecycle requirements and provides security visibility across vehicle fleets. This helps automakers protect connected and autonomous vehicles from increasingly sophisticated cyber threats, comply with UNECE WP.29 security monitoring requirements, respond quickly to security incidents, and maintain consumer trust in vehicle safety and data protection.
Automotive Intrusion Detection and Prevention Systems (IDPS) play a crucial role in safeguarding modern connected, electric, and autonomous vehicles from cyber threats. While traditional security measures like firewalls, access controls, and cryptographic authentication help block many attacks, determined hackers can exploit zero-day vulnerabilities. They may also conduct complex social engineering, compromise supply chains, or use insider access to break into vehicle security. Once attackers breach vehicle networks, they can manipulate safety-critical functions, steal sensitive data, deploy ransomware, or coordinate attacks across multiple vehicles. IDPS technology delivers essential security visibility and active defense capabilities. It continuously monitors for malicious activities, detects ongoing attacks, and automatically responds to contain threats before they cause significant damage. This layered defense approach combines preventive security controls with detection and response features, creating strong security systems that are vital for safety-critical automotive applications.
Several significant trends are changing the automotive IDPS market. These include the shift from signature-based detection to AI-driven behavioral analysis that can identify unknown threats. There is also rapid progress in real-time network traffic analysis capable of handling gigabit Ethernet speeds. Additionally, vehicle IDPS is increasingly integrated with Security Operations Centers (SOC), allowing for fleet-wide threat intelligence. The market has expanded from isolated gateway monitoring to wide-ranging detection across vehicle architectures. A combination of regulatory requirements for security monitoring, rising sophistication of cyber threats that demand active defenses, increasing vehicle connectivity that broadens attack surfaces, and AI/machine learning technologies that enhance real-time threat detection has evolved IDPS from experimental ideas into essential security components.
The automotive IDPS market is quickly evolving toward comprehensive, AI-driven security monitoring platforms that offer visibility across entire fleets and coordinated response capabilities. Modern systems extend far beyond simple anomaly detection. They create complex security ecosystems, including distributed sensors that monitor every segment of vehicle networks. They utilize machine learning models trained on millions of patterns of normal operation. These systems also aggregate threat intelligence across fleets, automate response protocols based on specific threat types, and integrate with vehicle SOC platforms for human analyst oversight. Continuous updates to these models include new threat signatures and attack patterns. The shift from disconnected intrusion detection to integrated security monitoring platforms marks a major change in automotive cybersecurity strategies.
AI and machine learning technologies are advancing rapidly. They enable IDPS systems to spot increasingly subtle attack indicators while reducing false positives, which could erode driver trust and system reliability. Modern systems use multiple detection methods at once. These include signature detection that matches known attack patterns, anomaly detection for identifying deviations from usual behaviors, protocol validation to ensure compliance with network standards, behavioral analysis to spot suspicious ECU activity, and statistical correlation for recognizing complex multi-stage attacks. Deep learning models can identify attack patterns across vast arrays of parameters—an impossible task for manually created rules—while unsupervised learning can uncover new threat indicators without needing labeled training data. Edge AI processing allows these advanced detection algorithms to run on the vehicles themselves. This enables immediate threat response without relying on cloud connectivity.
The combination of automotive IDPS with vehicle Security Operations Centers and fleet management platforms is forming a complete security monitoring system. Modern setups link vehicle-generated security data with centralized analysis platforms. This allows security analysts to oversee thousands of vehicles at once, identify coordinated fleet attacks, update IDPS detection models, manage investigation and response activities, and maintain thorough security incident records for compliance. This fleet-wide visibility changes automotive cybersecurity from individual vehicle defenses to coordinated protection across fleets, supporting shared threat intelligence and collective learning.
Report infographic
Market dynamics
4 factors across 2 forcesRegulatory Mandates for Security Monitoring and Threat Detection
Global automotive cybersecurity regulations now require ongoing security monitoring and threat detection as key vehicle security needs. UNECE WP.29 regulations ask automakers to show they can detect cyber attacks, monitor security events throughout a vehicle's life, and respond to security incidents. These rules specifically expect vehicles to have intrusion detection to spot unauthorized access and harmful activities. The ISO/SAE 21434 automotive cybersecurity standard also highlights the importance of security monitoring as a critical control for managing cybersecurity risks in production vehicles. Regulatory frameworks understand that just preventive security measures cannot fully protect against determined attackers and new vulnerabilities. This makes detective controls like IDPS crucial for overall security. Compliance requires clear monitoring abilities, including real-time threat detection, logging security events, having incident response plans, and connecting with cybersecurity management systems. Automakers without IDPS capabilities struggle with compliance, face challenges in type approval, and could have trouble accessing markets. This regulatory push creates a key market demand regardless of cost, ensuring that IDPS will become standard in various vehicle segments and markets as regulations spread worldwide.
Escalating Sophisticated Cyber Threats Targeting Vehicle Networks
The growing complexity and number of cyber attacks specifically aimed at automotive systems are driving the urgent need for active threat detection and response tools. Security researchers have revealed many attack methods including remote CAN bus injection that manipulates braking and steering, telematics exploitation that enables vehicle tracking and control, infotainment breaches that provide entry points into networks, key fob relay attacks that bypass access controls, and coordinated assaults on whole fleets. These attacks take advantage of weaknesses in vehicle network protocols, software, supply chain components, and day-to-day operations. Traditional preventive measures like access controls and firewalls offer some protection but cannot stop all intrusions. Attackers constantly find new weaknesses and come up with fresh techniques. IDPS gives critical security visibility by identifying when preventive measures fail, detecting attacks before they cause major harm, and allowing for a quick response to contain threats. The automotive industry's long product lifecycles (10-15+ years) mean vehicles must stay secure against threats that may not have been present when they were designed. This requires flexible security monitoring capabilities provided by IDPS. As vehicles become more connected and autonomous, the results of successful cyber attacks can be devastating, making proactive threat detection a necessity rather than a choice.
Table of contents
16 chapters · 185 sections · 280 pages · click to expandGeographic analysis
Europe
Largest shareIn 2026, Europe is anticipated to hold the largest share of the global automotive IDPS market. European leadership comes from UNECE WP.29 regulations that explicitly require security monitoring and threat detection capabilities, a concentration of premium vehicles implementing detailed security architectures, strong automotive cybersecurity expertise, particularly in Germany, established automotive cybersecurity firms like ESCRYPT, Argus, and Vector, and a cultural focus on systematic security engineering. German automakers, including BMW, Mercedes-Benz, Audi, Volkswagen Group, and Porsche, implement advanced IDPS systems integrated with broader vehicle security frameworks. European tier-one suppliers such as Continental, Bosch, Aptiv, and ZF incorporate IDPS capabilities into ECU and gateway products. This regulatory-driven security culture ensures continued dominance in the European market.
Asia-Pacific
Fastest growthAsia-Pacific is set to experience the highest growth rate during the forecast period, driven by a surge in connected and electric vehicle production that requires security monitoring. Chinese cybersecurity regulations for intelligent connected vehicles mandate threat detection, while growing awareness of cyber risks among automakers and consumers, along with domestic cybersecurity technology development, fuels this growth. China, in particular, will lead regional expansion through government requirements for security monitoring in intelligent connected vehicles, extensive EV production that incorporates significant connectivity, and local cybersecurity companies like AUTOCRYPT developing automotive IDPS solutions. Japanese and Korean automakers are also increasing IDPS adoption in response to cybersecurity needs.
North America
North America represents a considerable market, driven by rising cybersecurity awareness, NHTSA guidance that promotes security monitoring, the development of autonomous vehicles that require thorough threat detection, and cybersecurity companies like Upstream and Karamba, along with strong automotive cybersecurity research capabilities.
Competitive landscape
- Continental AG · Germany
- Aptiv PLC · Ireland
- Argus Cyber Security (Continental) · Israel/Germany
- Upstream Security (Israel/U.S.)
- GuardKnox Cyber Technologies Ltd. · Israel
- Karamba Security (U.S./Israel)
- AUTOCRYPT Co. Ltd. · South Korea
- Cymotive Technologies (Stellantis/Volkswagen Group) · Germany/Netherlands
- ESCRYPT GmbH (ETAS/Bosch) · Germany
- Arilou Technologies (NNG) · Israel/Hungary
- NXP Semiconductors N.V. · Netherlands
- Infineon Technologies AG · Germany
- STMicroelectronics N.V. · Switzerland
- Robert Bosch GmbH · Germany
- Denso Corporation · Japan
- Vector Informatik GmbH · Germany
- ETAS GmbH (Bosch) · Germany
- Panasonic Automotive Systems Co. Ltd. · Japan
- Trend Micro Inc. · Japan
- Cisco Systems Inc. (U.S.)
Frequently asked questions
The automotive intrusion detection & prevention systems market is expected to grow from USD 1.53 billion in 2026 to USD 7.82 billion by 2036
Cite this report
Meticulous Research. (2026). Automotive Intrusion Detection & Prevention Systems (IDPS) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041663). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/automotive-intrusion-detection-and-prevention-systems-market-6346