Automotive Transmission Market (2025-2032)
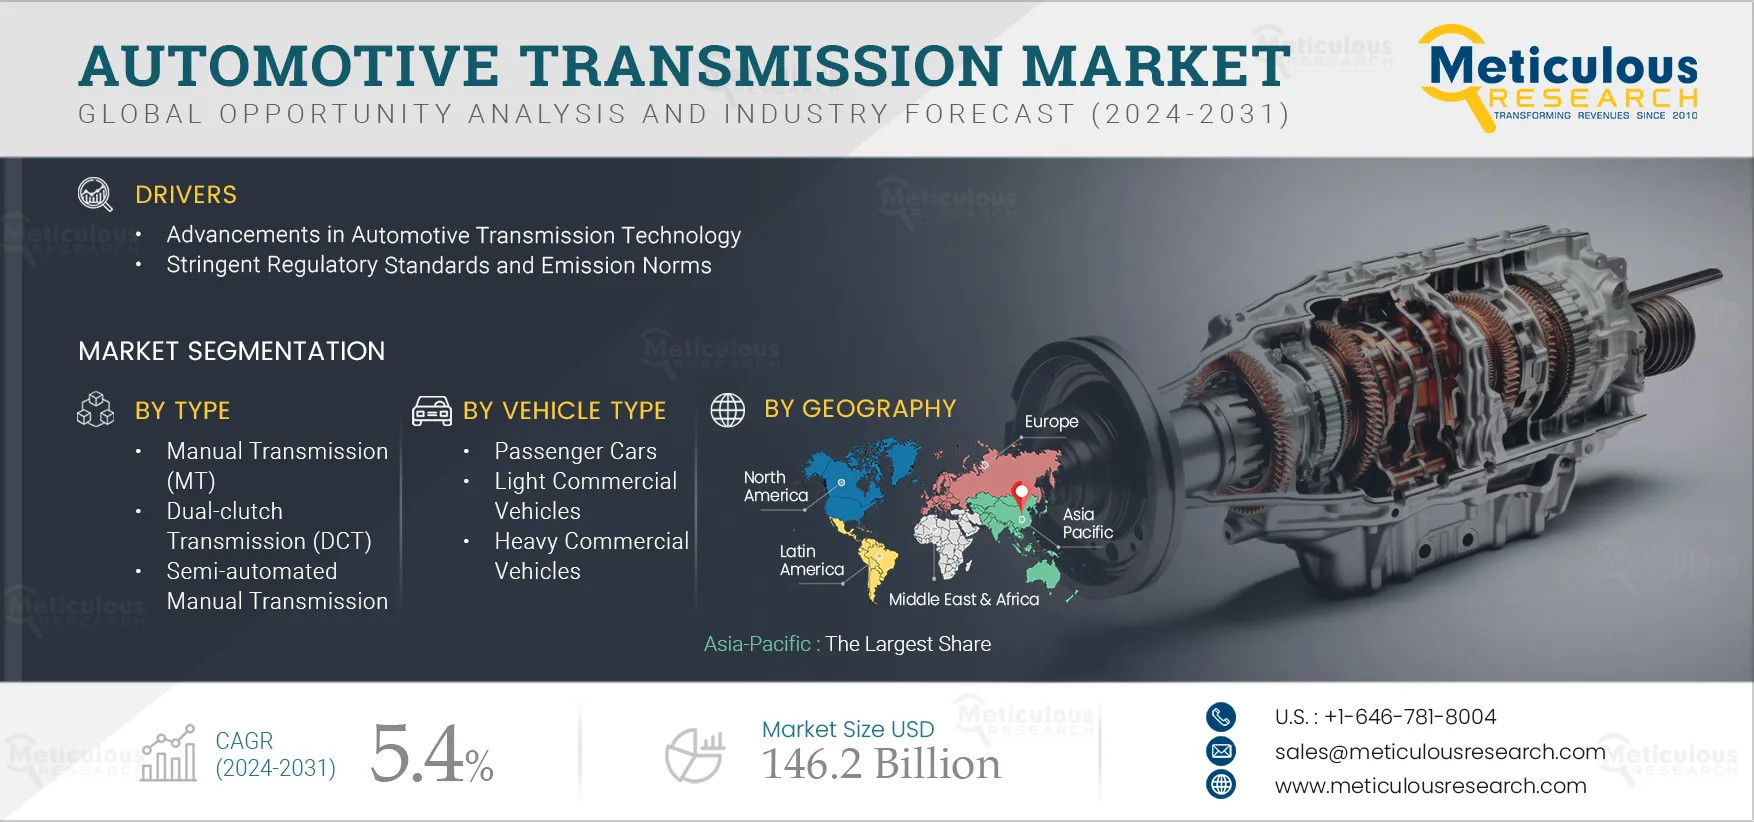
The Automotive Transmission Market is expected to reach $146.2 billion by 2032, at a CAGR of 5.4% from 2025 to 2032.
- Published
- Sep 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041149
- Base year
- 2024
- 2032 · FORECAST
- $146.2B
- 2032
- $146.2B
- CAGR 2025–2032
- 5.4%
2024 baseline · 2025–2032 forecast at 5.4% CAGR · hover a bar for the value
Key highlights
By Type: in 2025, the Manual Transmission Segment to Dominate the Automotive Transmission Market
By Engine Type: in 2025, the Petrol Engine Segment to Dominate the Automotive Transmission Market
By Vehicle Type: in 2025, the Passenger Cars Segment to Dominate the Automotive Transmission Market
By Sales Channel: in 2025, the Original Equipment Manufacturers Segment to Dominate the Automotive Transmission Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR | 5.4% |
| Market Size | USD above USD 146.2 Billion by 2032 |
| Segments Covered | By Type · Manual Transmission (MT) · Automated Manual Transmission (AMT) · Automatic Transmission (AT) · Continuously Variable Transmission (CVT) · Dual-clutch Transmission (DCT) · Semi-automated Manual Transmission · By Engine Type · Petrol Engines · Diesel Engines · By Vehicle Type · Passenger Cars · Light Commercial Vehicles · Heavy Commercial Vehicles · Trucks · Buses · By Sales Channel · Original Equipment Manufacturers (OEMs) · Aftermarket |
| Countries Covered | Europe (Germany, U.K., France, Italy, Spain, Netherlands, Switzerland, Sweden, Denmark, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia & New Zealand, Indonesia, Thailand, Vietnam, Malaysia, Singapore, and Rest of Asia- Pacific), North America (U.S., Canada), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Israel, and Rest of Middle East & Africa) |
| Key Companies | ZF Friedrichshafen AG (Germany), Magna International Inc. (Canada), BorgWarner Inc. (U.S.), Continental AG (Germany), Eaton Corporation plc (U.S.), Allison Transmission Holdings, Inc. (U.S.), Marelli Holdings Co., Ltd. (Japan), AISIN Group (Japan), Bonfiglioli S.P.A (China), Hyundai Transys Inc. (South Korea), Musashi Seimitsu Industry Co., Ltd. (Japan), Schaeffler AG (Germany), Vietesco Technologies Group AG (Germany), GKN plc (U.K.), and KATE LLC (Russia) |
Report overview
Segments covered: type, engine type, vehicle type, sales channel. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
The growth of the automotive transmission market is driven by increasing advancements in automotive transmission technology and stringent regulatory standards and emission norms. However, the complexity of transmission systems and fluctuations in raw material prices may restrain market growth.
Furthermore, the rising focus on lightweight and highly efficient materials among automakers, coupled with the integration of AI and machine learning with automotive transmission systems, is expected to create market growth opportunities. However, supply chain disruptions pose a significant challenge to the market’s growth.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Advancements in Automotive Transmission Technology
Advanced transmission technologies, such as continuously variable transmissions (CVTs), dual-clutch transmissions (DCTs), and automated manual transmissions (AMTs), offer improved fuel efficiency compared to traditional automatic transmissions. This efficiency gain is a significant selling point for both consumers and automakers, particularly in an era where environmental concerns and fuel economy standards are crucial. New transmission technologies often offer better performance characteristics, including quicker shift times, smoother gear changes, and optimized power delivery. These improvements enhance the driving experience, making vehicles more attractive to consumers, particularly those interested in high-performance vehicles.
Moreover, modern transmissions are increasingly becoming integrated with advanced driver assistance systems (ADAS) and vehicle connectivity features. These integrations can enable functionalities such as adaptive cruise control, automatic emergency braking, and predictive shifting algorithms that optimize gear selection based on real-time driving conditions. Advancements in materials, lubricants, and manufacturing processes contribute to the durability and reliability of modern transmission systems. This is crucial for automakers seeking to minimize warranty claims and improve the long-term ownership experience for consumers. Such advancements in transmission technology are expected to drive the growth of the automotive transmission market during the forecast period.
Stringent Regulatory Standards and Emission Norms
Regulatory standards and emission norms significantly influence the automotive transmission market's development. Stringent fuel efficiency standards mandated by regulatory bodies worldwide compel automakers to innovate and produce vehicles equipped with more efficient transmission systems. Advanced transmission technologies, including continuously variable transmissions (CVTs), dual-clutch transmissions (DCTs), and sophisticated automatic transmissions, contribute to improving fuel economy by optimizing gear ratios and reducing frictional losses. Moreover, as the automotive industry shifts towards electrification and hybridization, transmission systems for electric and hybrid vehicles play a pivotal role in maximizing energy efficiency. Electric vehicles (EVs) typically utilize single-speed transmissions or direct-drive systems. In contrast, hybrid vehicles employ various configurations such as series, parallel, or power-split transmissions to optimize the utilization of internal combustion engines and electric motors.
Additionally, the alignment of regulatory standards across various regions encourages the standardization of transmission technologies, enabling automakers to develop vehicles that comply with multiple regulatory frameworks. This standardization promotes economies of scale in production, ultimately resulting in cost reductions for manufacturers and consumers.
Table of contents
12 chapters · 120 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Manual Transmission | Automated manual transmission |
| By Engine Type | Petrol Engine | Petrol engines |
| By Vehicle Type | Passenger Cars | Passenger cars |
| By Sales Channel | Original Equipment Manufacturers | Original equipment manufacturers |
By Type
- Furthermore, the automated manual transmission segment is sub-segmented into automatic transmission, continuously variable transmission, and dual-clutch transmission.
- The manual transmission segment is expected to account for the largest share of 48.0% of the global automotive transmission market.
- This segment's large market share can be attributed to the higher fuel efficiency offered by manual transmissions compared to automatic alternatives.
- With growing concerns regarding fuel economy and environmental sustainability, some consumers opt for manual transmissions to optimize fuel efficiency and reduce their carbon footprint.
- This trend is particularly pronounced in regions with high fuel prices or a strong emphasis on environmental consciousness, potentially driving market growth in these areas.
- Moreover, manual transmissions are generally simpler in design and have fewer components compared to automatic transmissions.
- This simplicity often translates to lower maintenance and repair costs over the lifespan of the vehicle.
- However, the automated manual transmission segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment can be attributed to the benefits offered by automated transmissions, which combine the convenience of automatic transmissions with the engagement and control of manual transmissions.
- Furthermore, various key players are launching various automated manual transmissions, contributing to the market’s growth.
- For instance, in February 2025, ZF Friedrichshafen AG (Germany) announced the launch of the first PowerLine 8-speed automatic transmissions at its South Carolina manufacturing facility.
- As part of a USD 200 million investment unveiled in 2021, the company aims to increase production to 200,000 transmissions per year by 2025 to meet demand from US commercial vehicle manufacturers.
- Additionally, in January 2025, Tata Motors (India) launched the first-ever CNG cars equipped with automatic manual transmission (AMT) technology.
By Engine Type
- The Petrol Engine Segment to Dominate the Automotive Transmission Market
- The petrol engines segment is expected to account for the larger share of 56.0% of the global automotive transmission market.
- This segment's growth can be attributed to the compatibility of different types of automated transmissions, such as automatic transmissions and continuously variable transmissions (CVTs), with petrol engines.
- Automated transmissions play a crucial role in enhancing the performance of petrol engines by optimizing gear shifts for maximum power delivery and fuel efficiency.
- Moreover, features like dual-clutch transmissions (DCTs) offer quick gear changes, thereby improving acceleration and overall driving dynamics.
- These performance benefits are particularly appealing to enthusiasts and drivers who prioritize responsive and engaging driving experiences.
- These factors drive the demand for petrol engine vehicles equipped with automated transmissions.
- Moreover, the petrol engines segment is projected to register the highest CAGR during the forecast period.
By Vehicle Type
- The Passenger Cars Segment to Dominate the Automotive Transmission Market
- Furthermore, the heavy commercial vehicles segment is sub-segmented into trucks and buses.
- The passenger cars segment is expected to account for the largest share of 47.0% of the global automotive transmission market.
- The large market share of this segment can be attributed to the ongoing advancements in the automotive industry, which is experiencing rapid technological progress, particularly in transmission systems.
- Emerging transmission technologies like continuously variable transmissions (CVTs), dual-clutch transmissions (DCTs), and automatic transmissions are gaining prominence in passenger cars due to their higher efficiency, performance, and comfort over traditional manual transmissions.
- Furthermore, passenger cars constitute the largest segment of the automotive market in terms of both production and sales volume.
- As a result, the demand for transmissions for passenger cars is significantly higher than that of other vehicle segments, such as commercial vehicles or off-road vehicles.
- Moreover, the passenger cars segment is projected to register the highest CAGR during the forecast period.
By Sales Channel
- The original equipment manufacturers segment is expected to account for the larger share of 85.0% of the global automotive transmission market.
- The large market share of this segment can be attributed to increased expansion efforts by original equipment manufacturers (OEMs) by targeting emerging markets and diversifying their geographic footprint in the automated transmission market.
- These efforts involve adapting transmission offerings to align with regional preferences, regulatory environments, and infrastructure conditions.
- Moreover, OEMs may establish local manufacturing facilities, distribution networks, and marketing strategies to effectively penetrate new markets.
- Additionally, OEMs frequently collaborate with transmission component suppliers and technology companies to integrate cutting-edge features into their vehicles.
- Such partnerships enable OEMs to access specialized expertise, reduce development costs, and expedite time-to-market for new transmission technologies.
- Moreover, the original equipment manufacturers segment is projected to register the highest CAGR during the forecast period.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of 41.0% of the global automotive transmission market. The Asia-Pacific region is undergoing rapid urbanization and economic growth, rising disposable incomes, and expanding middle-class populations. These factors contribute to increased vehicle ownership and replacement cycles, driving demand for both passenger and commercial vehicles. The growth in the vehicle market is increasing the demand for automotive transmissions. Furthermore, in Asia-Pacific countries, there is a growing preference for automatic transmissions due to factors such as increasing traffic congestion in urban areas, the convenience of driving in stop-and-go traffic, and a desire for smoother driving experiences. This trend is driving demand for automatic transmission systems in passenger vehicles, particularly in larger cities. Stringent regulations across Asia-Pacific have also incentivized companies to adopt more efficient transmission systems. Additionally, the increasing automotive sales, especially in countries like China, India, Japan, and South Korea, are anticipated to positively impact the growth of the automotive transmission market in Asia-Pacific during the forecast period. Additionally, various market players are launching initiatives to drive market development. For instance, in September 2024, Aisin Corporation (Japan) showcased a range of electrification technologies and innovations at the 2024 Detroit Auto Show. These include advanced axles for enhanced energy efficiency, a 1-motor Hybrid Transmission, and a 2-motor Hybrid System for improved performance. Moreover, the market in Asia-Pacific is projected to register the highest CAGR of 7.0% during the forecast period.
Competitive landscape
- June 2024
Yanfeng Auto International Automotive Technology Co., Ltd., a leading Chinese automotive parts supplier, collaborated with IBM to leverage Data, AI, and Intelligent Automation Software for accelerating digital and intelligent transformation. Through this collaboration, the company integrates advanced technologies such as AI into the manufacturing of automotive transmission systems.
- July 2022
BluE Nexus (Japan), Aisin (Japan), and Denso Corporation (Japan) collaborated on a 1-motor hybrid transmission for the new Toyota Crown Crossover RS version. This transmission combines a Direct Shift-6AT, drive motor, and inverter into a single unit, ensuring excellent acceleration and fuel efficiency.
- March 2022
Tata (India) launched the Altroz, a premium hatchback featuring a dual-clutch automatic transmission.
- ABB Ltd. · Switzerland
- Schneider Electric SE · France
- Siemens AG · Germany
- Rockwell Automation Inc. (U.S.)
- Allied Motion Technologies, Inc. (U.S.)
- AMETEK Inc. (U.S.)
- Johnson Electric Holdings Limited · Hong Kong
- Nidec Motor Corporation · Japan
- Franklin Electric Co., Inc. (U.S.)
- Regal Rexnord Corporation (U.S.)
- Arc Systems Inc. (U.S.)
- Denso Corporation · Japan
- Emerson Electric Co. (U.S.)
- Nidec Corporation · Japan
- Oriental Motor USA Corp · Germany
Frequently asked questions
The global automotive transmission market is expected to reach $146.2 billion by 2032, at a CAGR of 5.4% from 2025–2032.
Cite this report
Meticulous Research. (2024). Automotive Transmission Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRAUTO - 1041149). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/automotive-transmission-market-5832