Anti-Drone (Counter-UAS) Market (2026-2036)
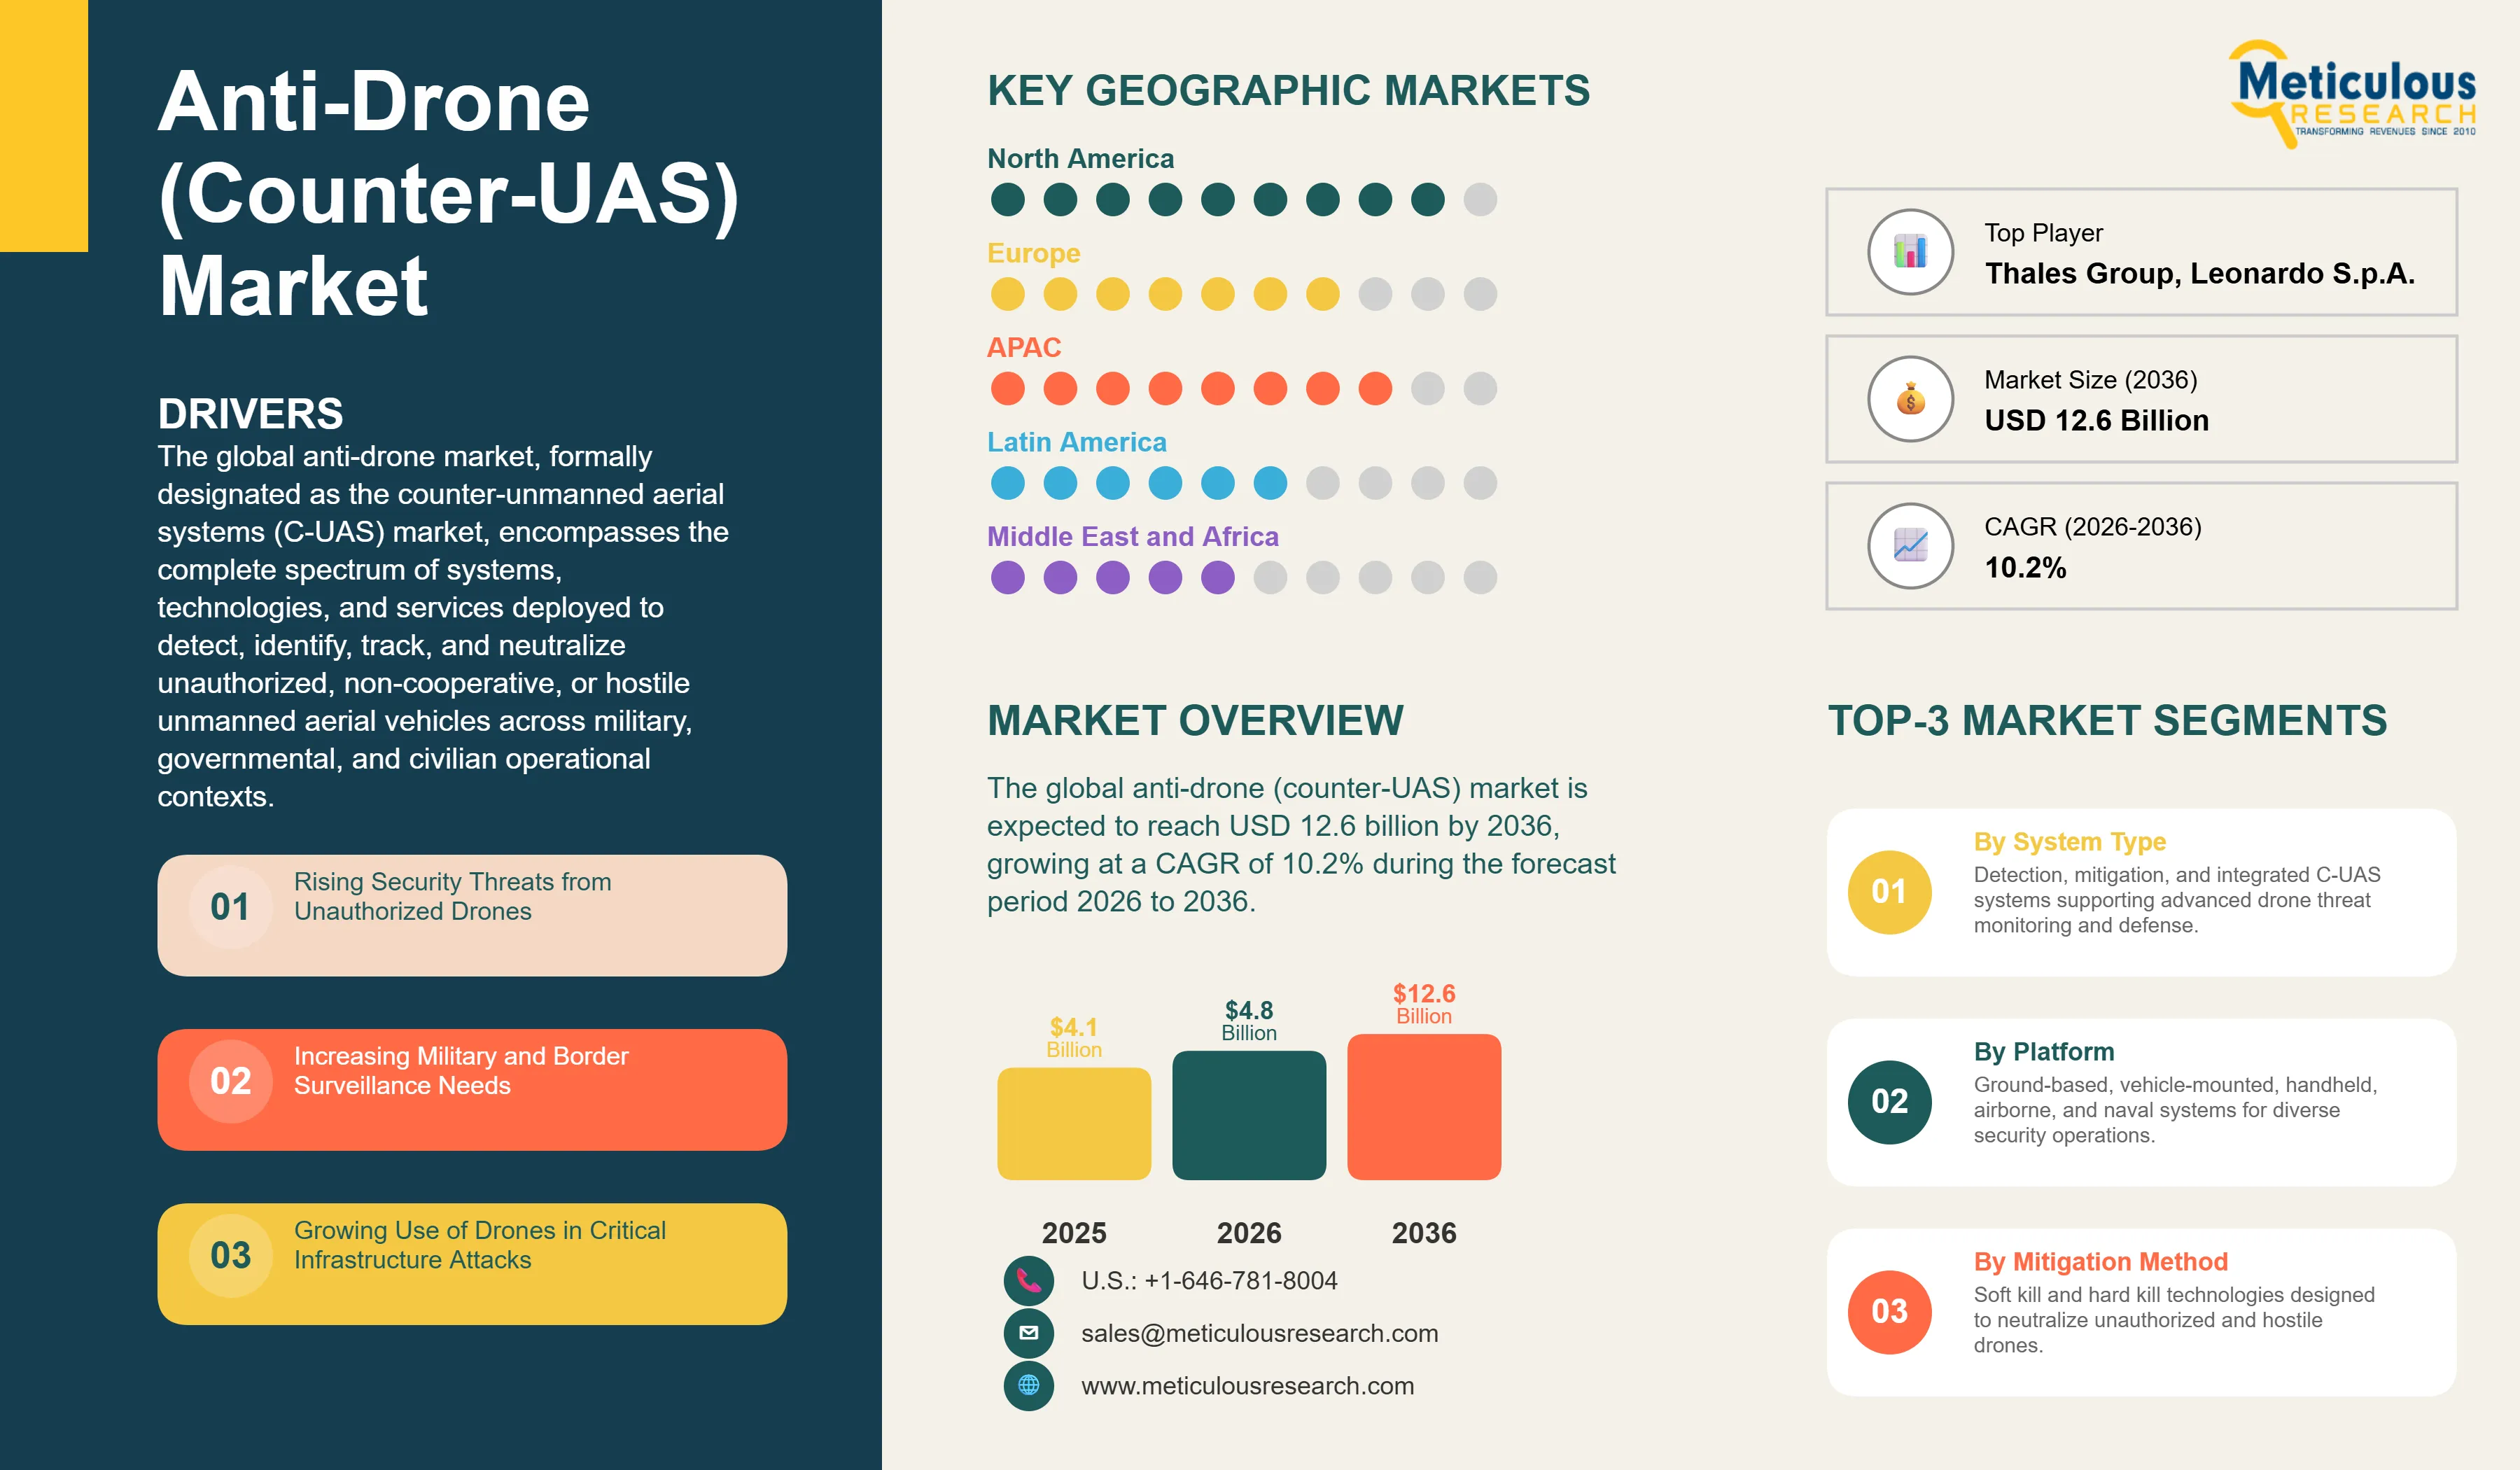
The global anti-drone (counter-UAS) market was valued at USD 4.1 billion in 2025. This market is expected to reach USD 12.6 billion by 2036 from an estimated USD 4.8 billion in 2026, growing at a CAGR of 10.2% during the forecast period 2026 to 2036.
- Published
- May 2026
- Pages
- 302
- Format
- PDF + Excel
- Report ID
- MR-1986
- Base year
- 2025
- 2025 · BASELINE
- $4.10B
- 2036
- $12.60B
- CAGR 2026–2036
- 10.2%
2025 baseline · 2026–2036 forecast at 10.2% CAGR · hover a bar for the value
Key highlights
The global counter-UAS market is projected to reach USD 12.6 billion by 2036, growing at a CAGR of 10.2% from 2026 to 2036.
The global anti-drone market was valued at USD 4.1 billion in 2025 and is estimated to reach USD 4.8 billion in 2026. According to the U.S. Government Accountability Office (GAO) 2025 assessment of C-UAS programs, the U.S. Department of Defense alone operated more than 35 distinct counter-drone programs across all service branches as of early 2025, reflecting the systemic and multi-domain scale of defense investment in this technology area.
North America is expected to dominate the global anti-drone market with the largest market share in 2026. The United States remains the single largest national investor in counter-UAS technology. As of early 2026, the U.S. has significantly intensified investment in Counter-Unmanned Aircraft Systems (C-UAS), with the Department of Defense (DoD) requesting around $75 billion for drones and counter-drone technologies in its FY2027 budget proposal. This marks a dramatic acceleration, targeting $54.6 billion specifically for the Defense Autonomous Working Group (DAWG) for rapid fielding, alongside over 1,900 reported civilian drone sightings in 2024 prompting increased protective measures.
Asia-Pacific is projected to witness the fastest growth during the forecast period. According to the latest data from the Stockholm International Peace Research Institute (SIPRI), defense spending across Asia and Oceania rose by 8.1% to reach $681 billion. This continuation of rapid regional militarisation builds directly upon the prior year's surge, where major powers such as China, India, and Japan recorded historic budget expansions.
By system type, the integrated C-UAS systems (detection and mitigation) segment is expected to hold the largest share of the global anti-drone market in 2026.
By platform, the ground-based systems segment is expected to hold the largest share in 2026, while vehicle-mounted systems are projected to register the fastest CAGR during the forecast period.
By mitigation method, the non-destructive (soft kill) segment is expected to hold the largest share in 2026, while destructive (hard kill) systems are projected to register the fastest CAGR, driven by the growing adoption of directed energy weapons and interceptor drone systems for high-threat military environments.
By application, the military and defense segment is expected to hold the largest share in 2026.
By end user, the defense forces segment is expected to hold the largest share in 2026, while infrastructure operators are projected to register the fastest CAGR during the forecast period, as regulatory mandates for drone detection at airports and critical energy facilities generate sustained non-defense procurement demand.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 12.6 Billion |
| Market Size in 2026 | USD 4.8 Billion |
| Market Size in 2025 | USD 4.1 Billion |
| Revenue Growth Rate (2026 to 2036) | CAGR of 10.2% |
| Format | PDF, Excel & Cloud Portal · 302 pages |
| Dominating System Type | Integrated C-UAS Systems (Detection and Mitigation) |
| Fastest Growing System Type | Directed Energy Weapons |
| Dominating Platform | Ground-Based Systems |
| Fastest Growing Platform | Vehicle-Mounted Systems |
| Dominating Mitigation Method | Non-Destructive (Soft Kill) |
| Fastest Growing Mitigation Method | Destructive (Hard Kill) |
| Dominating Deployment Mode | Fixed/Stationary Systems |
| Fastest Growing Deployment Mode | Mobile Systems |
| Dominating Application | Military and Defense |
| Fastest Growing Application | Critical Infrastructure Protection |
| Dominating End User | Defense Forces |
| Fastest Growing End User | Infrastructure Operators |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: system type, platform, mitigation method, deployment mode, application, end user.
The market's growth is driven by the explosive proliferation of commercial drone technology, the documented weaponization of unmanned systems in active conflict zones, and the accelerating investment by defense establishments and civilian security agencies in layered counter-UAS capabilities. According to the U.S. Department of Defense's 2025 Counter-UAS Strategy report, the number of drone incidents recorded at U.S. military installations globally increased by more than 60% between 2022 and 2024, underscoring the urgency driving procurement investment across the full C-UAS technology stack.
The global anti-drone market, formally designated as the counter-unmanned aerial systems (C-UAS) market, encompasses the complete spectrum of systems, technologies, and services deployed to detect, identify, track, and neutralize unauthorized, non-cooperative, or hostile unmanned aerial vehicles across military, governmental, and civilian operational contexts. The market spans detection technologies including radar, radio frequency (RF) signal intelligence, electro-optical and infrared (EO/IR) imaging, and acoustic sensing; identification and classification systems including AI-powered signal analysis and micro-Doppler signature processing; and neutralization or mitigation systems ranging from non-destructive soft-kill approaches including RF jamming, GNSS spoofing, and cyber-takeover to destructive hard-kill systems including directed energy weapons, kinetic interceptor projectiles, and interceptor drone platforms. These capabilities are deployed across ground-based fixed and mobile platforms, vehicle-mounted configurations, handheld portable systems, airborne assets, and naval platforms, serving defense forces, homeland security agencies, law enforcement, airport authorities, commercial enterprises, and critical infrastructure operators.
The fundamental driver of the global anti-drone market is the extraordinary democratization of drone technology capability that has occurred over the past decade, placing sophisticated aerial platforms with surveillance, payload delivery, and electronic warfare potential into the hands of an increasingly broad range of actors, including nation-state military forces, non-state armed groups, criminal organizations, and individual threat actors, at progressively lower cost thresholds. According to the RAND Corporation's 2025 analysis of the small UAS threat landscape, commercially available quadcopter drones capable of carrying 2 to 5 kilogram payloads at ranges exceeding 10 kilometers can be acquired for under USD 500, while militarily relevant long-range fixed-wing one-way attack drones can be produced by motivated non-state actors for between USD 5,000 and USD 50,000, compared to the hundreds of thousands to millions of dollars required for conventional munitions with comparable effect. The documented operational employment of such systems in the Russia-Ukraine conflict has, according to the Royal United Services Institute (RUSI) 2025 battlefield assessment, demonstrated that drone threats now operate across all altitude bands, speed regimes, and radar cross-section ranges in ways that systematically challenge single-sensor detection architectures, driving the development and procurement of multi-layered, AI-integrated C-UAS systems.
According to analyses from the European Defence Agency and broader defense industry sources, European and NATO member states are rapidly increasing investment in counter-UAS (C-UAS) capabilities in response to the growing threat posed by low-cost drones and loitering munitions. Procurement activity has accelerated significantly since 2022, with spending focused on radar systems, electronic warfare, directed-energy systems, and integrated air defense architectures. This sustained investment trajectory, combined with the parallel civilian procurement markets for airport, infrastructure, and public event drone security, is generating the commercial demand base that is supporting the market's projected 10.2% CAGR through the forecast period.
Report infographic
Market dynamics
7 factors across 3 forcesRising Security Threats from Unauthorized Drones
The global proliferation of commercial drone technology has created an unprecedented and rapidly escalating security threat environment across military, governmental, and civilian sectors that is the primary structural demand driver of the anti-drone market. By early 2026, the registered US commercial drone fleet is indeed exceeding 1.1 million units. This exponential growth in drone density, combined with the rapid capability improvement of commercially available platforms, has dramatically expanded the threat surface that security and defense organizations must address. The FBI's 2025 annual threat assessment specifically identified weaponized commercial drones as one of the five most significant emerging domestic terrorism threats facing the United States, citing multiple documented incidents of drone-facilitated surveillance of federal facilities, explosive payload delivery attempts, and coordination support for organized criminal enterprises. In Europe, Europol's 2025 Serious and Organized Crime Threat Assessment documented a 340% increase in drone-related criminal incidents across EU member states between 2020 and 2024, including drug trafficking, prison contraband delivery, and infrastructure surveillance operations conducted using commercially available drones.
Increasing Military and Border Surveillance Needs
The demonstrated operational impact of drone systems across recent conflicts, including the Russia–Ukraine war, the Israel–Hamas conflict, and Red Sea security operations, is driving heightened urgency in military counter-drone procurement across NATO member states and major Indo-Pacific defense establishments. These conflicts have underscored the scale, frequency, and diversity of drone threats, ranging from low-cost commercial quadcopters used for reconnaissance to long-range loitering munitions deployed in coordinated attacks. The ability of adversaries to deploy large volumes of drones simultaneously has exposed critical gaps in existing air defense systems, which were not originally designed to address such distributed and asymmetric threats.
As a result, counter-unmanned aerial system (C-UAS) capabilities have become a top defense priority. Assessments by organizations such as NATO have identified counter-drone systems as a key near-term capability gap, prompting coordinated procurement initiatives across member states. National defense agencies, including Germany’s Bundeswehr and the United Kingdom’s Ministry of Defence, are actively investing in a range of solutions, including electronic warfare systems, detection and tracking infrastructure, and directed energy technologies. These investments reflect a broader shift in defense strategy, with C-UAS systems becoming an essential component of modern, layered air defense architectures.
Table of contents
14 chapters · 163 sections · 302 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By System Type | Integrated C-UAS Systems | Directed energy weapons |
| By Platform | Ground-Based Systems | Vehicle-mounted systems |
| By Mitigation Method | Non-Destructive (Soft Kill) | Destructive (hard kill) |
| By Application | Military and Defense | Critical infrastructure protection |
| By End User | Defense Forces | Infrastructure operators |
By System Type
- Integrated C-UAS Systems to Dominate
- Integrated C-UAS systems are expected to account for the largest share of the market.
- This dominance reflects a clear operational consensus that standalone detection or mitigation solutions are insufficient when deployed in isolation.
- Effective counter-drone operations require seamless coordination between detection, identification, tracking, and neutralization functions, which integrated architectures are designed to deliver.
- Procurement trends across defense organizations, including initiatives led by the United States Army, increasingly prioritize fully integrated systems that provide end-to-end threat management within a unified command-and-control framework.
- However, within the mitigation systems segment, directed energy weapons are expected to witness the fastest growth during the forecast period.
- High-energy laser and high-power microwave systems are gaining traction as scalable and cost-effective solutions for countering high-volume drone threats.
- Programs led by defense organizations and companies such as Raytheon Technologies and Rafael Advanced Defense Systems are advancing these technologies toward broader operational deployment.
- Systems like Iron Beam and naval laser platforms are demonstrating the viability of directed energy as a core component of modern air defense strategies.
- As these technologies mature and production scales, they are expected to play an increasingly central role in future C-UAS architectures.
By Platform
- Ground-Based Systems to Hold the Largest Share
- Ground-based systems are expected to account for the largest share of the market.
- Fixed installations deployed at military bases, airports, government facilities, and other critical infrastructure sites represent the most established and high-value deployment category.
- These systems benefit from access to stable power supply, larger sensor configurations, and integrated command-and-control infrastructure, enabling superior detection range and more robust neutralization capabilities.
- Defense organizations such as the United States Air Force and European agencies including the European Defence Agency continue to prioritize fixed-site protection of strategic assets, reinforcing the dominance of ground-based C-UAS systems.
- However, vehicle-mounted systems are expected to register the fastest growth during the forecast period.
- Recent conflicts have demonstrated the vulnerability of mobile military units—including armored vehicles, artillery systems, and logistics convoys—to drone-based surveillance and precision strikes.
- As a result, defense forces are increasingly prioritizing mobile counter-drone capabilities that can be deployed alongside maneuvering units.
- Procurement programs highlighted by organizations such as Jane's Defence reflect growing demand for integrated vehicle-based air defense solutions.
- Initiatives across NATO countries, including Germany’s SHORAD programs, the United Kingdom’s LEAPP system, and Poland’s PILICA modernization, are incorporating mobile C-UAS capabilities into their force structures.
- Similarly, acquisitions by the United States Army of vehicle-integrated counter-drone systems further underscore the shift toward mobility-focused air defense, positioning this segment as a key growth driver in the evolving anti-drone market.
By Mitigation Method
- Non-Destructive (Soft Kill) to Hold the Largest Share
- The non-destructive (soft kill) segment is expected to account for the largest share of the global anti-drone market.
- Soft kill methods, including RF jamming that disrupts the control link and GNSS navigation signals of target drones, GNSS spoofing that feeds false position data causing loss of navigation control, and cyber-takeover that seizes command of the drone's flight controller, are preferred for the majority of current operational deployments because they avoid the physical debris and collateral damage risks associated with hard kill approaches, are more readily legally authorized in civilian and urban environments, and can be deployed with lower infrastructure requirements than kinetic or directed energy systems.
- According to DroneShield's 2025 Annual Report, RF-based jamming and detection systems represented approximately 64% of the company's 2024 revenue, reflecting the strong commercial preference for soft kill approaches in the law enforcement, airport, and event security customer segments that DroneShield predominantly serves.
- However, the destructive (hard kill) segment is projected to register the highest CAGR during the forecast period, driven by the demonstrated inadequacy of soft kill approaches against militarized drones equipped with frequency-hopping communication links, encrypted navigation systems, and autonomous waypoint-guided flight modes that render them immune to conventional RF jamming.
- According to the RUSI 2025 Electronic Warfare in Ukraine assessment, Russian drone operators progressively adapted their Shahed attack drone platforms throughout 2024 to operate with pre-programmed inertial navigation flight profiles that do not rely on active RF control links, rendering conventional jamming-based soft kill approaches ineffective and driving Ukrainian and allied investment in kinetic and directed energy hard kill systems.
- This operational pressure is elevating hard kill procurement in military C-UAS programs globally.
By Application
- Military and Defense to Hold the Largest Share
- The military and defense segment is expected to account for the largest share of the market.
- This dominance is driven by sustained investment in counter-drone capabilities across major defense organizations, reflecting the growing recognition of drones as a critical threat vector in modern warfare.
- Operational lessons from recent conflicts have highlighted the decisive role of counter-drone systems in battlefield protection, border security, and force survivability.
- Defense agencies such as the United States Army and allied NATO forces continue to expand procurement programs spanning fixed-site protection, mobile tactical systems, and advanced neutralization technologies.
- However, the critical infrastructure protection segment is expected to witness the fastest growth during the forecast period.
- High-profile drone attacks on energy and industrial assets have demonstrated the significant economic and security risks posed by unmanned systems targeting essential infrastructure.
- This has prompted governments and regulatory bodies to introduce stricter security requirements for sectors such as energy, transportation, and utilities.
- Organizations including the U.S. Department of Homeland Security and the U.S. Nuclear Regulatory Commission are driving the adoption of counter-drone technologies through policy mandates and risk mitigation frameworks.
- As infrastructure operators increasingly prioritize airspace security, demand for detection and mitigation systems across airports, power plants, and industrial facilities is expected to accelerate, positioning this segment as a key growth driver in the anti-drone market.
By End User
- Defense Forces to Hold the Largest Share
- The defense forces segment is expected to account for the largest share of the market.
- National military organizations represent the most significant procurement channel for counter-drone systems, driven by large-scale, multi-year acquisition programs that span fixed-site protection, mobile tactical deployments, and advanced neutralization technologies.
- Defense-led initiatives, including those coordinated by entities such as the Joint Counter-Small Unmanned Aircraft Systems Office and NATO, continue to shape demand, reflecting the strategic importance of counter-drone capabilities in modern military operations.
- However, the infrastructure operators segment is expected to witness the fastest growth during the forecast period.
- Operators of critical assets, including airports, energy infrastructure, and utilities, are increasingly adopting counter-drone solutions as regulatory requirements and security risks intensify.
- Government bodies such as the Transportation Security Administration are introducing frameworks to strengthen airspace security around aviation infrastructure, while industry organizations like the Electric Power Research Institute highlight the growing frequency of drone-related security incidents across energy networks.
- As counter-drone deployment transitions from optional security enhancement to regulatory necessity, infrastructure operators are emerging as a key high-growth segment within the global anti-drone market.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the market, driven primarily by the United States’ leadership in defense spending, technology development, and operational deployment of counter-unmanned aerial systems (C-UAS). The U.S. maintains the most advanced and institutionalized counter-drone ecosystem, supported by coordinated multi-service acquisition programs led by organizations such as the Joint Counter-Small Unmanned Aircraft Systems Office. In parallel, civilian initiatives led by the Federal Aviation Administration are expanding drone detection and airspace management infrastructure, further broadening the regional market beyond military applications. Canada also contributes to regional demand through modernization of continental defense systems and enhanced surveillance capabilities under binational security frameworks.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is expected to register the fastest growth during the forecast period. Rising defense expenditures, increasing geopolitical tensions, and growing concerns around drone incursions are driving rapid adoption of counter-drone technologies across the region. Countries such as India, Japan, and South Korea are prioritizing counter-drone capabilities within their defense modernization strategies, supported by domestic manufacturing initiatives and targeted procurement programs.
Europe
Meanwhile, Europe represents the second-largest regional market, with strong growth driven by heightened security concerns following the Russia–Ukraine conflict and coordinated investment efforts through organizations such as the European Defence Agency.
Middle East & Africa
The Middle East and Africa region is also witnessing sustained demand, led by countries such as Israel and Gulf states, where persistent drone threats have accelerated investments in advanced air defense and counter-drone systems.
Competitive landscape
- Lockheed Martin Corporation (U.S.)
- Raytheon Technologies Corporation (U.S.)
- Northrop Grumman Corporation (U.S.)
- Thales Group · France
- BAE Systems plc (U.K.)
- Leonardo S.p.A · Italy
- Israel Aerospace Industries · Israel
- DroneShield Ltd. · Australia
- Dedrone GmbH (Germany/U.S.)
- Anduril Industries (U.S.)
- Rafael Advanced Defense Systems · Israel
- Elbit Systems Ltd. · Israel
- Saab AB · Sweden
- L3Harris Technologies, Inc. (U.S.)
- Hensoldt AG · Germany
Frequently asked questions
The global anti-drone market is expected to reach USD 12.6 billion by 2036 from an estimated USD 4.8 billion in 2026, at a CAGR of 10.2% during the forecast period 2026 to 2036.
Cite this report
Meticulous Research. (2026). Anti-Drone (Counter-UAS) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1986). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/anti-drone-counter-uas-market-6669