Advanced Distribution Management Systems (ADMS) Market (2026-2036)
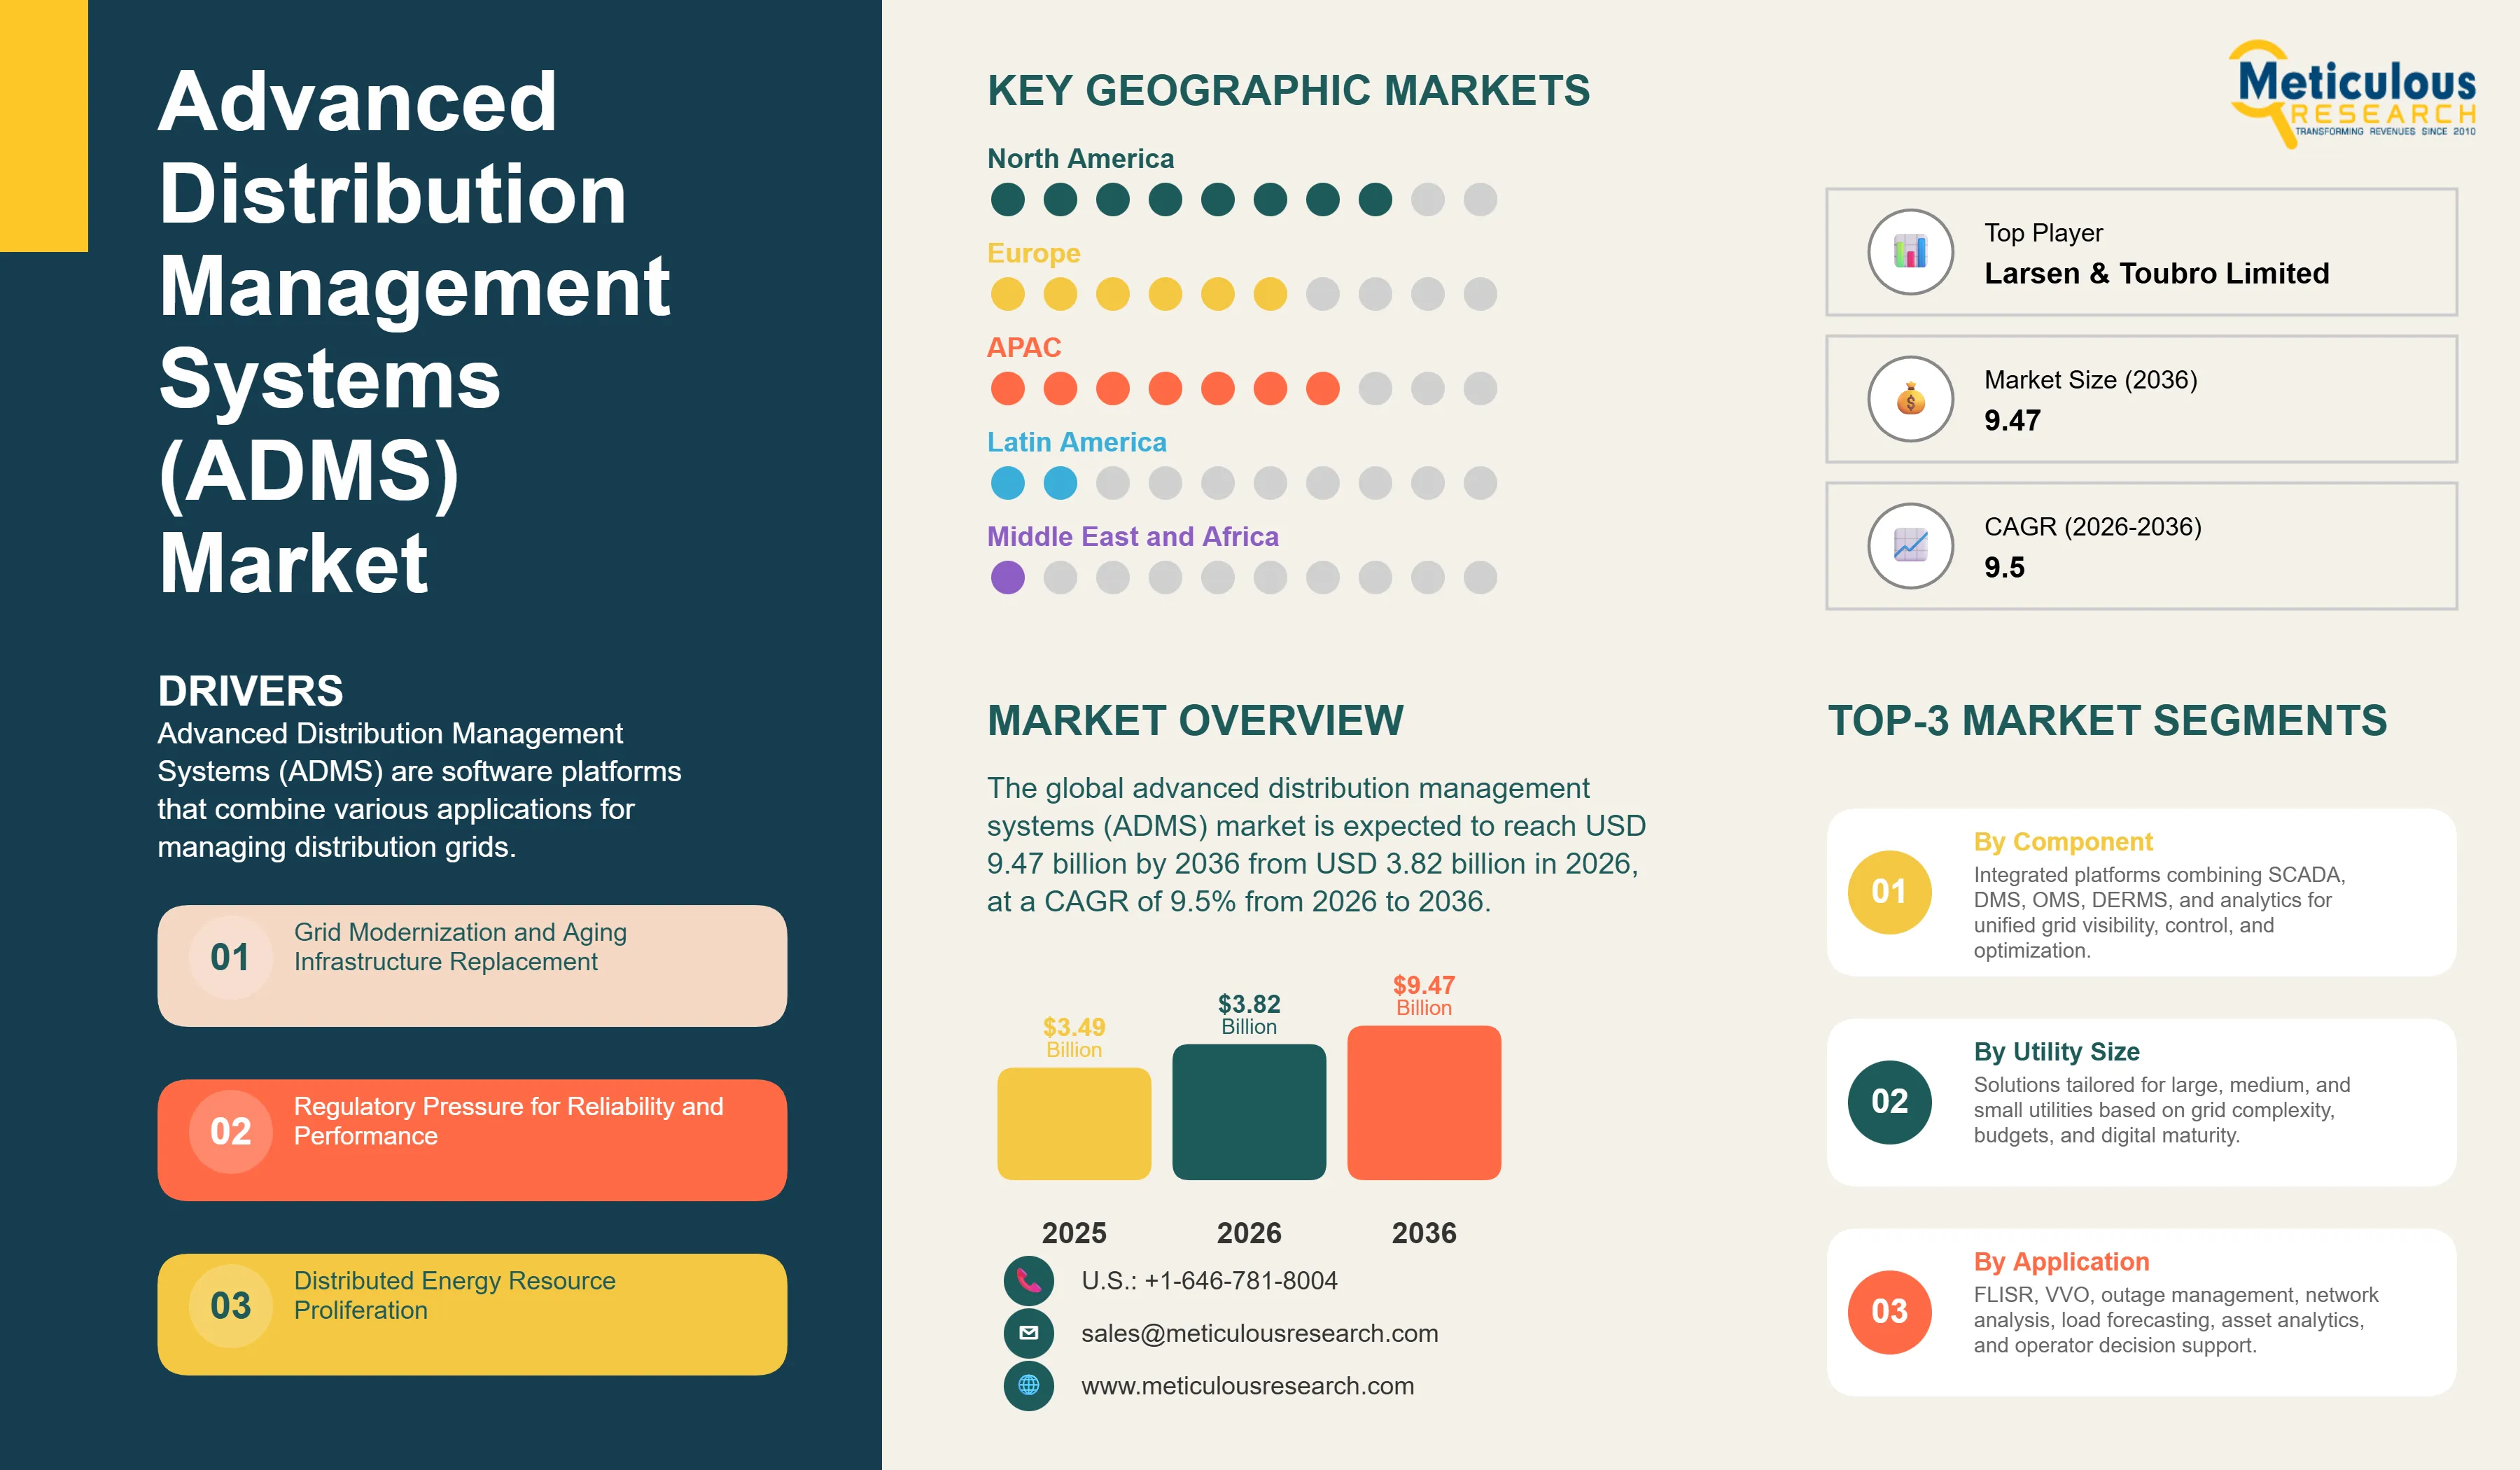
The global advanced distribution management systems (ADMS) market is expected to reach USD 9.47 billion by 2036 from USD 3.82 billion in 2026, at a CAGR of 9.5% from 2026 to 2036.
- Published
- Jan 2026
- Pages
- 277
- Format
- PDF + Excel
- Report ID
- MREP - 1041684
- Base year
- 2025
- 2026 · ESTIMATED
- $3.82B
- 2036
- $9.47B
- CAGR 2026–2036
- 9.5%
2025 baseline · 2026–2036 forecast at 9.5% CAGR · hover a bar for the value
Key highlights
In 2026, North America accounts for the largest share of the global ADMS market, driven by aging grid infrastructure requiring modernization, high grid automation adoption, regulatory incentives for grid reliability improvement, and presence of leading ADMS vendors.
Asia-Pacific is projected to register the highest CAGR during the forecast period, fueled by massive grid expansion and modernization in China and India, smart grid initiatives, rapid urbanization requiring reliable distribution infrastructure, and growing renewable energy integration.
Based on component, the integrated ADMS platform segment holds the largest share in 2026, driven by utility preference for unified solutions over siloed applications, operational efficiency benefits from integration, and vendor offerings emphasizing comprehensive platforms.
Based on deployment model, the on-premise segment dominates in 2026, reflecting utility preference for data control and security, regulatory requirements for critical infrastructure, and legacy IT infrastructure, though cloud adoption is accelerating.
Based on utility size, the large utilities segment accounts for the largest share in 2026, driven by complex grid management requirements, capital availability for major system investments, and early adopter status for advanced technologies.
The cloud-based ADMS segment is expected to grow at the highest CAGR during the forecast period, driven by lower upfront costs, scalability advantages, easier updates and maintenance, and growing utility comfort with cloud security.
The DMS (Distribution Management System) component within ADMS is experiencing significant growth, driven by grid complexity from DER integration, need for advanced network analysis, and volt-VAR optimization benefits.
The U.S. ADMS market is projected to grow at a CAGR of around 8% during the forecast period 2026 to 2036, driven by grid modernization investments, reliability regulations, and integration of distributed energy resources.
China is expected to lead the Asia-Pacific ADMS market, driven by the world's largest distribution grid expansion, government smart grid policies, urbanization requiring advanced infrastructure, and domestic ADMS vendor development.
In 2026, Germany is projected to account for significant share of the European ADMS market, driven by Energiewende grid transformation, high renewable penetration requiring advanced management, and strong utility automation culture.
Report summary
| Particulars | Details |
|---|---|
| Market Size Value in 2026 | USD 3.82 Billion |
| Revenue Forecast in 2036 | USD 9.47 Billion |
| Growth Rate | CAGR of 9.5% from 2026 to 2036 |
| Format | PDF, Excel & Cloud Portal · 277 pages |
| Base Year for Estimation | 2025 |
| Historical Data | 2021–2025 |
| Forecast Period | 2026–2036 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2036 |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, trends |
| Segments Covered | Component, Deployment Model, Utility Size, Application, Utility Type, Region |
| Regional Scope | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
| Countries Covered | U.S., Canada, Mexico, Germany, U.K., France, Italy, Spain, Netherlands, China, India, Japan, South Korea, Australia, Singapore, Brazil, Chile, Saudi Arabia, UAE, South Africa |
| Key Companies Profiled | Schneider Electric SE, Siemens AG, General Electric Company, ABB Ltd., Oracle Corporation, OSI Inc. (Emerson), Advanced Control Systems Inc. (Utilidata), Survalent Technology Corporation, Open Systems International Inc. (Emerson/AspenTech), ETAP (Operation Technology Inc.), AutoGrid Systems Inc., Itron Inc., Landis+Gyr, Trimble Inc., Hitachi Energy Ltd., Eaton Corporation, S&C Electric Company, Tantalus Systems Corp., KEPCO KDN, Larsen & Toubro Limited |
Report overview
Segments covered: component, deployment model, utility size.
Advanced Distribution Management Systems (ADMS) are software platforms that combine various applications for managing distribution grids. These include supervisory control and data acquisition (SCADA), distribution management systems (DMS), outage management systems (OMS), demand response management, distributed energy resource management, and advanced analytics. Together, they allow utilities to monitor, control, and optimize distribution networks in real time.
These systems use algorithms for network analysis and optimization. They provide real-time state estimation for better grid visibility and automate outage response with fault location, isolation, and service restoration (FLISR). They also improve efficiency and power quality through volt-VAR optimization (VVO), track switching operations via network topology processing, forecast loads and equipment failures with predictive analytics, and support operator decision-making with visualization interfaces.
By integrating utility applications that typically operate in silos, using real-time data from smart meters and grid sensors, employing analytics and optimization algorithms, and offering unified operator interfaces, ADMS platforms help utilities manage complex distribution grids. These grids have bidirectional power flows from distributed generation, dynamic loads from electric vehicles, increased automation and remote control features, and greater customer expectations for reliability and power quality.
Advanced Distribution Management Systems provide the operational backbone for modern electric distribution grids. They offer the visibility, control, and optimization needed to manage networks that have changed from simple, one-way power systems to active and complex networks. These networks now include distributed generation, energy storage, electric vehicle charging, and two-way power flows. These integrated platforms tackle key challenges for distribution utilities. They help manage the complexity from increasing distributed energy resources, improve reliability, reduce outage durations and frequencies, optimize grid operations for efficiency and power quality, integrate renewable energy while keeping stability, enable grid modernization and automation, and meet regulatory performance and reporting requirements. As distribution grids evolve from basic delivery systems to smart, interactive networks that support the energy transition, ADMS moves from being an optional upgrade to essential infrastructure for safe, reliable, and efficient operations.
Several transformative trends are reshaping the ADMS market. These include the use of artificial intelligence and machine learning for predictive analytics and autonomous grid operations, the merging of ADMS with distributed energy resource management systems (DERMS) for comprehensive edge grid management, the development of cloud-based ADMS architectures that offer scalability and cost benefits, the rollout of advanced distribution automation that enables self-healing grid features, and the inclusion of customer engagement and demand-side management capabilities. The push for grid modernization, the growth of distributed energy resources, the maturation of digital technologies, regulatory pressure for better reliability, and changing customer expectations have raised ADMS from back-office software to strategic platforms essential for grid transformation and the evolution of utility business models.
Report infographic
Market dynamics
7 factors across 3 forcesGrid Modernization and Aging Infrastructure Replacement
The aging distribution infrastructure in developed markets creates a need for grid modernization that includes ADMS capabilities. Much of the distribution infrastructure in North America and Europe was installed 40-60 years ago and is nearing the end of its service life, requiring replacement or significant refurbishment. At the same time, changing grid conditions, such as distributed generation, electric vehicle loads, and customer expectations, make older grid designs and operations insufficient. ADMS allows utilities to modernize their operations by providing better visibility through real-time monitoring instead of periodic manual checks. It offers advanced analytics that can identify problems before failures occur and automation that reduces manual tasks and speeds up response times. Additionally, optimization improves efficiency and delays the need for capital investment. Grid modernization programs create opportunities to implement ADMS as a foundational platform to support transformation.
Regulatory Pressure for Reliability and Performance
Regulatory requirements for distribution reliability, performance reporting, and customer service are pushing utilities to adopt ADMS. Many jurisdictions set performance standards, including SAIDI (System Average Interruption Duration Index) and SAIFI (System Average Interruption Frequency Index), along with financial penalties for poor performance and rewards for good performance. ADMS directly helps improve reliability by enabling quicker outage detection and restoration, predictive maintenance that prevents failures, and optimization that reduces stress on equipment. Additionally, regulators increasingly demand detailed reports on grid performance, renewable integration, and operational metrics, which ADMS platforms provide through automated data collection and analytics.
Table of contents
15 chapters · 188 sections · 277 pages · click to expandGeographic analysis
North America
Largest shareNorth America has the largest market share in 2026. This is due to aging distribution infrastructure that needs updates. Utilities are replacing equipment and systems that are 40 to 60 years old. Regulatory frameworks encourage improvements in reliability through performance-based rules. There is also high adoption of grid automation, thanks to extensive SCADA coverage that supports ADMS. The rise of distributed energy resources, particularly solar and storage, adds management complexity. Leading ADMS vendors like GE, Schneider Electric, OSI, and Survalent strengthen this market. U.S. utilities are investing heavily in grid modernization, with ADMS as a key part of their plans. Canadian utilities are also modernizing, focusing on resilience against severe weather.
Asia-Pacific
Asia-Pacific is projected to grow at the highest rate. China’s large-scale distribution grid expansion and smart grid projects drive this growth. The country has the world’s largest grid, which requires effective management. India is modernizing its grid and launching smart city programs. Rapid urbanization in the region demands reliable distribution infrastructure. Renewable energy integration, particularly distributed solar, is increasing. Domestic ADMS vendors are developing in China, India, and South Korea. China stands out as a significant market due to its grid size and government technology mandates, which create chances for both international vendors and local companies.
Europe
Europe is also a major market, influenced by Germany’s Energiewende grid transformation and a high level of renewable energy. The UK has its own requirements for grid reliability and innovation programs. The Nordics are at the forefront of grid automation and renewable integration. Across Western Europe, aging infrastructure needs replacement. European utilities prioritize sustainability and innovation, which drives the adoption of advanced ADMS features like DER integration and analytics.
Competitive landscape
- Schneider Electric SE · France
- Siemens AG · Germany
- General Electric Company (U.S.)
- ABB Ltd. · Switzerland
- Oracle Corporation (U.S.)
- OSI Inc./Emerson (U.S.)
- Advanced Control Systems Inc./Utilidata (U.S.)
- Survalent Technology Corporation · Canada
- Open Systems International/Emerson (U.S.)
- ETAP/Operation Technology Inc. (U.S.)
- AutoGrid Systems Inc. (U.S.)
- Itron Inc. (U.S.)
- Landis+Gyr · Switzerland
- Trimble Inc. (U.S.)
- Hitachi Energy Ltd. · Switzerland
- Eaton Corporation (Ireland/U.S.)
- S&C Electric Company (U.S.)
- Tantalus Systems Corp. · Canada
- KEPCO KDN · South Korea
- Larsen & Toubro Limited · India
Frequently asked questions
The ADMS market is expected to grow from USD 3.82 billion in 2026 to USD 9.47 billion by 2036.
Cite this report
Meticulous Research. (2026). Advanced Distribution Management Systems (ADMS) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MREP - 1041684). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/advanced-distribution-management-systems-market-6367