Ultrasound Market (2025-2032)
The Ultrasound Market is expected to reach $18.07 Billion by 2032, at a CAGR of 5.8% from 2025 to 2032.
- Published
- Jan 2025
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRHC - 104271
- Base year
- 2024
- 2032 · FORECAST
- $18.07B
- 2032
- $18.07B
- CAGR 2025–2032
- 5.8%
2024 baseline · 2025–2032 forecast at 5.8% CAGR · hover a bar for the value
Key highlights
By Component: In 2025, the Ultrasound Devices Segment to Dominate the Ultrasound Market
By Technology: In 2025, the Diagnostic Ultrasound Segment to Dominate the Ultrasound Market
By Display: In 2025, the Colored Display Segment to Dominate the Ultrasound Market
By Portability: in 2025, the Cart/Trolley-based Ultrasound Systems Segment to Dominate the Ultrasound Market
By Application: in 2025, the Diagnostic Applications Segment to Dominate the Ultrasound Market
By End User: in 2025, the Hospitals & Clinics Segment to Dominate the Ultrasound Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 5.8% |
| Market Size (Value) | USD 18.07 Billion by 2032 |
| Segments Covered | By Product · Ultrasound Devices · Transducers/Probes · Gels · Other Components · (Note:- Other components include probe racks, probe holders, disposable wipes, ultrasound needle guides, extender cables and adapters, and battery chargers & rechargeable batteries.) · By Technology · Diagnostic Ultrasound · 2D Ultrasound · 3D and 4D Ultrasound · Doppler Ultrasound · Color Doppler Imaging · Continuous Doppler Imaging · Pulse Wave Doppler Imaging · Therapeutic Ultrasound · High-Intensity Focused Ultrasound (HIFU) · Lithotripsy · Extracorporeal Shock Wave Lithotripsy (ESWL) · Shock Wave Lithotripsy (SWL) · By Display · Colored Display · Black and White (B/W) Display · By Portability · Cart/Trolley-based Ultrasound Systems · Handheld/Compact Ultrasound Systems · Point of Care Ultrasound Systems · By Applications · Diagnostic Applications · General Imaging · Cardiology · Obstetrics/Gynecology · Vascular · Urology · Other Diagnostic Applications · (Note: Other diagnostic applications include abdominal and anesthesia) · Therapeutic Applications · Drug Delivery · Physical Therapy · Pain Management · Other Therapeutic Applications · (Note:- Other therapeutic applications include thrombolysis and sonoporation) · By End User · Hospitals and Clinics · Diagnostic Imaging Centers · Ambulatory Care Centers · Academic and Research Institutes |
| Countries Covered | North America (U.S., Canada), Europe (Germany, France, U.K., Italy, Spain, Rest of Europe), Asia-Pacific (Japan, China, India, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and Middle East & Africa |
| Key Companies | GE Healthcare Technologies Inc. (U.S.), Konica Minolta, Inc. (Japan), Koninklijke Philips N.V. (Netherlands), Siemens Healthineers AG (Germany), Canon Inc. (Japan), Esaote S.p.A (Italy), Shenzhen Mindray Bio-Medical Electronics Co., Ltd (China), Samsung Medison Co., Ltd. (South Korea), FUJIFILM SonoSite, Inc. (A Subsidiary of FUJIFILM Holdings Corporation) (U.S.), and Hologic, Inc. (U.S.) |
Report overview
Segments covered: product, ultrasound device, transducers/probe, gel, other component, technology, diagnostic ultrasound, 2d ultrasound, 4d ultrasound, doppler ultrasound, color doppler imaging, continuous doppler imaging, pulse wave doppler imaging, therapeutic ultrasound, lithotripsy, display, colored display, portability, cart/trolley-based ultrasound system, handheld/compact ultrasound system, point of care ultrasound system, application, diagnostic application, general imaging, cardiology, obstetrics/gynecology, vascular, urology, other diagnostic application, therapeutic application, drug delivery, physical therapy, pain management, other therapeutic application, end user, hospital, clinic, diagnostic imaging center, ambulatory care center, academic, research institute. Regions: North America, Europe, Asia-Pacific, Latin America.
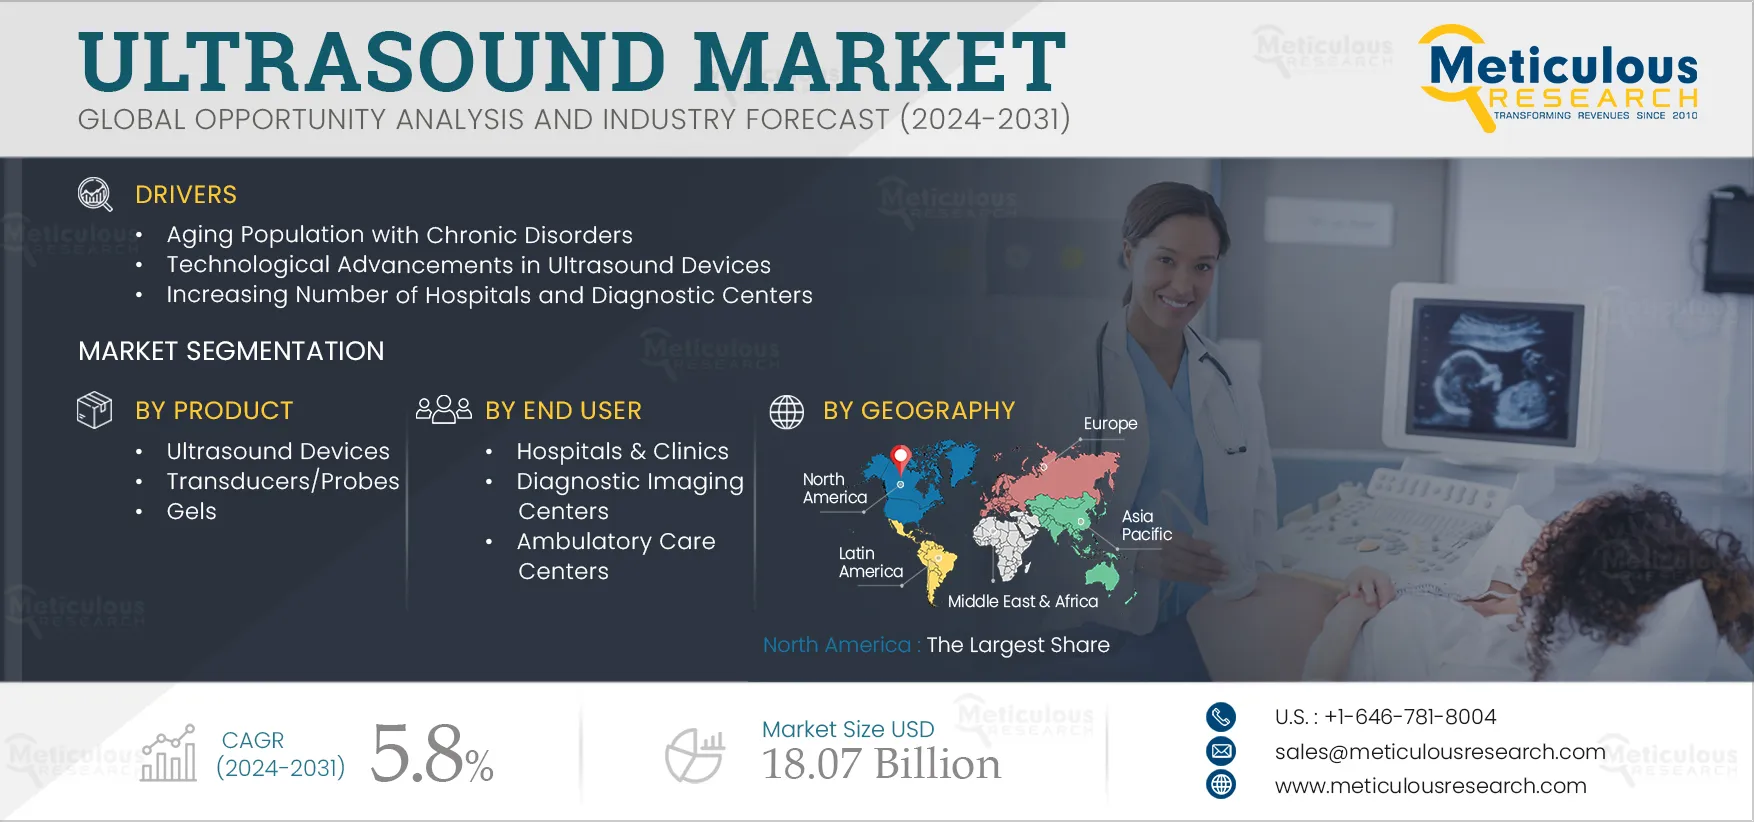
The growth of the ultrasound market is driven by the aging population with chronic disorders, advancements in ultrasound device technology, the rising number of diagnostic imaging centers and hospitals, the rising incidence of orthopedic injuries and musculoskeletal disorders, and the increasing public & private investments, funding, and grants for ultrasound device development.
Furthermore, the emergence of point-of-care ultrasound devices and the demand from emerging economies are expected to create market growth opportunities.
Report infographic
Market dynamics
5 factors across 3 forcesAging Population and the Subsequent Increase in Chronic Disease Prevalence
The aging population and shifts in societal behaviors are significant factors contributing to a consistent rise in the prevalence of chronic diseases, which has led to an increased demand for ultrasound procedures. The "World Population Ageing 2020" report published by the Department of Economic and Social Affairs, United Nations, highlights that the global population of individuals aged 65 or above was 727 million in 2020. This number is projected to reach 1.5 billion by 2050.
Furthermore, knee pain is highly prevalent among the elderly population, often linked to knee osteoarthritis, a condition that can be diagnosed using ultrasound. Additionally, lung cancer ranks among the most widespread chronic illnesses. According to GLOBOCAN, lung cancer cases are projected to rise from 2.21 million in 2020 to approximately 3.63 million in 2032.
The elderly population also faces the risk of malnutrition, which can result in increased frailty, reduced quality of life, and higher mortality rates. Malnutrition often leads to a decrease in muscle mass, affecting muscle strength. In this context, researchers have explored the use of ultrasonography to measure muscle thickness as a means of nutritional assessment in older adults.
Thus, the increasing prevalence of chronic diseases coupled with the rising geriatric population is expected to boost the adoption of ultrasound devices, driving the growth of this market.
Rising Prevalence of Orthopedic Injuries and Musculoskeletal Disorders
Musculoskeletal disorders are linked to both occupational injuries and age-related dysfunction. Common musculoskeletal conditions include rheumatoid arthritis, osteoarthritis, osteoporosis, and septic arthritis. Among the elderly population, bone fractures and broken hips are prevalent orthopedic injuries.
Globally, many individuals experience musculoskeletal conditions. For instance, according to the World Health Organization (WHO) 2021, approximately 1.71 billion people worldwide are affected by musculoskeletal conditions. Furthermore, the WHO predicts a rise in disabilities related to musculoskeletal disorders in the coming decades.
Furthermore, the older population often faces age-related issues such as joint pain, arthritis, and osteoporosis. Arthritis is prevalent among adults, affecting millions of individuals worldwide. According to the CDC, approximately 63.0 million people in the U.S. were diagnosed with arthritis in 2020, with projections indicating that this number could reach 78.4 million by 2040. These orthopedic conditions have increased the demand for ultrasound devices to analyze and diagnose these disorders.
Table of contents
14 chapters · 113 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Component | Ultrasound Devices | — |
| By Technology | Diagnostic Ultrasound | — |
| By Display | Colored Display | — |
| By Portability | Cart/Trolley-based Ultrasound Systems | — |
| By Application | Diagnostic Applications | — |
| By End User | Hospitals & Clinics | — |
By Component
- The ultrasound devices segment is expected to account for the largest share of the ultrasound market.
- Ultrasound devices are machines that use direct high-frequency sound waves to make images to examine the organs present inside the body of a patient.
- The large market share of this segment is attributed to factors such as the demand for minimally invasive surgery is a major driver for the ultrasound devices market.
- Technologically advanced ultrasound devices enable high-resolution real-time imaging of soft tissue configurations, making ultrasound-guided techniques increasingly prevalent in minimally invasive surgeries.
By Technology
- The diagnostic ultrasound segment is expected to account for a larger share of the ultrasound market.
- Diagnostic ultrasound is done to show structures inside the body and help healthcare providers to guide and diagnose and treatment for various diseases, chronic conditions, or injuries.
- The large market share of this segment is attributed to factors such as its simplicity, cost-effectiveness, real-time imaging capability, and portability.
- It is widely recognized as the preferred standard technology for detecting abnormalities and facilitating diagnosis.
By Display
- The Colored Display Segment to Dominate the Ultrasound Market
- The colored display segment is expected to account for the largest share of the ultrasound market.
- Colored display ultrasounds are devices that display a colored picture or image of the parts of the body that are scanned.
- The large market share of this segment can be attributed to the benefits offered by colored display ultrasound, such as clear visualization of blood flow, detection of abnormalities in the hemodynamics of the bloodstream, and identification of speed and directions of the blood flow.
By Portability
- The cart/trolley-based ultrasound systems segment is expected to account for the largest share of the ultrasound market.
- The large market share of this segment is attributed to the advantages offered by these systems over handheld ultrasound devices, such as a wider range of high image quality and imaging capabilities.
- Additionally, cart-based ultrasound machines, being bulkier and more powerful than handheld devices, are commonly preferred in clinical settings such as hospitals, clinics, and diagnostic imaging centers.
- Furthermore, these machines are mounted on carts, providing stability and enabling easy mobility between patient rooms.
By Application
- The diagnostic applications segment is expected to account for the largest share of 65% of the ultrasound market.
- The large market share of this segment is attributed to the increasing awareness of the importance of early diagnosis of diseases, advancements in diagnostic imaging technology, and the extensive range of diagnostic applications for ultrasound devices.
By End User
- The hospitals & clinics segment is expected to account for the largest share of 44.3% of the ultrasound market.
- This segment’s large market share can be attributed to the increasing hospitalizations linked to chronic diseases in aging populations, rising healthcare expenditure, high adoption of advanced imaging modalities in hospitals, the demand for cost-effective products to manage healthcare expenses, growing emphasis on point-of-care services for patients, and the expansion of healthcare facilities in emerging economies.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 34.9% of the ultrasound market, followed by Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America’s significant market share can be attributed to the increasing preference for minimally invasive surgery, rising incidence of chronic disorders, growing occurrences of orthopedic injuries, and advancements in ultrasound imaging technology. Healthcare expenditure is a significant factor that defines healthcare quality for the population. The health expenditure of North America increased to 18.3% of GDP in 2020, an increase from 16.2% in 2019 (Source: The World Bank). This increase in healthcare spending signifies a heightened focus on ensuring the population's health and is anticipated to drive the increased adoption of advanced ultrasound technologies in the region. By Geography: North America to Dominate the Ultrasound Market in 2025
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is projected to register the highest CAGR of 8.6% during the forecast period. The growth of this regional market is driven by the increasing prevalence of orthopedic injuries and cancer, the aging population, government initiatives aimed at promoting early diagnosis of diseases, growing adoption of advanced medical technologies, improving healthcare infrastructure, rising healthcare expenditure, and insurance coverage.
Competitive landscape
- November 2024
Siemens Healthineers AG (Germany) launched ACUSON Maple, an ultrasound system powered with AI to optimize everyday clinical performance for users of all skill levels.
- October 2024
GE Healthcare Technologies, Inc. (U.S.) launched Venue Family point-of-care ultrasound systems. These systems include Caption Guidance, artificial intelligence (AI) based technology that provides real-time guidance for capturing diagnostic-quality cardiac images.
- February 2024
Shenzhen Mindray Bio-Medical Electronics Co., Ltd. (China) launched its first handheld wireless ultrasound system, the TE Air. This device is designed for seamless operation across various medical settings, offering clear point-of-care ultrasound (POCUS) imaging.
- GE Healthcare Technologies Inc. (U.S.)
- Konica Minolta, Inc. · Japan
- Koninklijke Philips N.V. · Netherlands
- Siemens Healthineers AG · Germany
- Canon Inc. · Japan
- Esaote S.p.A · Italy
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd · China
- Samsung Medison Co., Ltd. · South Korea
- Hologic, Inc. (U.S.)
Frequently asked questions
This market study covers the sizes & forecasts of the ultrasound market, segmented based on component, technology, display, portability, application, end user, and geography. It also provides the value analysis of various segments and sub-segments of the global ultrasounds market at country levels.
Cite this report
Meticulous Research. (2025). Ultrasound Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 104271). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/ultrasound-market-4972