Packaging Films Market (2026-2036)
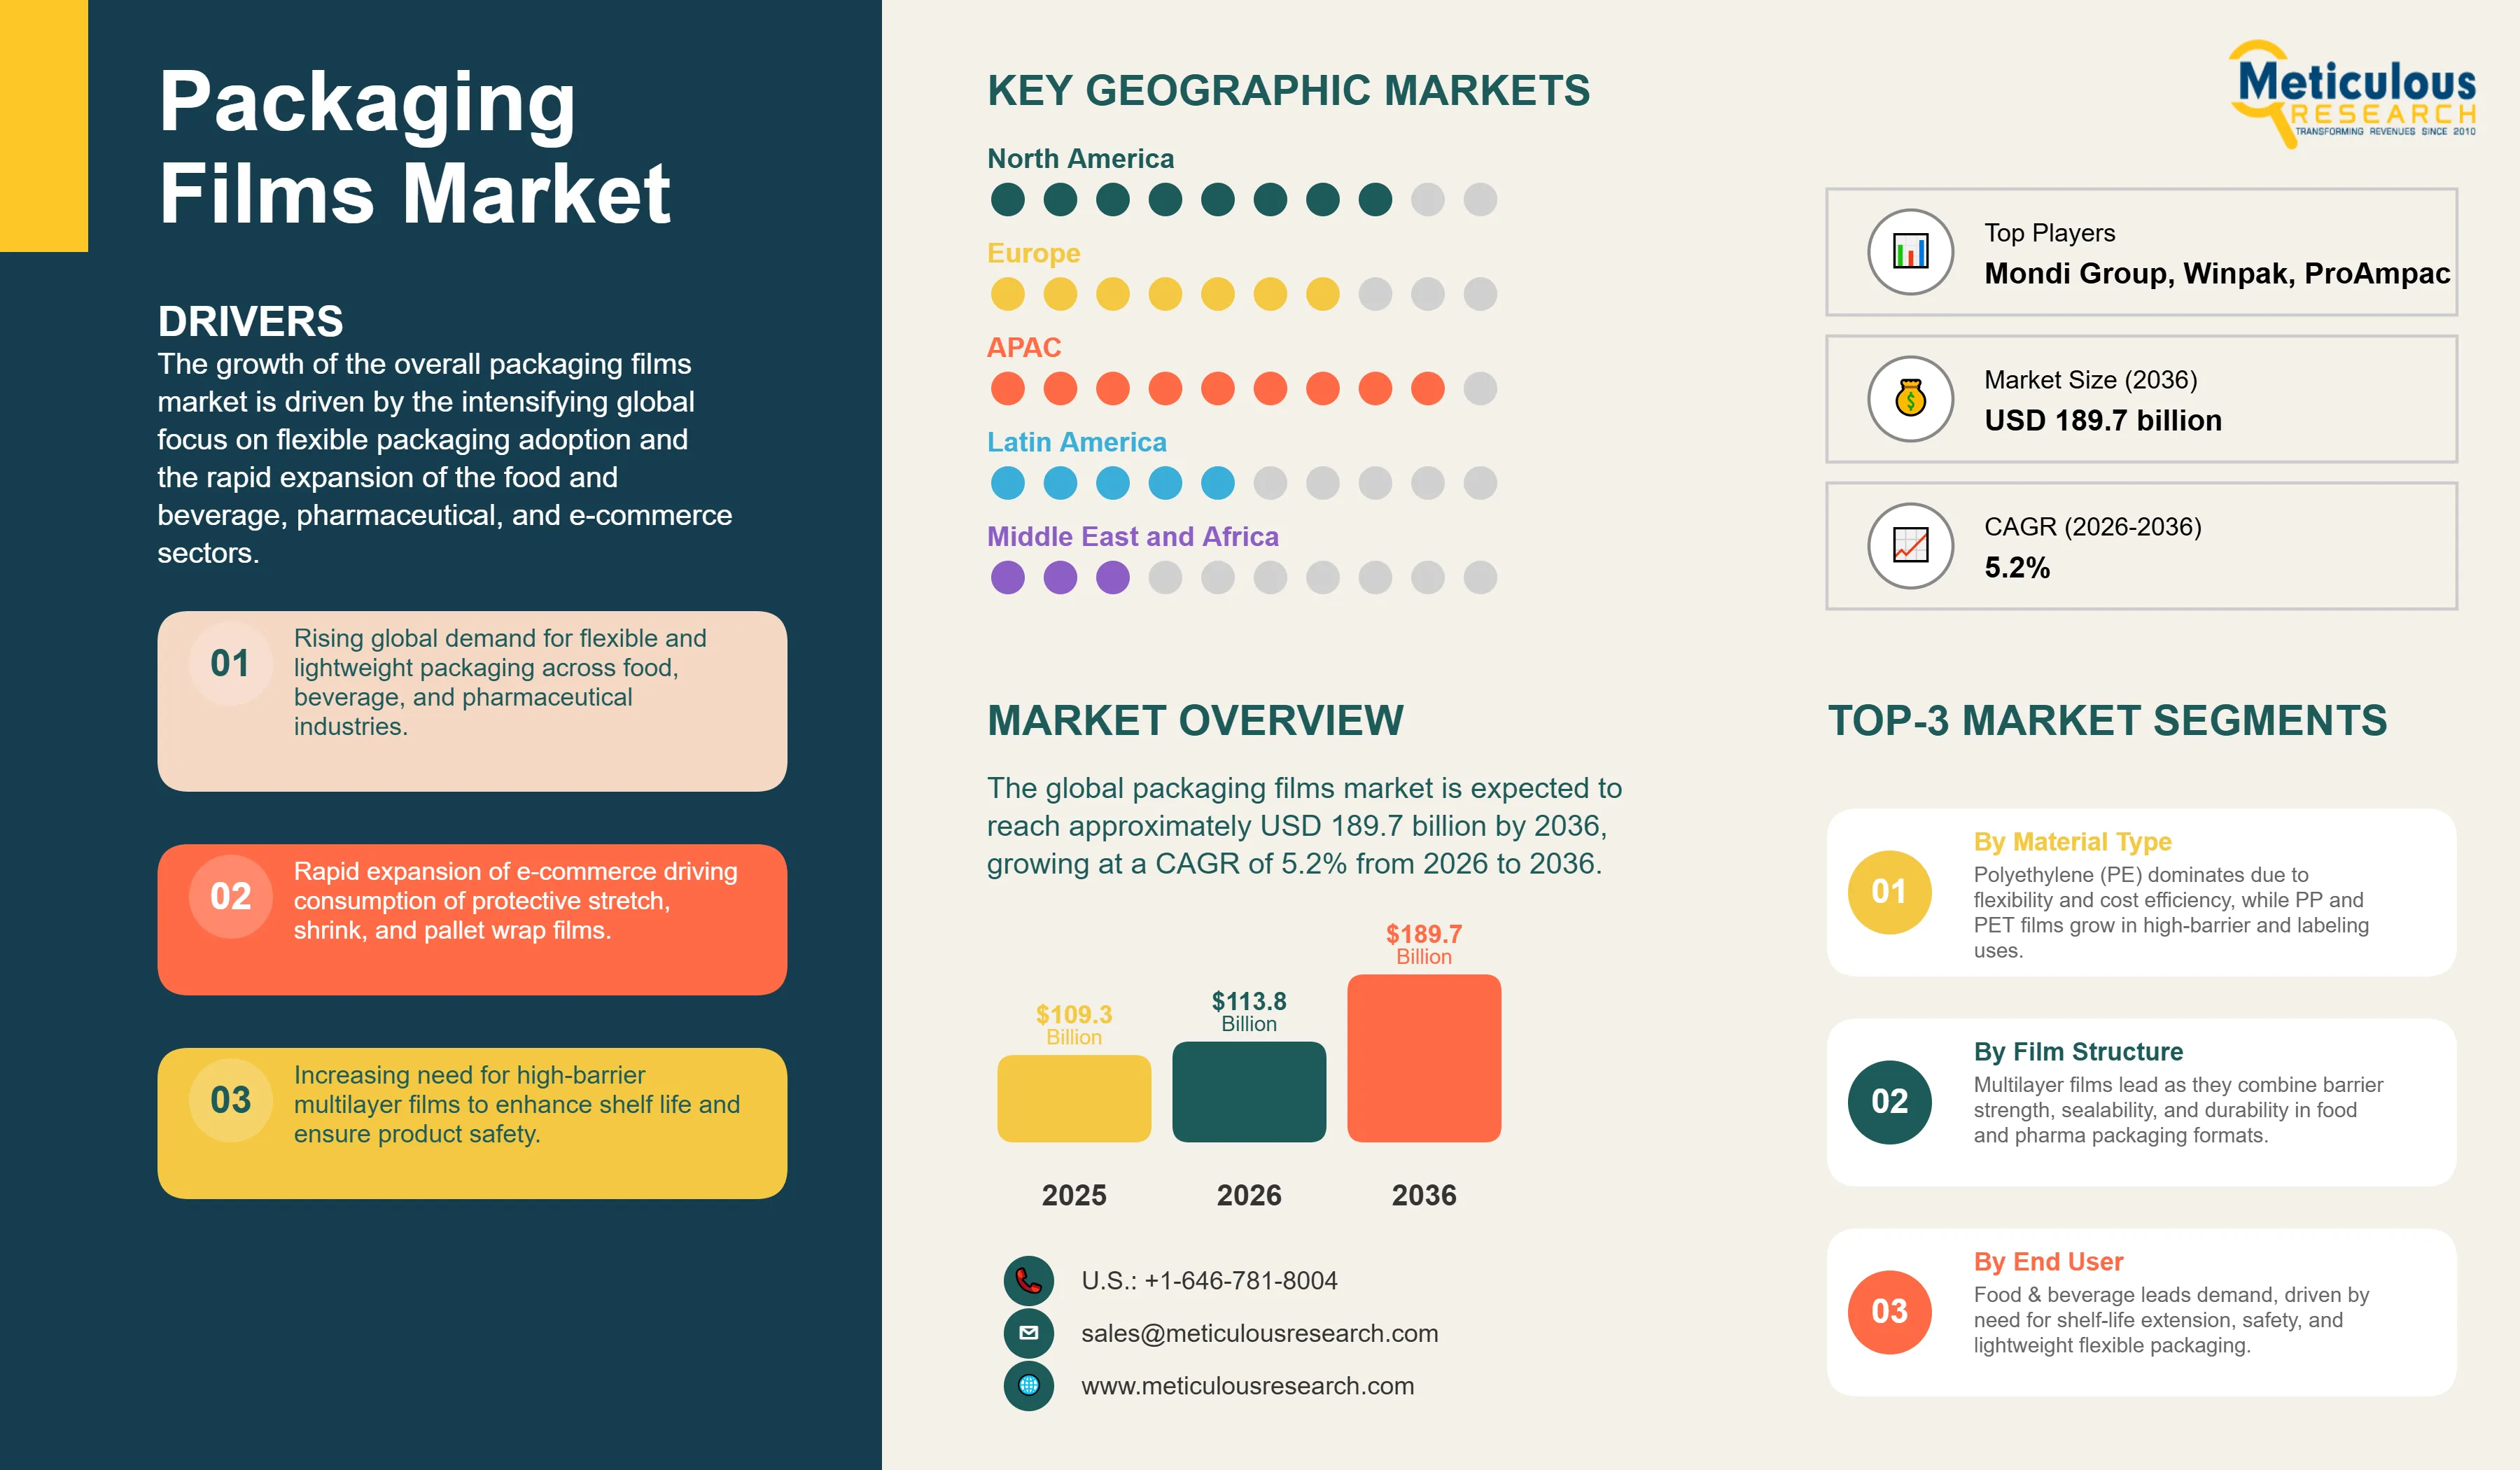
The global packaging films market was valued at USD 109.3 billion in 2025. The market is expected to reach approximately USD 189.7 billion by 2036 from USD 113.8 billion in 2026, growing at a CAGR of 5.2% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 287
- Format
- PDF + Excel
- Report ID
- MR-1802
- Base year
- 2025
- 2025 · BASELINE
- $109.3B
- 2036
- $189.7B
- CAGR 2026–2036
- 5.2%
2025 baseline · 2026–2036 forecast at 5.2% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global packaging films market is projected to reach USD 189.7 billion by 2036.
The market is expected to grow at a CAGR of 5.2% from 2026 to 2036.
Asia-Pacific dominates the global packaging films market with the largest market share in 2026, driven by massive investments in flexible packaging infrastructure and the rapid growth of food processing, consumer goods, and e-commerce sectors in China, India, and Southeast Asia.
North America is expected to witness steady growth during the forecast period, supported by strong demand for sustainable and recyclable film structures and the presence of leading film manufacturers and converters in the U.S. and Canada.
By material type, the polyethylene (PE) films segment holds the largest market share in 2026, driven by its widespread adoption across flexible packaging applications owing to its superior flexibility, cost efficiency, and compatibility with modern high-speed packaging lines.
By film structure, the multilayer films segment holds the largest market share in 2026, due to its ability to combine the functional properties of different materials into a single film construction, enabling enhanced barrier performance, sealing strength, and mechanical durability.
By manufacturing technology, the biaxially oriented films segment holds the largest share of the overall market in 2026, owing to the widespread usage of BOPP and BOPET films across food packaging, labeling, and lamination applications.
By end-use, the food and beverage segment holds the largest share of the overall market in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 189.7 Billion |
| Market Size in 2026 | USD 113.8 Billion |
| Market Size in 2025 | USD 109.3 Billion |
| Market Growth Rate (2026-2036) | CAGR of 5.2% |
| Format | PDF, Excel & Cloud Portal · 287 pages |
| Dominating Region | Asia-Pacific |
| Fastest Growing Region | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Material Type, Film Structure, Manufacturing Technology, End-use, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: material type, film structure, manufacturing technology, end-use.
The growth of the overall packaging films market is driven by the intensifying global focus on flexible packaging adoption and the rapid expansion of the food and beverage, pharmaceutical, and e-commerce sectors. As brand owners and packaging converters seek to integrate greater functionality into their packaging formats — including superior barrier performance, extended shelf life, and material efficiency — packaging films have become essential for maintaining product safety and operational sustainability across the supply chain. The rapid expansion of mono-material recyclable film structures and the increasing need for high-barrier protection in pharmaceutical and ready-to-eat food applications continue to fuel significant growth across all major geographic regions.
Packaging films are thin, flexible sheet materials engineered to protect, preserve, and present products across a wide range of industries and end-use applications. These materials are manufactured from a variety of polymer resins — including polyethylene, polypropylene, polyester, polyamide, and biopolymers — and are processed through blown, cast, or biaxial orientation technologies to achieve specific functional properties such as barrier resistance, clarity, heat sealability, and mechanical strength. The market is defined by a diverse portfolio of solutions, ranging from simple monolayer polyethylene stretch films used in industrial and agricultural wrapping to sophisticated multilayer high-barrier structures used in vacuum-packed meat, retort pouches, and pharmaceutical blister packaging.
The market includes solutions tailored to the specific needs of each end-use sector. In the food and beverage industry, packaging films are deployed to protect perishable and shelf-stable products from oxygen, moisture, light, and microbial contamination — directly influencing product freshness and consumer safety. In the pharmaceutical and healthcare sector, films serve as a critical interface between the product and its environment, where precise control over permeability, sterility, and tamper resistance is non-negotiable. In personal care, agriculture, and industrial segments, films provide functional protection while increasingly being designed to meet circular economy and sustainability goals set by both regulators and brand owners.
The global packaging industry is undergoing a structural shift, with flexible film-based solutions continuing to outperform traditional rigid packaging formats across most high-growth end-use categories. This transition is being accelerated by the growing preference for lightweight, cost-effective packaging that reduces logistics costs and lowers carbon emissions across the supply chain. At the same time, rising regulatory pressure — particularly in Europe and North America — around single-use plastics and recyclability is compelling manufacturers to invest heavily in next-generation film structures, including mono-material polyethylene and polypropylene laminates, post-consumer recycled content integration, and bio-based and compostable film alternatives. These developments are reshaping the competitive landscape and creating new value pools for manufacturers that can combine functional performance with environmental responsibility.
Shift Toward Mono-Material and Recyclable Film Structures
One of the most significant structural shifts underway in the packaging films market is the industry-wide transition from conventional multi-substrate laminates — typically combining polyethylene, polyester, aluminum foil, and polyamide — toward mono-material film constructions that can be processed through established recycling streams. This shift is being driven by tightening regulations across the European Union under the Packaging and Packaging Waste Regulation (PPWR), as well as voluntary commitments made by global consumer goods companies to achieve fully recyclable or reusable packaging portfolios. Leading manufacturers such as Amcor plc and Berry Global Inc. have made significant investments in developing high-barrier, all-polyethylene and all-polypropylene film structures that match the functional performance of traditional multi-substrate laminates, while enabling collection and reprocessing through existing flexible film recycling infrastructure. These innovations are fundamentally changing how film manufacturers design their product portfolios, with downgauging — producing thinner films that deliver equivalent or superior mechanical properties — emerging as a parallel strategy to reduce material consumption and cost while meeting sustainability targets.
The rising global demand for convenience foods, ready-to-eat meals, and premium fresh and processed products is fueling strong growth in high-barrier multilayer packaging films. These structures — engineered with five, seven, or more functional layers incorporating materials such as ethylene vinyl alcohol (EVOH), polyamide, and metallized substrates — are essential for maintaining product integrity across extended distribution and retail cycles. Film manufacturers including Sealed Air Corporation, Coveris Holdings S.A., and Winpak Ltd. are continuously advancing their coextrusion and coating capabilities to offer film structures with increasingly precise oxygen transmission rates (OTR) and water vapor transmission rates (WVTR), enabling food producers to meet growing consumer expectations for freshness without reliance on artificial preservatives. The pharmaceutical sector is similarly driving demand for high-barrier lidding and blister films capable of meeting stringent regulatory specifications for moisture and gas permeation across varying temperature and humidity conditions.
Report infographic
Market dynamics
2 factors across 2 forcesRising Demand for Flexible and Protective Packaging Across High-Growth End-use Sectors
A key driver of the packaging films market is the sustained and broad-based expansion of end-use industries that rely on flexible film solutions for product protection, preservation, and presentation. The food and beverage sector — by far the largest consumer of packaging films globally — continues to grow in parallel with urbanization, rising disposable incomes, and the deepening preference for packaged, ready-to-consume food formats across both developed and emerging markets. Simultaneously, the global e-commerce sector is driving substantial incremental demand for protective films, including stretch and shrink films used to bundle, wrap, and secure products during transit. It is estimated that as internet retail penetration deepens across Southeast Asia, Latin America, and Africa through 2036, the need for lightweight, durable, and cost-effective protective packaging films will grow significantly. The pharmaceutical and healthcare sector further contributes to this demand, where strict product safety requirements and the growth of generic drug manufacturing in emerging markets are expanding the adoption of high-barrier blister films, lidding films, and medical device packaging films.
Table of contents
11 chapters · 125 sections · 287 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Material Type | Polyethylene (PE) Films | — |
| By Film Structure | Multilayer Films | — |
| By Manufacturing Technology | Biaxially Oriented Films | — |
| By End-use | Food and Beverage | Pharmaceutical and healthcare |
By Material Type
- The polyethylene films segment accounts for the largest share of the overall packaging films market in 2026.
- This dominance is primarily attributed to the exceptional versatility, cost efficiency, and established processing compatibility of polyethylene-based films across the broadest range of packaging applications globally.
- Low-density polyethylene (LDPE) and linear low-density polyethylene (LLDPE) films are widely used in stretch and cling film formats for food wrapping, pallet wrapping, and produce packaging, while high-density polyethylene (HDPE) films find strong demand in carrier bags, heavy-duty sacks, and agricultural applications.
- The structural shift toward mono-material polyethylene laminates designed to replace conventional mixed-material flexible packaging with a fully recyclable PE-based alternative — is further reinforcing the dominance of this segment by expanding PE film consumption into lamination applications where polyester and polyamide substrates have historically dominated.
- However, the polypropylene (PP) films segment is expected to grow at a rapid CAGR during the forecast period, driven by the strong expansion of biaxially oriented polypropylene (BOPP) films in food and confectionery packaging, label stock, and over-wrapping applications, as well as growing interest in oriented polypropylene as a platform for mono-material flexible packaging.
By Film Structure
- The multilayer films segment holds the largest share of the overall market in 2026.
- This is primarily due to the ability of multilayer coextrusion and lamination technologies to combine dissimilar materials into a single, optimized film construction that simultaneously delivers barrier performance, mechanical strength, sealability, printability, and processability — properties that no single-layer film can provide at the required performance level for demanding food, pharmaceutical, and industrial applications.
- Current large-scale food and pharmaceutical packaging operations increasingly specify five-layer and seven-layer film structures incorporating EVOH barrier layers and polyamide components to achieve the oxygen and moisture transmission specifications required for vacuum, modified atmosphere, and retort packaging formats.
- The monolayer films segment, while smaller in value share, is expected to witness steady demand growth during the forecast period, particularly in stretch film, agricultural film, and industrial wrapping applications where barrier complexity is not required and cost efficiency and high throughput are the dominant purchasing criteria.
By Manufacturing Technology
- The biaxially oriented films segment holds the largest share of the overall packaging films market in 2026.
- The biaxial orientation process — which stretches polymer films simultaneously or sequentially in both the machine and transverse directions — imparts significantly enhanced tensile strength, optical clarity, dimensional stability, and barrier performance compared to non-oriented equivalents.
- Biaxially oriented polypropylene (BOPP) and biaxially oriented polyethylene terephthalate (BOPET) films are among the most widely used flexible packaging substrates globally, serving as primary webs in laminated structures for snack food, confectionery, beverage labeling, and retort packaging applications.
- The blown films segment, while holding a comparably large volume share, demonstrates particular strength in stretch wrap, produce packaging, heavy-duty sacks, and agricultural film applications, where the toughness and puncture resistance achievable through the blown process are valued over optical clarity.
- The cast films segment is growing steadily in applications requiring superior surface smoothness and heat sealability, particularly in cast polypropylene (CPP) sealant films used in laminated retort pouches and food packaging overwraps.
By End-use
- The food and beverage segment commands the largest share of the global packaging films market in 2026.
- This dominance stems from its unmatched scale of consumption across a vast and diverse product portfolio — encompassing dry foods, fresh and frozen produce, dairy, meat and seafood, confectionery, snacks, beverages, and ready-to-eat meals — each of which requires film-based packaging solutions tailored to its specific preservation, presentation, and distribution requirements.
- Large-scale food producers and retailers globally depend on packaging films for portion control, product visibility, tamper evidence, and the shelf-life extension that reduces food waste and supports longer-distance distribution.
- Advanced film systems from manufacturers such as Sealed Air Corporation and Coveris Holdings S.A. are enabling reliable performance in high-speed automated packaging environments, reducing downtime and material waste for food processors.
- The pharmaceutical and healthcare segment is poised for the fastest growth through 2036, fueled by expanding demand for high-barrier blister and lidding films in generic drug manufacturing, the growth of biologics and medical device packaging requirements, and increasing pharmaceutical production capacity investments across Asia-Pacific and Latin America.
- Manufacturers face mounting pressure to develop films that meet both functional specifications and the traceability and serialization requirements of global pharmaceutical regulatory authorities.
Geographic analysis
Asia-Pacific
Largest shareAsia-Pacific holds the largest share of the global packaging films market in 2026. The region's dominance is primarily attributed to its position as both the world's largest consumer and largest producer of packaging films, underpinned by massive food processing industries, a rapidly expanding middle-class consumer base, and the presence of globally significant film manufacturing capacity. China alone accounts for a substantial portion of global packaging film production, with its extensive polyethylene, BOPP, and BOPET film manufacturing infrastructure supporting both domestic consumption and significant export volumes. India represents the region's fastest-growing major market, driven by rapid urbanization, the formalization of modern retail and e-commerce channels, rising packaged food consumption, and strong domestic film manufacturing capacity additions from players such as Uflex Ltd., Jindal Poly Films Ltd., and Cosmo First Ltd.
North America
North America and Europe together account for a substantial share of the global packaging films market. The growth of these markets is primarily driven by the ongoing shift toward sustainable and recyclable film structures, continued innovation in high-barrier and specialty film grades, and the sustained demand from well-established food, beverage, pharmaceutical, and industrial end-use sectors. In North America, the rapid expansion of e-commerce and the associated demand for protective stretch and shrink films, combined with strong investment in recyclable packaging innovation by leading brand owners and film converters, supports steady market growth. Players such as Berry Global Inc., Sealed Air Corporation, Winpak Ltd., and ProAmpac LLC are at the forefront of product development across both functional performance and sustainability dimensions.
Europe
In Europe, the stringent regulatory environment around packaging recyclability and single-use plastics — including the EU Packaging and Packaging Waste Regulation (PPWR) and Extended Producer Responsibility frameworks — is the primary structural force reshaping the market. Countries such as Germany, France, and the United Kingdom are at the forefront of mono-material film adoption and closed-loop recycling infrastructure development. Leading film manufacturers operating in the region, including Mondi Group plc, Coveris Holdings S.A., and Taghleef Industries Group, are investing substantially in next-generation recyclable and bio-based film development to align with evolving regulatory and brand owner requirements.
Competitive landscape
- Amcor plc
- Berry Global Inc.
- Sealed Air Corporation
- Mondi Group plc
Frequently asked questions
The global packaging films market is expected to grow from USD 113.8 billion in 2026 to USD 189.7 billion by 2036.
Cite this report
Meticulous Research. (2026). Packaging Films Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1802). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/packaging-films-market-6485