Optometry Equipment Market (2025-2032)
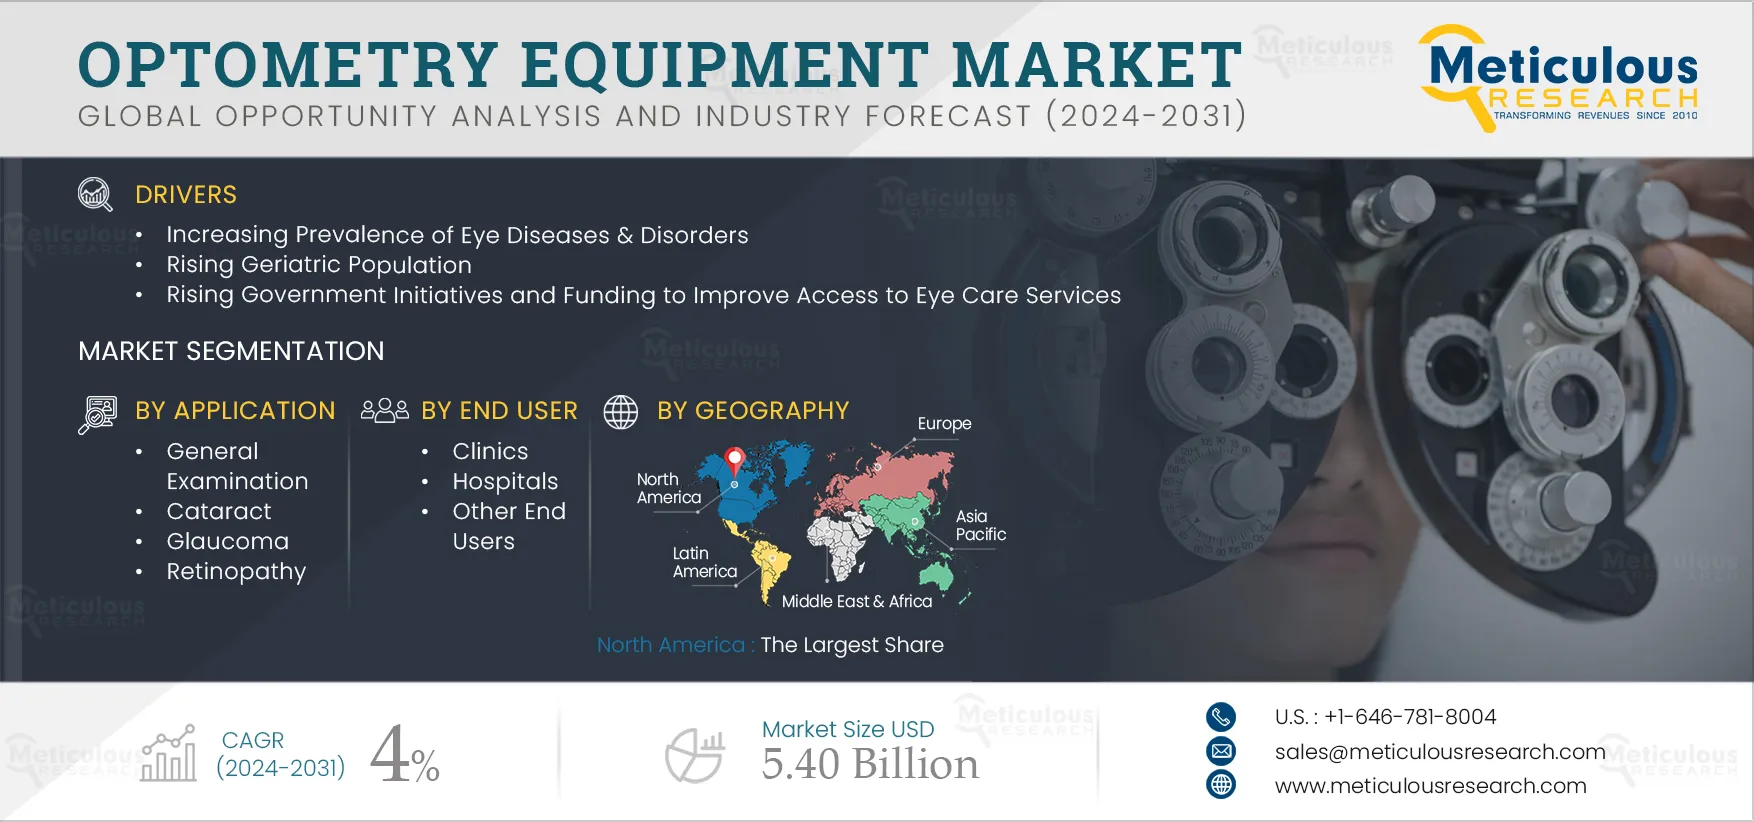
The Optometry Equipment Market is expected to reach $5.40 billion by 2032, at a CAGR of 4% from 2025 to 2032.
- Published
- Jan 2025
- Pages
- 270
- Format
- PDF + Excel
- Report ID
- MRHC - 104722
- Base year
- 2024
- 2032 · FORECAST
- $5.40B
- 2032
- $5.40B
- CAGR 2025–2032
- 4%
2024 baseline · 2025–2032 forecast at 4% CAGR · hover a bar for the value
Key highlights
By Type: The Retina & Glaucoma Examination Products Segment to Dominate the Optometry Equipment Market in 2025
By Application: The General Examination Segment to Account for the Largest Share of the Market in 2025
By End User: The Clinics Segment to Account for the Largest Share of the Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 270 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 4% |
| Market Size (Value) | USD 5.40 Billion by 2032 |
| Segments Covered | By Type · Retina & Glaucoma Examination Products · OCT Scanners · Perimeters · Fundus Cameras · Retinoscopes · Ophthalmoscopes, Ophthalmic Lasers, and Ophthalmic Microscopes · Keratometers, Autorefractors, and Lensometers · Ophthalmic Ultrasound Systems and Digital Phoropters · Slit Lamps · Tonometers · Retinal Imaging Systems · General Examination Products · Chart Projectors · Cataract & Cornea Examination Products · Specular Microscopes · Corneal Topography System · Wavefront Analyzers & Aberrometers · Optical Biometry Systems · By Application · General Examination · Cataract · Age-related Macular Degeneration · Glaucoma · Retinopathy · Other Applications · (Note: Other applications include refractive errors, amblyopia, strabismus, and floaters.) · By End User · Clinics · Hospitals · Other End Users · (Note: Other end users include academic & research institutes and retail optician shops.) |
| Countries Covered | North America (U.S. and Canada), Europe (Germany, France, U.K., Italy, Spain, Netherlands, Switzerland, Sweden, Belgium and Rest of Europe), Asia-Pacific (China, Japan, India, Indonesia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa |
| Key Companies Profiled | NIDEK CO. LTD. (Japan), Carl Zeiss Meditec AG (Germany), Novartis AG (Switzerland), Heidelberg Engineering GmbH (Germany), Johnson & Johnson (U.S.), Canon, Inc. (Japan), Bausch Health Companies Inc. (Canada), Escalon Medical Corp (U.S.), Topcon Healthcare Solutions, Inc. (U.S.), and HEINE Optotechnik GmbH & Co. KG (Germany) |
Report overview
Segments covered: type, retina & glaucoma examination product, oct scanner, perimeter, fundus camera, ophthalmic laser, keratometer, autorefractor, lensometer, ophthalmic ultrasound system, digital phoropter, slit lamp, tonometer, retinal imaging system, general examination product, chart projector, cataract & cornea examination product, corneal topography system, wavefront analyzers & aberrometer, optical biometry system, application, general examination, cataract, age-related macular degeneration, glaucoma, retinopathy, other application, end user, clinic, hospital, other end user. Regions: North America, Europe, Asia-Pacific, Latin America.
The growth of the optometry equipment market is driven by factors such as the rising prevalence of eye diseases and disorders, the growing geriatric population, the increasing number of individuals with visual impairments due to the excessive use of laptops and mobile phones, and rising government initiatives and funding to improve access to eye care services. However, the shortage of eye care professionals may restrain market growth.
Moreover, emerging economies, the rise in specialty optometric practices, and the increasing use of telehealth and telemedicine by eye doctors and patients are expected to create market growth opportunities. However, a lack of knowledge about the use of advanced optometry instruments among healthcare professionals poses a major challenge to market growth.
Additionally, the use of artificial intelligence (AI) for the diagnosis and treatment of various eye conditions is a prominent trend in the optometry equipment market.
Report infographic
Market dynamics
5 factors across 3 forcesIncreasing Cases of Eye diseases and Disorders
Glaucoma, cataracts, and refractive errors are among the major causes of preventable blindness and visual impairment. According to the data published by the WHO in 2022, nearly 2.2 billion people worldwide had vision impairment or blindness, with over 1 billion of these cases being preventable or yet to be addressed. Moreover, as per the Cleveland Clinic's 2022 statistics, approximately 3.4 million individuals in the U.S. aged 40 and above meet the criteria for 'legal blindness.' Additionally, around 7% of children have previously received diagnoses for eye conditions or diseases, with about 3% of children under 18 being blind or experiencing vision impairment. The most common eye diseases or conditions include age-related macular degeneration, diabetes-related retinopathy, cataracts, and glaucoma. Thus, the rising prevalence of eye-related diseases and disorders is driving the demand for optometry equipment.
Rising Geriatric Population
The aging population and the subsequent rise in the prevalence of eye diseases are driving the demand for optometry equipment. This equipment is crucial for diagnosing, treating, and monitoring patients at risk of vision-threatening chronic conditions like diabetic retinopathy. According to data published by Rendia, Inc. (U.S.) in 2022, optometrists diagnose approximately 400,000 patients annually in the U.S. who have diabetic neuropathy but are unaware of their diabetic condition. Moreover, vision impairment affects more than 2.9 million people in the U.S. (Source: National Center for Chronic Disease Prevention and Health Promotion). Globally, 65% of individuals above the age of 60 are visually impaired, with nearly 4% experiencing blindness. Therefore, the increasing demand for optometry equipment tailored to the needs of the geriatric population is driving the market's growth.
Table of contents
11 chapters · 112 sections · 270 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Retina & Glaucoma Examination Products | General examination products |
| By Application | General Examination | — |
| By End User | Clinics | — |
By Type
- The retina & glaucoma examination products segment is expected to account for the largest share of 24.0% of the optometry equipment market.
- This segment's large market share can be attributed to the high prevalence of glaucoma and the increasing incidence of retinal tears, diabetic retinopathy, and macular degeneration.
- According to data published in the scientific journal BMC Ophthalmology in 2024, diabetic retinopathy affects nearly 27% of patients with diabetes mellitus.
- Retina & glaucoma examination products play a crucial role in enabling early detection, ensuring safety, and providing detailed documentation and monitoring of disease progression.
- Additionally, these examination products contribute to maintaining clear vision and optimal eye function.
- However, the general examination products segment is projected to register the highest CAGR during the forecast period.
By Application
- The general examination segment is expected to account for the largest share of 38.0% of the market.
- General examinations encompass various tests to assess the health, functionality, and appearance of different parts of the eye.
- The large market share of this segment can be attributed to the rise in visual impairments stemming from the increasing utilization of laptops and mobile phones and the growing geriatric population, which is fueling the demand for general examinations.
- As a result, there is a rising demand for optometry equipment for facilitating general examinations.
By End User
- The clinics segment to account for the largest share of the market.
- This segment's large market share can be attributed to the large number of private clinics in developed nations, patients' inclination towards ophthalmic clinics for the diagnosis and treatment of eye conditions, and the timely appointments and cost-effectiveness offered by these clinics.
Geographic analysis
North America
Largest shareIn 2025, North America is expected to account for the largest share of 39.3% of the optometry equipment market, followed by Europe and Asia-Pacific. In 2025, the U.S. is expected to account for the larger share of the optometry equipment market in North America. The country's significant market share can be attributed to the widespread adoption of advanced optometry equipment for eye care, the presence of major market players, and the well-established healthcare system. Additionally, high spending on eye care in the U.S. contributes to the significant market share. For instance, according to data from the American Optometric Association's 2020 whitepaper, major eye conditions among adults aged over 40 in the U.S. result in an annual economic impact exceeding USD 145 billion, a figure which is expected to rise with the increasing geriatric population.
Asia-Pacific
Fastest growthHowever, the market in Asia-Pacific is projected to register the highest CAGR of 5.7% during the forecast period. The growth of this regional market can be attributed to the growing geriatric population, increasing healthcare expenditures, and initiatives by major market players to establish a stronger presence in the region. Furthermore, the surge in eye infections and diseases contributes to the market's growth. For instance, a significant outbreak of viral pink eye disease, also known as conjunctivitis, affected a considerable number of individuals in countries such as India, Vietnam (63,000 individuals), and Pakistan (400,000 individuals).
Competitive landscape
- March 2025
The Optical Company (TOC) (U.S.) completed the acquisition of Adelaide Eye Care (AEC) (U.S.), thereby expanding its operational reach to 60 new locations. This acquisition enhanced TOC's capabilities in diagnostic technology and personalized optical dispensing.
- February 2024
NIDEK CO., LTD. (Japan) launched the AL-Scan M Optical Biometer along with the MV-1 Myopia Viewer software. The AL-Scan M is designed to measure axial length, aiding in the prediction and monitoring of myopia progression for both scientific and clinical purposes.
- April 2024
NIDEK CO., LTD. (Japan) launched the NT-1/1e Non-Contact Tonometer series, comprising three devices.
- November 2022
Advancing Eyecare (AEC) acquired Veatch Ophthalmic Instruments (U.S.). This acquisition enabled AEC to expand its offerings in the ophthalmic segment.
- NIDEK CO. LTD. · Japan
- Carl Zeiss Meditec AG · Germany
- Novartis AG · Switzerland
- Heidelberg Engineering GmbH · Germany
- Johnson & Johnson (U.S.)
- Canon, Inc. · Japan
- Bausch Health Companies Inc. · Canada
- Escalon Medical Corp (U.S.)
- Topcon Healthcare Solutions, Inc. (U.S.)
- HEINE Optotechnik GmbH & Co. KG · Germany
Frequently asked questions
This study offers a detailed assessment of the optometry equipment market, including the market sizes & forecasts for market segments categorized by type, application, and end user. The study also provides an in-depth analysis of various segments & subsegments of the optometry equipment market at the regional and country levels.
Cite this report
Meticulous Research. (2025). Optometry Equipment Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 104722). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/optometry-equipment-market-5406