Medical Laser Market (2024-2031)
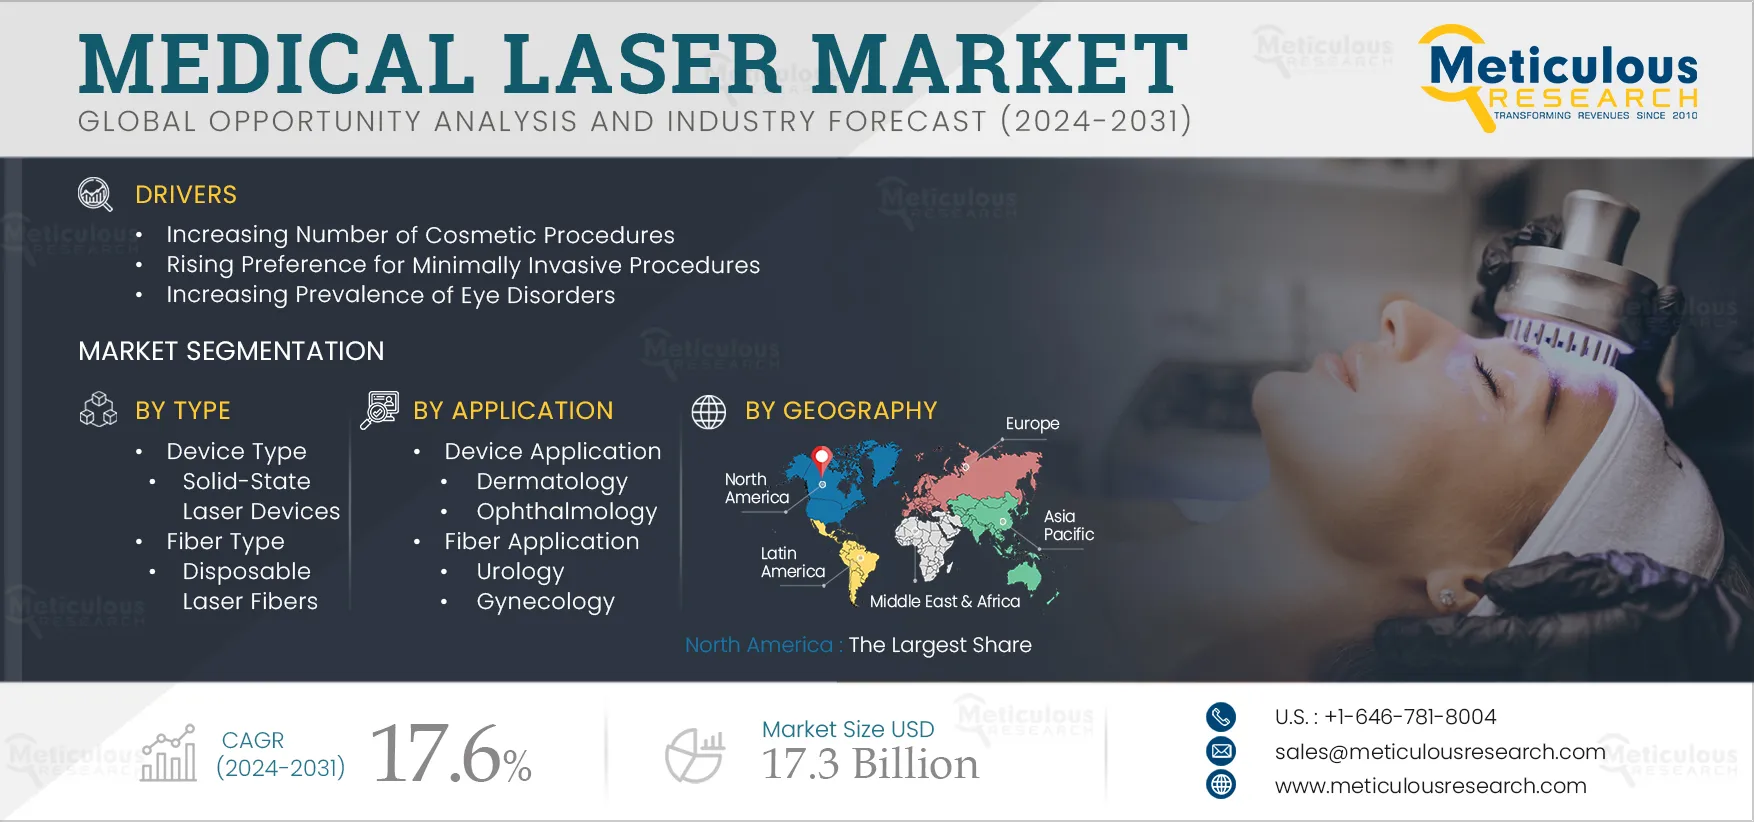
The Medical Laser Market is expected to reach $17.3 billion by 2031, at a CAGR of 17.6% from 2024 to 2031.
- Published
- Jun 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRSE - 104503
- Base year
- 2023
- 2031 · FORECAST
- $17.30B
- 2031
- $17.30B
- CAGR 2024–2031
- 17.6%
2023 baseline · 2024–2031 forecast at 17.6% CAGR · hover a bar for the value
Key highlights
By Device Type: In 2024, the Solid-State Laser Devices Segment to Dominate the Medical Laser Devices Market
By Fiber Type: In 2024, the Disposable Laser Fibers Segment to Dominate the Medical Laser Fibers Market
By Device Application: In 2024, the Dermatology Segment to Dominate the Medical Laser Devices Market
By Fiber Application: In 2024, the General Surgeries Segment to Dominate the Medical Laser Fibers Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 17.6% |
| Market Size (Value) | USD 17.3 Billion by 2031 |
| Segments Covered | By Type · Device Type · Solid-State Laser Devices · Neodymium Yttrium Aluminum Garnet Laser Devices (Nd:YAG) · Erbium Yttrium Aluminum Garnet Laser Devices (Er:YAG) · Holmium Yttrium Aluminum Garnet Laser Devices (Ho:YAG) · Alexandrite Laser Devices · Potassium Titanyl Phosphate Laser Devices · Ruby Laser Devices · Gas Laser Devices · CO2 Laser Devices · Excimer Laser Devices · Argon Laser Devices · Helium-Neon (He-Ne) Laser Devices · Krypton Laser Devices · Metal Vapor (Copper and Gold) Laser Devices · Diode Laser Devices · Dye Laser Devices · Fiber Type · Disposable Laser Fibers · Reusable Laser Fibers · By Application · Device Application · Dermatology · Ophthalmology · Urology · Dentistry · Cardiology · Gynecology · Other Device Applications · Fiber Application · General Surgeries · Urology · Dermatology · Gynecology · Cardiology · Dentistry · Other Fiber Applications |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Rest of Asia-Pacific), Latin America (Mexico, Brazil, Rest of Latin America), and the Middle East & Africa (UAE, Israel, Rest of Middle East & Africa) |
| Key Companies | Lumenis Ltd. (Israel), Fotona d.o.o. (Slovenia), BIOLASE, Inc. (U.S.), IRIDEX Corporation (U.S.), Cutera, Inc. (U.S.), Alna-Medicalsystem AG & Co. KG (Germany), Bausch & Lomb Incorporated (U.S.), Boston Scientific Corporation (U.S.), Alcon, Inc. (Switzerland), Stryker Corporation (U.S.), Alma Lasers (Israel), biolitec AG (Germany), Bluecore, Inc. (South Korea), Cynosure LLC (U.S.), PhotoMedex (U.S.) and Spectranetics (U.S.) MED-Fibers, INC.(U.S.), Clarion Medical Technologies (Canada), Olympus Corporation (Japan) |
Report overview
Segments covered: type, application. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of this market is attributed to the increasing number of cosmetic procedures, rising preference for minimally invasive procedures, and increasing prevalence of eye disorders. Moreover, the growth of medical tourism is expected to offer growth opportunities for the players operating in this market.
Report infographic
Market dynamics
3 factors across 2 forcesIncreasing Number of Cosmetic Procedures Drives the Growth of the Medical Laser Market
There has been an increase in the demand for laser cosmetic procedures, such as body contouring, skin tightening, hair removal, dermabrasion, acne, wrinkles, and skin rejuvenation procedures. Aesthetic laser devices are preferred over other devices due to various advantages, including ease of use, minimal invasiveness, and less time consumption.
Researchers are also working on applying artificial intelligence (AI) in medical lasers for cosmetic surgeries. AI technology can be used in medical lasers as it has several benefits. It eliminates human error, reduces potential risks and side effects, provides high precision, and simplifies treatments for doctors.
Growing awareness among people about aesthetics, growing adoption of surgeries, and growing affordability of advanced treatments such as acne and scar removal, among others, is expected to increase the demand for medical lasers. Various factors, such as increasing advancements in technologies in aesthetic procedures, increased focus on body appearance, high disposable income, rising problems of obesity, and rising number of private clinics and surgeons providing treatments, are increasing the demand for medical lasers in the cosmetics industry.
Rising Preference for Minimally Invasive Procedures Drives the Growth of the Medical Laser Market
Minimally invasive surgery is a procedure that is performed through tiny incisions instead of a large opening. This surgery has several benefits, such as smaller incisions, less pain, minimal to no scars, less blood loss, and a lower complication rate. As the demand for treatments such as microdermabrasion, laser hair removal, and several other treatments is increasing, the need for minimally invasive procedures is also growing. Factors such as the increasing number of surgeries and rising diagnoses of various disorders, such as appendicitis, cancer, and cardiovascular diseases, drive the demand for these procedures. MIS surgeries are widely adopted among the geriatric population due to the relatively shorter recovery time and less pain. Minimally invasive surgery has become a standard surgical technique in many routine operations that include:
- Adrenalectomy to remove one or both adrenal glands
- Appendectomy to remove the appendix
- Cancer surgery to destroy a tumor
- Cholecystectomy to remove the gallbladder
- Colectomy to remove parts of a diseased large bowel
- Endovascular surgery to treat or repair aneurysms
- Hiatal hernia repair to relieve gastroesophageal reflux disease
- Splenectomy to remove the spleen
Such factors are expected to stimulate the demand for minimally invasive procedures, further supporting market growth.
Table of contents
10 chapters · 126 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Device Type | Solid-State Laser Devices | Diode lasers |
| By Fiber Type | Disposable Laser Fibers | — |
| By Device Application | Dermatology | Urology |
| By Fiber Application | General Surgeries | Cardiology |
By Device Type
- The solid-state laser devices segment is expected to account for the largest share of above 45% of the medical laser devices market.
- The large market share of this segment is attributed to the increasing use of solid-state lasers in medical applications, such as treatment processes for scar removal, melisma treatment, and skin resurfacing, which has encouraged various healthcare facilities to adopt these lasers for performing treatments.
- Various advantages associated with solid-state lasers, such as high efficiency compared to gas lasers, simple construct than to other lasers, and economical nature of solid-state lasers, are driving the growth of this segment.
- However, the diode lasers segment is projected to register the highest CAGR during the forecast period.
- The segment's growth is attributed to the preference for these lasers in various surgical procedures, such as hair removal, soft tissue cutting, aesthetic procedures, dental surgeries, coagulation, and thermal cancer therapy.
- Diode lasers deliver wavelengths ranging from 810 to 1064 nm.
- They are compact and portable solid-state units.
By Fiber Type
- The disposable laser fibers segment is expected to account for the larger share of above 75% of the medical laser fibers market.
- The large market share of this segment is attributed to the increasing use of laser fiber in diagnostic procedures, rising demand for non-invasive surgical procedures, the effective cost of disposable laser fibers, and the increasing number of urologic and plastic surgery procedures.
- Moreover, this segment is also projected to register the highest CAGR during the forecast period.
By Device Application
- The Dermatology Segment to Dominate the Medical Laser Devices Market
- The dermatology segment is expected to account for the largest share of above 31% of the medical laser devices market.
- The large market share of this segment is attributed to the increasing number of cosmetic surgeries simultaneously increasing the use of medical lasers in these treatments and increasing integration of AI technology for dermatology applications.
- These lasers are used for various treatments, such as vascular lesions, pigmented lesions and tattoos, hair removal, facial wrinkles, scars, sun-damaged skin, and skin cancers.
- However, the urology segment is projected to register the highest CAGR during the forecast period.
- The segment's growth is attributed to the rising number of kidney diseases, increasing urinary tract infections, the growing elderly population, and rising chronic kidney disorders.
- Different types of lasers are used in urology, such as KTP:YAG (potassium titanyl phosphate), LBO:YAG (lithium borate), diode lasers, holmium (Ho):YAG, and thulium (Tm):YAG lasers, among others.
By Fiber Application
- The general surgeries segment is expected to account for the larger share of above 27% of the medical laser fibers market.
- The large market share of this segment is attributed to the growing prevalence of colon cancer, appendicitis procedures, pancreatic cancer, and small and large intestine cancers.
- Medical laser fibers perform highly efficient surgeries and reduce the risk of cross-contamination between surgeries, increasing the demand for medical laser fibers.
- However, the cardiology segment is projected to register the highest CAGR during the forecast period.
- Cardiovascular surgeons use various types of laser fibers, such as Nd:YAG, holmium, and CO2, to treat patients suffering from heart disease, heart attack, stroke, or blood clots and individuals at high risk for developing these problems.
- The better outcomes and high efficiency of medical laser fibers have accelerated the demand for laser fibers in this segment.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of above 45% of the medical laser market. The market growth in North America is driven by the presence of major vendors in the region, technological advancements in medical devices, government investments to promote innovation in the healthcare segment and the exponential growth of aesthetic/cosmetic procedures. The aging population in the U.S. is creating the need for major surgeries related to geriatric populations, such as ophthalmic surgeries, including cataracts, glaucoma, cardiovascular surgeries, and urological surgeries, driving the demand for medical lasers in this region. In 2024, the North America Region to Dominate the Medical Laser Market
Asia-Pacific
Fastest growthHowever, Asia-Pacific is projected to record the highest CAGR of above 24% during the forecast period. The growth of medical tourism in most Asian countries, rising disposable income, growing awareness and adoption of minimally invasive aesthetic procedures, government support to provide better medical infrastructure, and the arrival of several medical device manufacturers in the region support the market growth in the region. In countries such as China and Japan, government bodies are introducing policies to support the standardization of the aesthetic medicine industry.
Competitive landscape
- February 2024
BIOLASE, Inc. (U.S.) launched Waterlase iPlus Premier Edition, an all-tissue laser system for dental care applications.
- February 2024
Meridian Medical AG (Switzerland) launched three new ophthalmic lasers, namely, Microruptor (MR) Q lasers: MR Q, MR Q SLT, and MR Q supine in the U.S.
- May 2021
Lumenis Ltd. partnered with Harrods Wellness Clinic to equip its aesthetic clinic with the Stellar M22. As a result, the clinic will offer the patients a multi-spot Nd:YAG to treat vascular and leg vein lesions on all skin types, and Q-Switched Nd:YAG will treat pigmented lesions and remove dark tattoos.
- Lumenis Ltd. · Israel
- Fotona d.o.o · Slovenia
- BIOLASE, Inc. (U.S.)
- IRIDEX Corporation (U.S.)
- Cutera, Inc. (U.S.)
- Alna-Medicalsystem AG & Co. KG · Germany
- Bausch & Lomb Incorporated (U.S.)
- Boston Scientific Corporation (U.S.)
- Alcon, Inc. · Switzerland
- Stryker Corporation (U.S.)
- Alma Lasers · Israel
- Bluecore, Inc. · South Korea
- Cynosure LLC (U.S.)
- PhotoMedex (U.S.) and Spectranetics (U.S.) MED-Fibers
- INC.(U.S.)
- Clarion Medical Technologies · Canada
- Olympus Corporation · Japan
Frequently asked questions
The medical laser market study focuses on market assessment and opportunity analysis through the sales of medical lasers across different regions and countries across different market segments. This study is also focused on competitive analysis for medical lasers based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). Medical Laser Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRSE - 104503). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/medical-lasers-market-5196