Hydrogen Fuel Cell Vehicles Market (2026-2036)
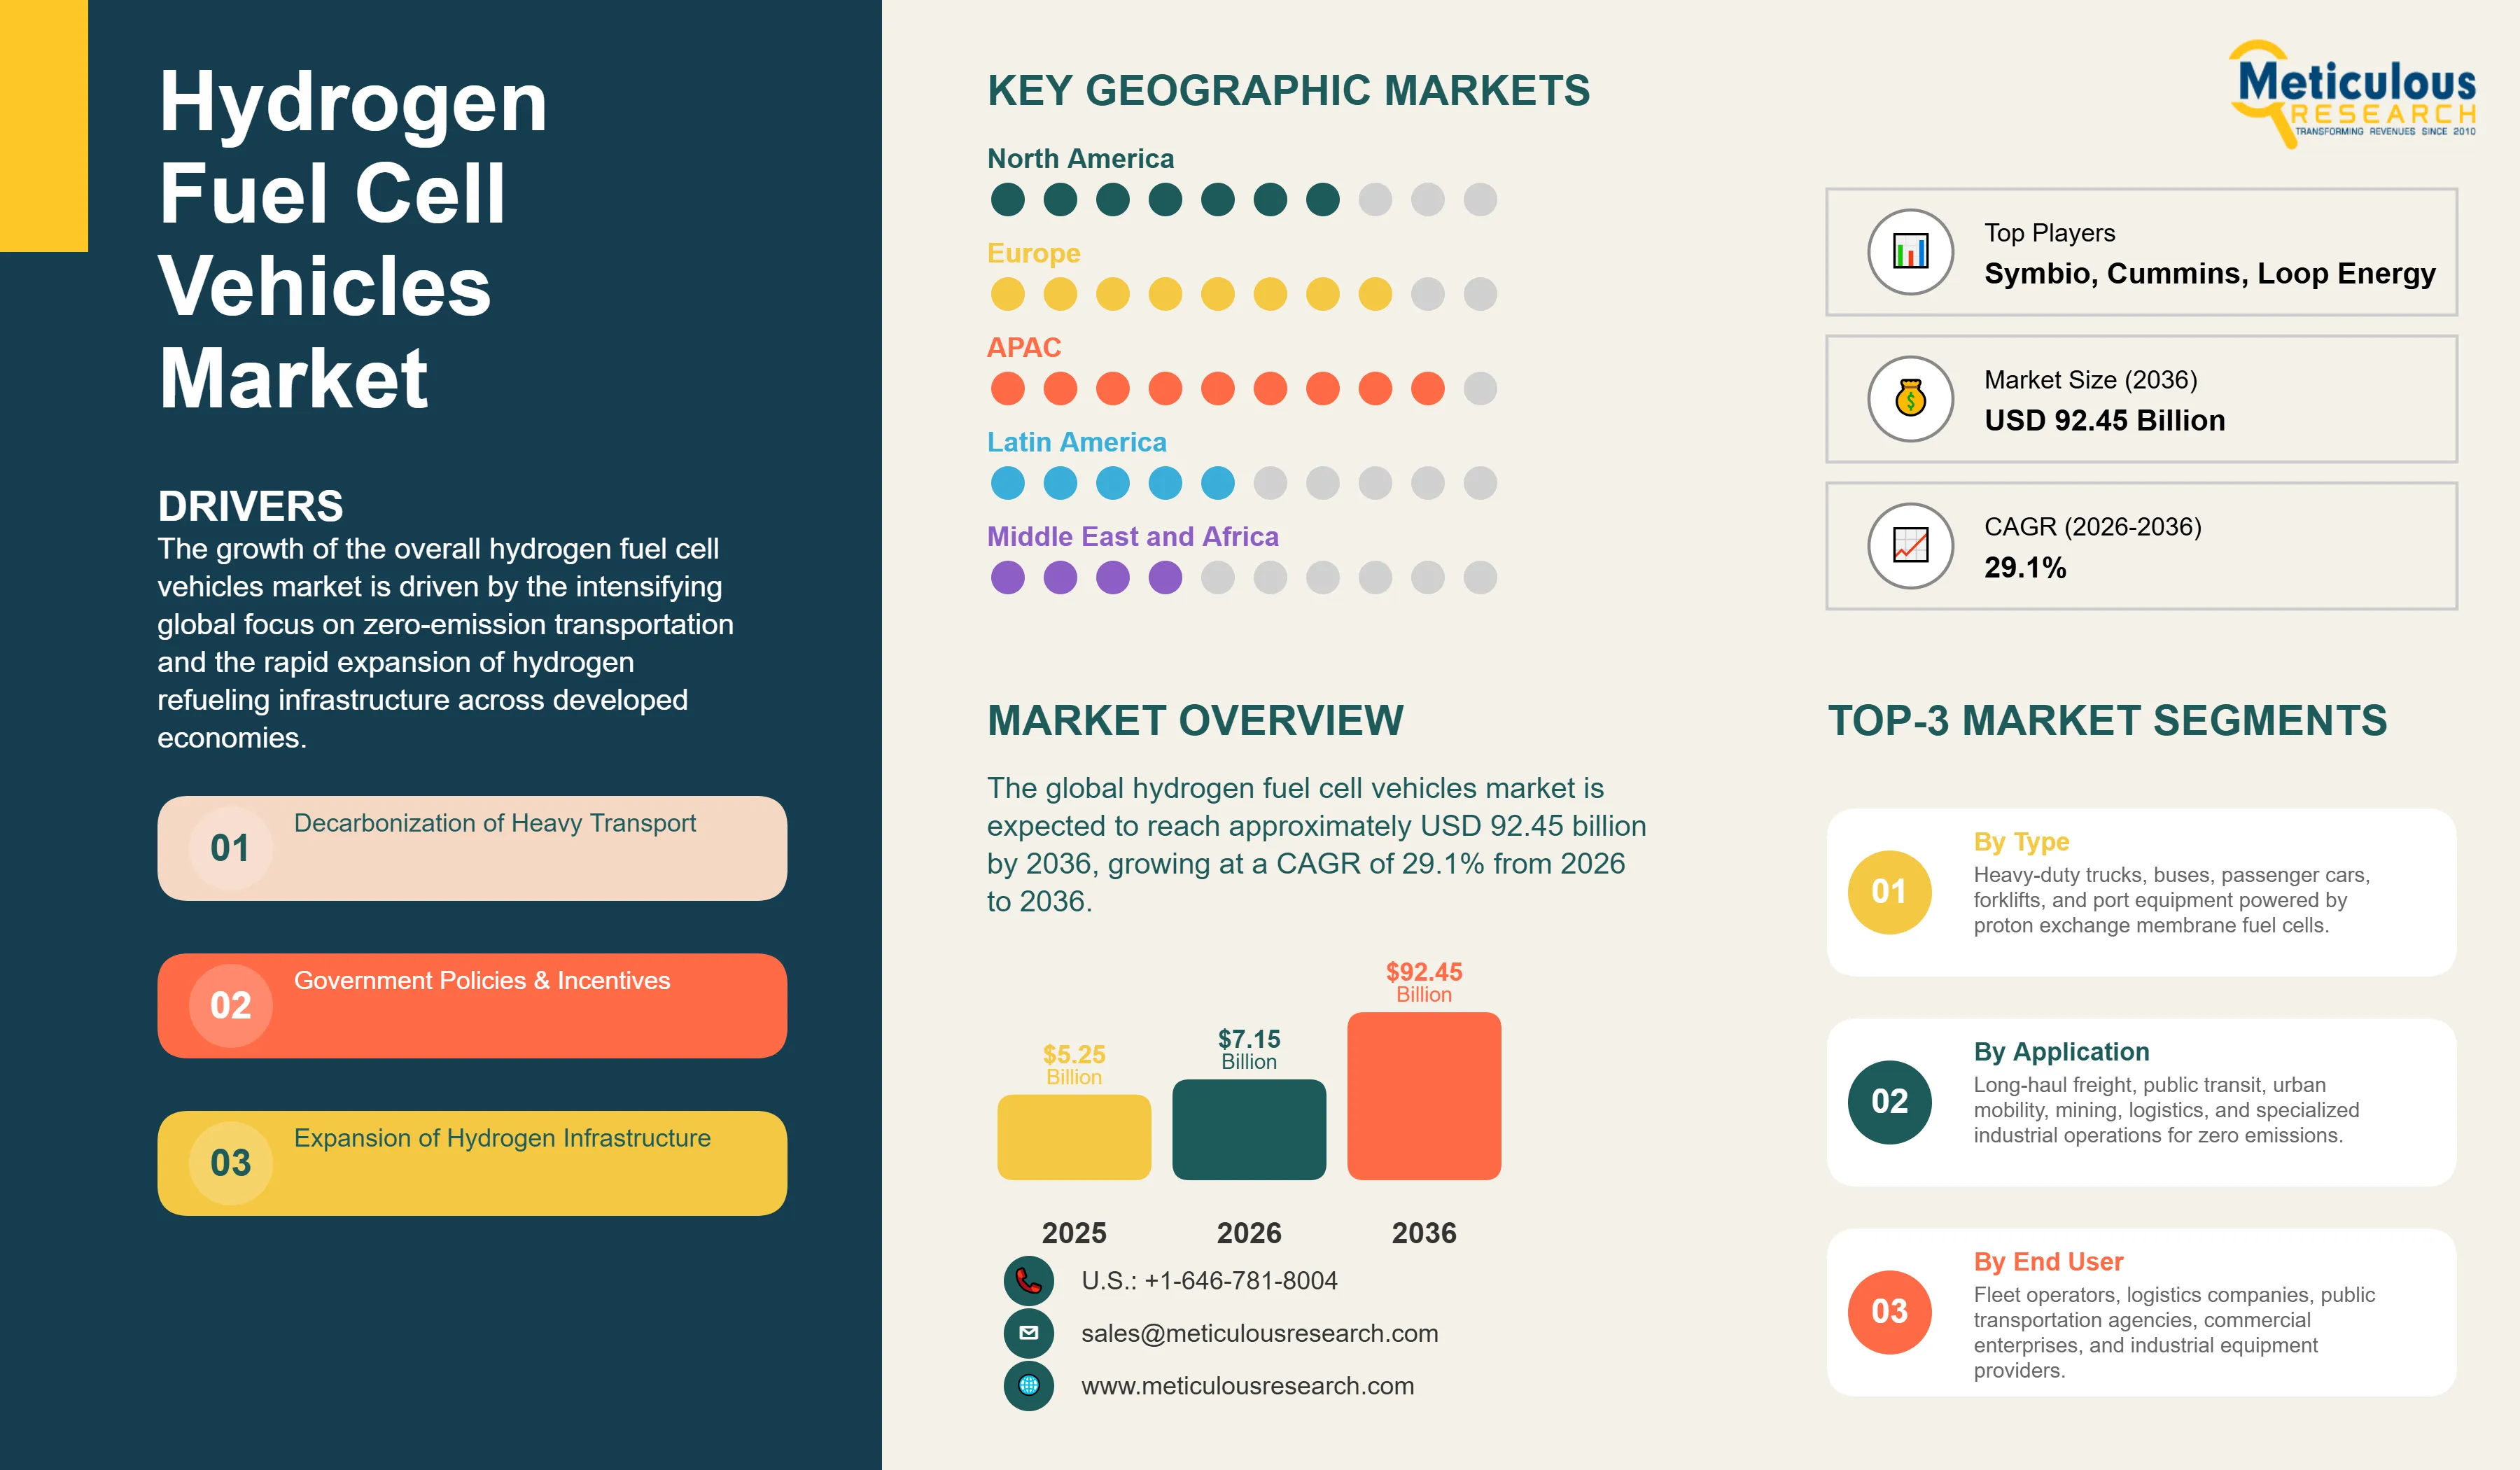
The global hydrogen fuel cell vehicles market was valued at USD 5.25 billion in 2025. The market is expected to reach approximately USD 92.45 billion by 2036 from USD 7.15 billion in 2026, growing at a CAGR of 29.1% from 2026 to 2036.
- Published
- Feb 2026
- Pages
- 255
- Format
- PDF + Excel
- Report ID
- MR-1737
- Base year
- 2025
- 2025 · BASELINE
- $5.25B
- 2036
- $92.45B
- CAGR 2026–2036
- 29.1%
2025 baseline · 2026–2036 forecast at 29.1% CAGR · hover a bar for the value
Key highlights
In terms of revenue, the global hydrogen fuel cell vehicles market is projected to reach USD 92.45 billion by 2036.
The market is expected to grow at a CAGR of 29.1% from 2026 to 2036.
Asia-Pacific dominates the global hydrogen fuel cell vehicles market with the largest market share in 2026, driven by aggressive hydrogen economy initiatives and the presence of leading automotive manufacturing hubs in South Korea, Japan, and China.
Europe is expected to witness rapid growth during the forecast period, supported by massive investments in hydrogen infrastructure and stringent emissions regulations driving commercial vehicle transitions in Germany, France, and the Netherlands.
By vehicle type, the heavy commercial vehicles segment holds the largest market share in 2026, particularly in supporting long-haul freight operations and mining equipment requiring extended range without lengthy charging stops.
By component, the fuel cell stack segment holds the largest market share in 2026, due to its critical role as the power generation core and continuous technology improvements reducing cost per kilowatt.
By technology, the proton exchange membrane (PEM) segment holds the largest share of the overall market in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 92.45 Billion |
| Market Size in 2026 | USD 7.15 Billion |
| Market Size in 2025 | USD 5.25 Billion |
| Market Growth Rate (2026-2036) | CAGR of 29.1% |
| Format | PDF, Excel & Cloud Portal · 255 pages |
| Dominating Region | Asia-Pacific |
| Fastest Growing Region | Europe |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
| Segments Covered | Vehicle Type, Component, Technology, Range, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Report overview
Segments covered: vehicle type, component, technology, range.
The growth of the overall hydrogen fuel cell vehicles market is driven by the intensifying global focus on zero-emission transportation and the rapid expansion of hydrogen refueling infrastructure across developed economies. As automotive manufacturers seek to integrate more sustainability into their commercial vehicle fleets and long-haul transportation systems, hydrogen fuel cell technology has become essential for maintaining high-performance operations without battery weight constraints. The rapid expansion of government subsidies for clean hydrogen production and the increasing need for heavy-duty zero-emission vehicles in freight and public transportation continue to fuel significant growth of this market across all major geographic regions.
Hydrogen fuel cell vehicles represent critical zero-emission transportation platforms that leverage advanced electrochemical technologies to provide optimized mobility solutions and improved operational efficiency through clean energy architectures. These systems include integrated fuel cell stacks, hydrogen storage tanks, and power electronics designed to convert hydrogen into electricity while emitting only water vapor across the automotive continuum. The market is defined by high-efficiency technologies such as proton exchange membrane fuel cells and compressed hydrogen storage systems at 700 bar pressure, which significantly enhance energy density and operational range in high-demand transportation environments. These systems are indispensable for fleet operators seeking to optimize their emissions profiles and meet aggressive decarbonization targets without compromising vehicle productivity or operational flexibility.
The market includes a diverse range of solutions, ranging from light-duty fuel cell passenger cars for urban mobility to complex heavy-duty fuel cell trucks and specialized applications including buses, forklifts, and port equipment. These systems are increasingly integrated with advanced components such as regenerative braking systems and hybrid battery buffers to provide services such as peak power delivery and energy recovery during deceleration. The ability to provide stable, high-power output while minimizing refueling downtime has made hydrogen fuel cell technology the choice for operators where range anxiety and operational continuity are paramount concerns in zero-emission fleet transitions.
The global transportation sector is pushing hard to decarbonize mobility systems, aiming to meet net-zero emission targets and air quality improvement goals. This drive has increased the adoption of high-efficiency hydrogen powertrains, with advanced fuel cell systems helping to enable zero-emission operations for weight-sensitive and range-intensive applications. At the same time, the rapid growth in the green hydrogen production market and declining electrolyzer costs are increasing the viability of sustainable hydrogen fuel pathways, creating synergies between renewable energy deployment and clean transportation infrastructure development.
Report infographic
Market dynamics
4 factors across 3 forcesDecarbonization of Heavy Transport and Government Policy Support
A key driver of the hydrogen fuel cell vehicles market is the rapid movement of the global transportation industry toward zero-emission heavy-duty mobility solutions. Global demand for emissions-free freight operations, extended range capabilities, and rapid refueling has created significant incentives for the adoption of hydrogen fuel cell infrastructure. The trend toward “electrification-of-everything” and the integration of hydrogen powertrains into commercial fleet platforms drive operators toward scalable solutions that fuel cell technology can uniquely provide. It is estimated that as regulatory pressure on diesel vehicles intensifies and hydrogen production costs decline through 2036, the need for robust, long-range zero-emission solutions increases significantly; therefore, fuel cell-driven powertrains and high-pressure hydrogen storage, with their ability to ensure operational parity with conventional trucks, are considered a crucial enabler of modern sustainable logistics strategies.
Table of contents
11 chapters · 91 sections · 255 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Vehicle Type | Heavy Commercial Vehicles | — |
| By Component | Fuel Cell Stack | — |
| By Technology | Proton Exchange Membrane | — |
By Vehicle Type
- The heavy commercial vehicles segment accounts for a significant portion of the overall hydrogen fuel cell vehicles market in 2026.
- This is mainly attributed to the critical advantages of this vehicle class in supporting long-haul freight operations, regional distribution networks, and weight-sensitive applications within modern logistics environments.
- Heavy-duty fuel cell trucks offer the most comprehensive solution to range and refueling time constraints that limit battery-electric alternatives in commercial operations.
- The freight and logistics sectors alone consume a large share of hydrogen fuel cell vehicle production, with major deployments in Europe and Asia demonstrating the technology’s capability to handle high-utilization duty cycles.
- However, the buses segment is expected to grow at a rapid CAGR during the forecast period, driven by the growing need for zero-emission public transportation in urban areas and transit agency commitments to fleet electrification with minimal charging infrastructure disruption.
By Component
- The fuel cell stack holds the largest share of the overall market in 2026.
- This is primarily due to the critical function of fuel cell stacks as the electrochemical power generation core and the continuous technology improvements reducing platinum loading and increasing power density.
- Current automotive-grade fuel cell systems are increasingly specifying high-efficiency membrane electrode assemblies to ensure compliance with vehicle performance standards and durability expectations for commercial applications exceeding 25,000 operating hours.
- The hydrogen storage system segment is expected to witness significant growth during the forecast period.
- The shift toward Type IV composite tanks at 700 bar pressure and the complexity of thermal management systems are pushing the requirement for advanced storage solutions that can handle diverse vehicle architectures and refueling protocols while ensuring absolute safety for crash scenarios and leak prevention.
By Technology
- The proton exchange membrane (PEM) segment commands the largest share of the global hydrogen fuel cell vehicles market in 2026.
- This dominance stems from its superior ability to operate at relatively low temperatures (60-80°C), provide rapid startup capabilities, and deliver high power density, making it the technology of choice for automotive applications.
- Large-scale deployments in passenger cars, trucks, and buses drive demand, with advanced PEM systems from Toyota, Hyundai, and Ballard Power enabling reliable performance in demanding transportation environments.
- However, the solid oxide fuel cell segment, while currently focused on stationary applications, is positioned for future automotive adoption through 2036, fueled by its potential for higher electrical efficiency and fuel flexibility enabling operation on hydrogen-natural gas blends during infrastructure transition periods.
Geographic analysis
Asia-Pacific
Largest shareAsia-Pacific holds the largest share of the global hydrogen fuel cell vehicles market in 2026. The largest share of this region is primarily attributed to the comprehensive hydrogen economy strategies and the presence of the world’s leading fuel cell vehicle manufacturers, particularly in South Korea, Japan, and China. South Korea and Japan together account for a significant portion of global fuel cell vehicle production, with their positions as early adopters of hydrogen mobility and extensive refueling networks driving sustained growth. The presence of leading manufacturers like Hyundai, Toyota, and Honda alongside well-developed component supply chains provides a robust market for both passenger and commercial fuel cell solutions.
North America
Europe and North America together account for a substantial share of the global hydrogen fuel cell vehicles market. The growth of these markets is mainly driven by the need for heavy-duty vehicle decarbonization in the commercial transport and public transit sectors. The demand for advanced fuel cell systems in Europe is mainly due to its ambitious climate targets and the presence of hydrogen infrastructure initiatives in Germany, France, and the Netherlands. In North America, the leadership in fuel cell technology development and the push for zero-emission commercial vehicles are driving the adoption of high-reliability hydrogen solutions. The United States and Canada are at the forefront, with significant focus on integrating fuel cell trucks into logistics workflows and transit bus fleets to ensure the highest levels of emissions reduction and operational reliability.
Competitive landscape
- Toyota Motor Corporation
- Hyundai Motor Company
- Ballard Power Systems Inc.
- Plug Power Inc.
Frequently asked questions
The global hydrogen fuel cell vehicles market is expected to grow from USD 7.15 billion in 2026 to USD 92.45 billion by 2036.
Cite this report
Meticulous Research. (2026). Hydrogen Fuel Cell Vehicles Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1737). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/hydrogen-fuel-cell-vehicles-market-6420