Europe Medical Image Management Market (2025-2032)
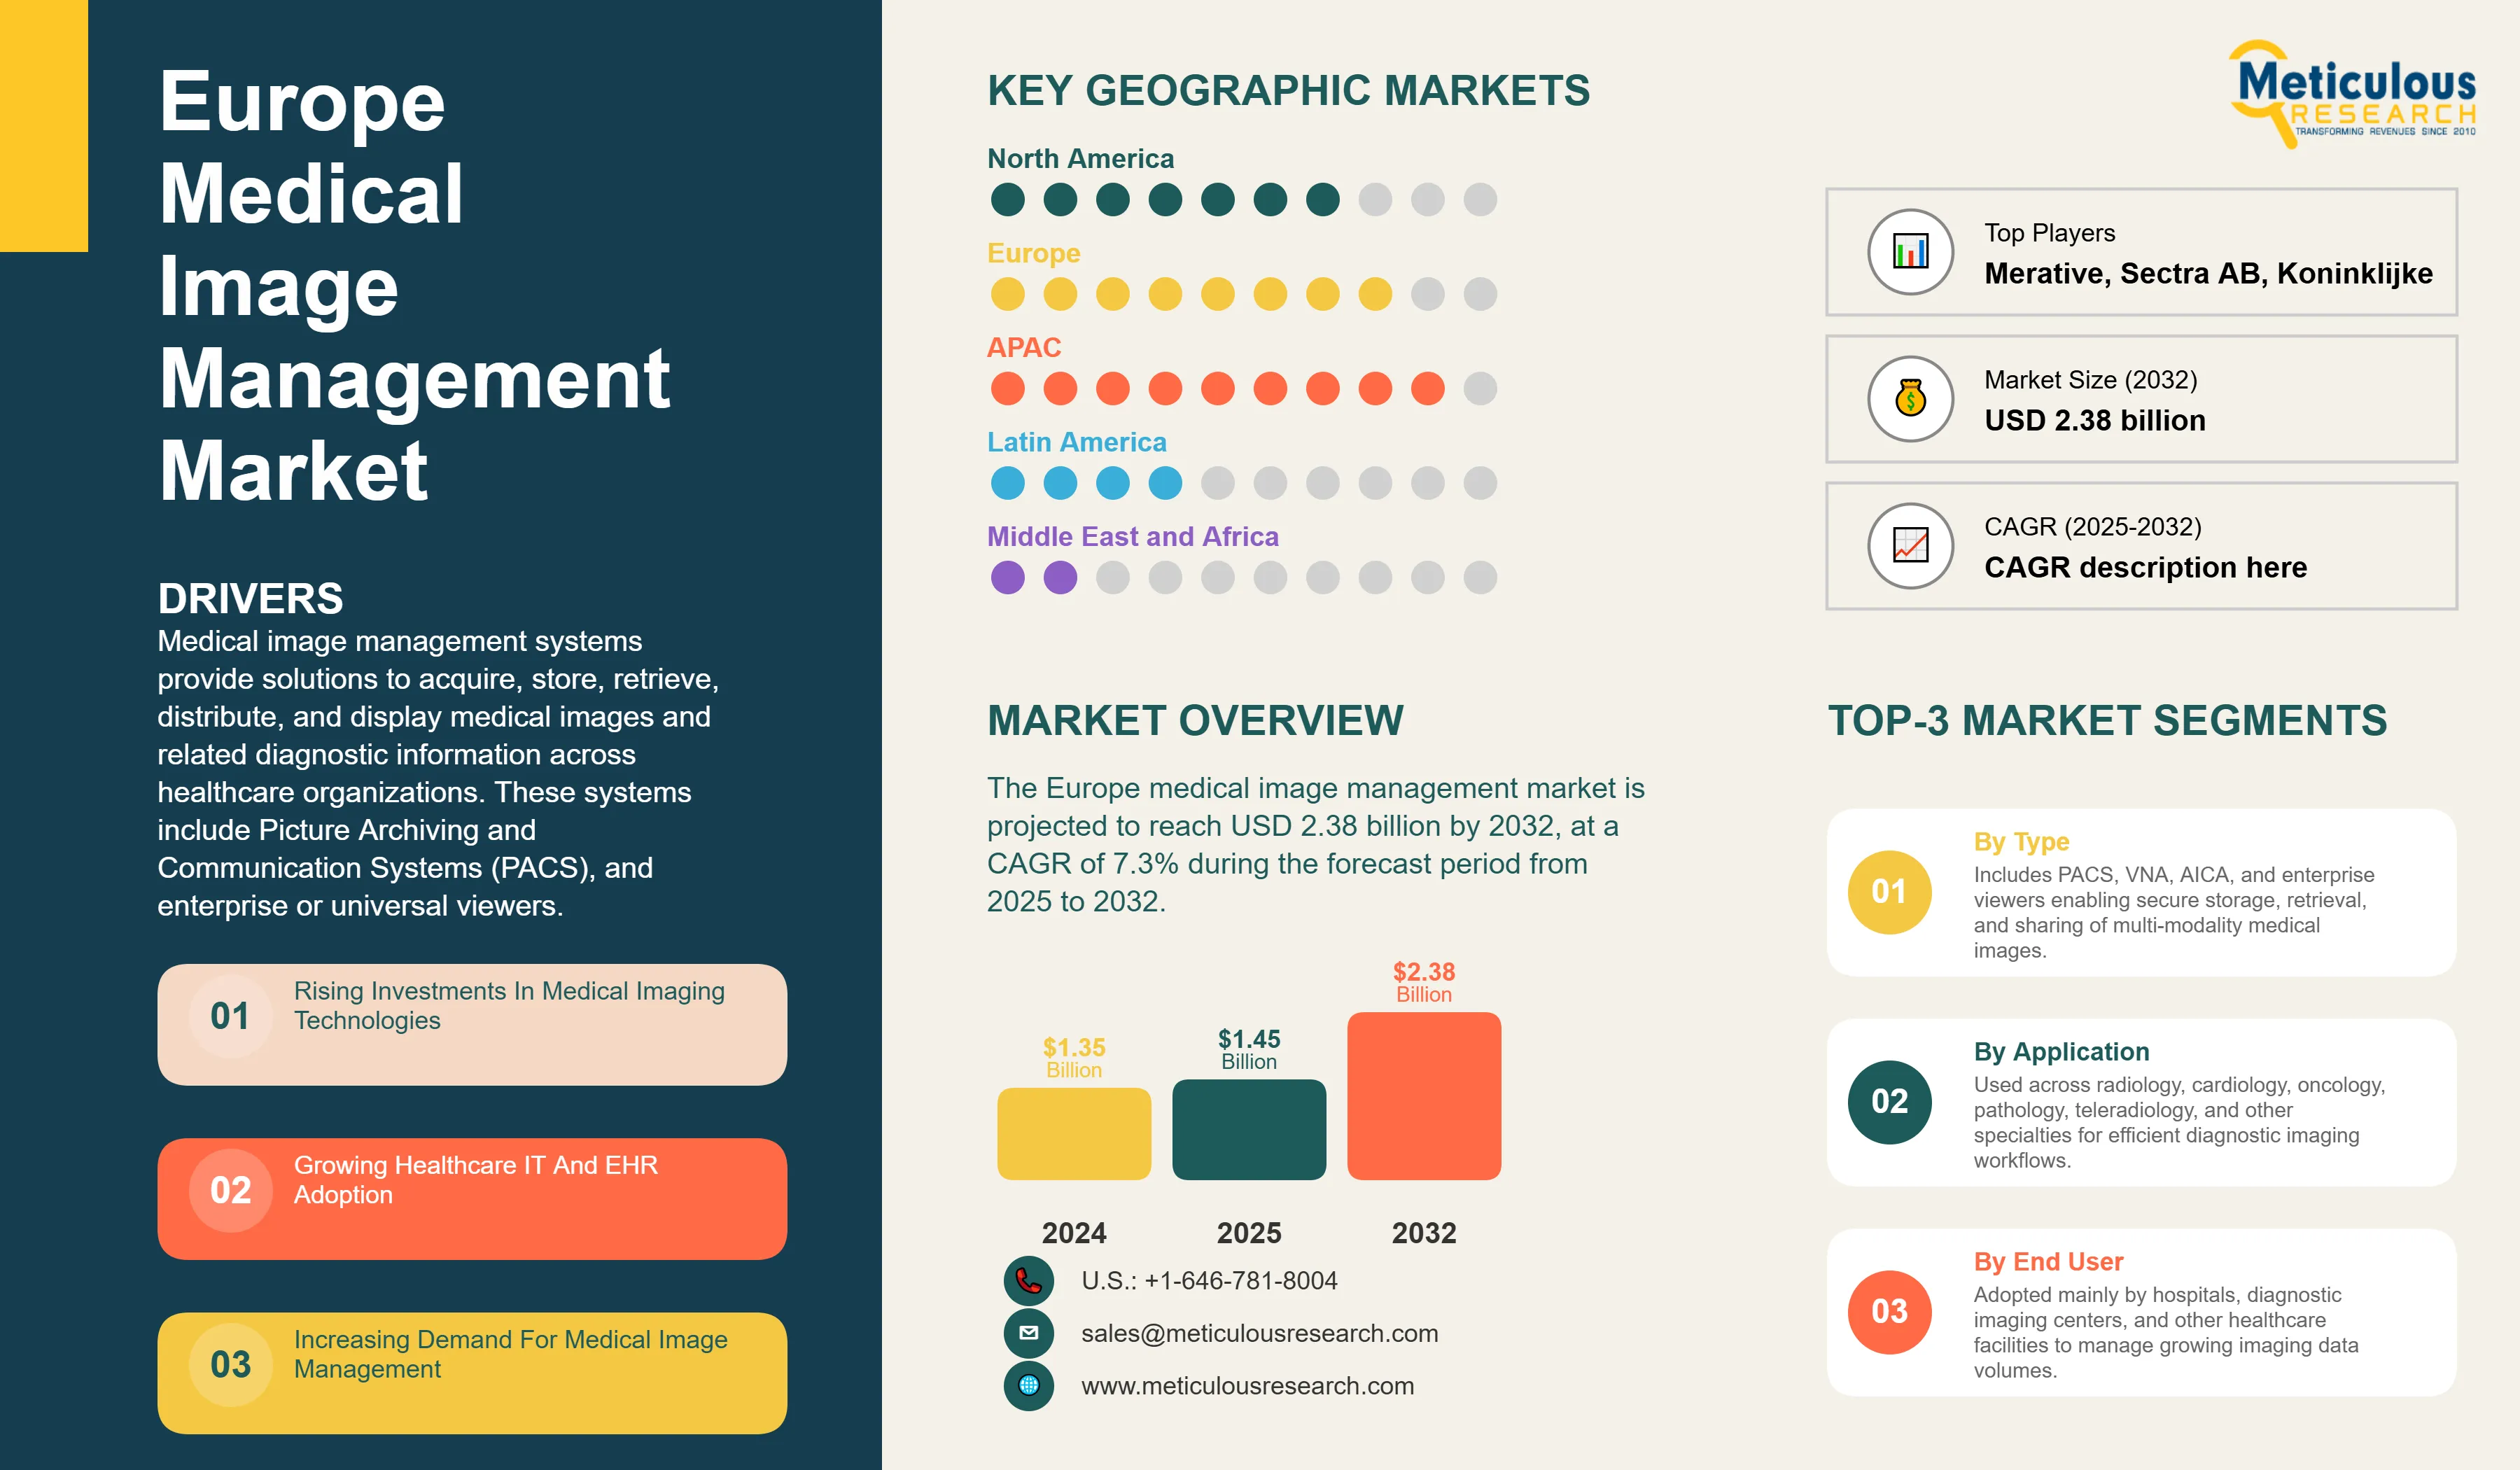
Europe Medical Image Management Market Size & Forecast The Europe medical image management market is projected to reach USD 2.38 billion by 2032 from an estimated USD 1.45 billion in 2025, at a CAGR of 7.3% during the forecast period from 2025 to 2032. Medical image management systems provide solutions
- Published
- Jan 2026
- Pages
- 265
- Format
- PDF + Excel
- Report ID
- MRHC - 104979
- Base year
- 2024
- 2025 · ESTIMATED
- $1.45B
- 2032
- $2.38B
- CAGR 2025–2032
- 7.3%
2024 baseline · 2025–2032 forecast at 7.3% CAGR · hover a bar for the value
Key highlights
By Product: The Picture Archive Communication System (PACS) Segment to Dominate the Europe Medical Image Management Market in 2025
By End User: The Hospitals Segment to Dominate the Europe Medical Image Management Market in 2025
By Geography: Germany Dominates the Europe Medical Image Management Market in 2025
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 245 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 7.3% |
| Market Size (Value) in 2025 | USD 1.45 Billion |
| Market Size (Value) in 2032 | USD 2.38 Billion |
| Segments Covered | By Product · Picture Archive Communication System (PACS) · Departmental PACS · Radiology PACS · Cardiology PACS · Pathology PACS · Other Departmental PACS · Enterprise PACS · Vendor Neutral Archive (VNA) · Application-Independent Clinical Archive (AICA) · Enterprise/Universal Viewer · By End User · Hospitals · Public Hospitals · Private Hospitals · Diagnostic Imaging Centres · Other End Users |
| Countries Covered | Germany, France, U.K., Italy, Spain, Russia, Switzerland, Netherlands, Belgium, Turkey, and Rest of Europe |
| Key Companies | Koninklijke Philips N.V. (Netherlands), Siemens Healthineers AG (Germany), GE Healthcare Technologies, Inc. (U.S.), FUJIFILM Holdings Corporation (Japan), Agfa-Gevaert NV (Belgium), Sectra AB (Sweden), Hyland Software, Inc. (U.S.), INFINITT Healthcare Co., Ltd. (South Korea), Mach7 Technologies (Australia), Novarad Corporation (U.S.), BridgeHead Software Ltd. (U.K.), Change Healthcare Inc. (U.S.), and Merative (U.S.) |
Report infographic
Market dynamics
6 factors across 2 forcesRising Investments in Medical Imaging Technologies
Medical imaging technologies are attracting significant investments across Europe, supporting improved image management solutions like PACS and VNA. European digital health startups raised about $4.8 billion in 2024, marking the fastest global year-over-year growth at 27%, with momentum continuing into the first half of 2025, which totaled €5.2 billion. Major 2024 deals highlighted investor confidence: Flo Health ($200 million), Caresyntax ($180 million), Alan ($193 million), and Ōura ($200 million).
Government programs are enhancing imaging infrastructure. The EU4Health initiative, with €5.3 billion allocated for 2021-2027, designated €752.4 million in 2024 for digital health priorities, including grants for eHealth. France took the lead with €1.7 billion for digital health startups in 2022, nearly tripling the amount from 2021, while the UK's £700 million ($923 million) Digital Diagnostic Solutions project, announced in September 2024, targets AI-driven imaging as one of the largest healthcare IT investments worldwide. Germany's Hospital Future Act continues to fund PACS/VNA rollouts across hospitals.
Noteworthy private sector initiatives include GE Healthcare’s opening of a cutting-edge R&D center in Lyon, France, in June 2024, focusing on next-generation MRI sequences and AI image reconstruction. These investments represent 15-20% of digital health funding and are expected to speed up the adoption of medical image management solutions throughout the forecast period.
The European Commission has committed over €16 billion from 2014 to 2027 through programs, including the Cohesion Policy and the Recovery and Resilience Facility, to support healthcare digitalization. Most EU member states reported that these funds fit well with their healthcare digitalization needs, boosting investments in electronic health records, ePrescriptions, and remote healthcare services, which drive demand for integrated medical image management infrastructure.
Growing Healthcare IT and Electronic Health Record (EHR) Adoption
The healthcare IT industry in Europe has seen substantial growth, attracting significant private and public investments. The European Health Data Space (EHDS), approved in January 2025, is a major initiative aimed at improving individuals' access to and control over their electronic health data, while also allowing data reuse for research and innovation. The EHDS requires member states to adopt a shared EHR exchange format using Fast Healthcare Interoperability Resources (FHIR) standards. This will facilitate seamless integration of medical imaging data with patient records across borders.
National digital health initiatives are continually promoting EHR adoption. France’s Ma Santé 2022 program concentrates on patient-centered care, provider collaboration, and digital development, with a total budget of €3.24 billion, of which €500 million is dedicated to digital transformation. Italy’s Strategy for Digital Growth and Triennial Plan for Public Administration Informatics encourages EMR and telemedicine adoption across regions. Germany leads in the European departmental PACS market, showing widespread integration of imaging informatics with health information systems.
Limited access to imaging data in EMRs often results in repeated diagnostic imaging, exposing patients to unnecessary radiation and raising healthcare costs. PACS and VNA solutions that connect with EHRs are increasingly sought after to enhance clinical workflows and treatment decisions. This integration allows radiologists and clinicians to review complete patient histories alongside imaging studies, leading to more accurate diagnoses and fewer redundant procedures. The merging of EHR and imaging informatics signifies a crucial shift in European healthcare delivery, driving ongoing demand for interoperable medical image management solutions.
Increasing Demand for Medical Image Management Solutions
The demand for medical image management solutions in Europe is growing due to an aging population, an increase in chronic diseases, and rising imaging volumes. According to Eurostat, approximately 21.6% of the EU population was 65 or older as of 2024, and this percentage continues to rise with longer life expectancy. The elderly are particularly susceptible to chronic diseases: 80% of those aged 65 and over have at least one chronic condition, and about 36% have two or more, according to EFPIA data.
Imaging volumes across Europe are increasing significantly. The UK National Health Service reported roughly 43.4 million medical imaging tests conducted in England from February 2022 to January 2023. The growth of advanced imaging technologies has greatly raised storage capacity needs. Technologies such as digital breast tomosynthesis (3D mammography), photon-counting CT, and high-resolution MRI create large, complex datasets, increasing the need for efficient storage and management solutions.
The Netherlands shows intensive imaging use, performing about 58 MRI scans and 134 CT scans per 1,000 residents annually, among the highest rates in the EU. This rise in imaging volumes highlights the need for strong image management infrastructure. In 2023, Eurostat reported approximately 2.3 million hospital beds available across the EU, with an average of 511 hospital beds for every 100,000 inhabitants. This extensive hospital infrastructure generates substantial demand for medical image management solutions. Nearly all large hospitals in Western Europe now operate fully functional PACS systems, showing a mature market with ongoing requirements for upgrades, replacements, and integration with new imaging technologies.
Technical Advancements in Diagnostic Imaging Modalities
Technological advancements in diagnostic imaging are transforming patient care and increasing demand for sophisticated image management solutions. In January 2024, Siemens Healthineers launched an AI-powered radiology platform at the European Congress of Radiology in Vienna, intended to speed up image analysis and enable earlier disease detection. In March 2024, Canon Medical Systems teamed up with a Dutch AI startup to incorporate deep learning algorithms into CT and MRI scanners, enhancing tumor segmentation and reducing false positives.
Key innovations reshaping the European market include digital breast tomosynthesis (DBT), now widely considered standard in breast imaging due to better lesion visibility and early cancer detection. Photon-counting CT technology is becoming more popular in European facilities, offering lower radiation doses and improved contrast resolution. In late 2024, Philips introduced the BlueSeal MR Mobile, the first 1.5T fully sealed helium-free magnet mobile unit in the industry, addressing sustainability and resource constraints.
The integration of AI into imaging technologies continues to accelerate. By mid-2025, about 873 AI/ML radiology devices had received FDA clearance, with radiology accounting for 78% of all new AI medical device approvals. Leading vendors—GE Healthcare (96 cleared tools), Siemens Healthineers (80), Philips (42), Canon (35), and United Imaging (32)—are incorporating AI capabilities into imaging systems. In September 2024, Philips launched an updated integrated diagnostics suite featuring cloud-based PACS integration and AI triage tools for stroke detection, designed for NHS hospitals. These advancements create increasingly large and complex datasets, driving demand for enterprise-grade PACS and VNA solutions that can handle multi-modality image repositories.
Table of contents
10 chapters · 334 sections · 265 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Product | Picture Archive Communication System (PACS) | — |
| By End User | Hospitals | Hospitals |
By Product
- The Picture Archive Communication System (PACS) Segment Dominated the Europe Medical Image Management Market in 2025
- The PACS segment had the largest share of the medical image management market in Europe.
- This strong market share comes from the growing use of PACS in radiology departments, where most imaging studies are handled, managed, and stored.
- There is also an increasing adoption of PACS in other fields like cardiology, ophthalmology, oncology, endoscopy, teleradiology, dermatology, pathology, neurology, and dentistry.
- Recent assessments show that nine out of ten hospitals in Western Europe now operate fully functional PACS to manage and share medical images.
- This shows the maturity and broad acceptance of this technology.
- The PACS segment is also divided into departmental PACS and enterprise PACS.
- Departmental PACS holds the larger share, with radiology PACS being the largest subsegment due to radiology’s central role in diagnostic imaging workflows.
- On the other hand, the vendor neutral archive (VNA) solutions segment is growing quickly.
- European healthcare providers are increasingly focusing on enterprise imaging, working together, and long-term data management.
- VNAs allow centralized storage of medical images and non-DICOM content across departments, vendors, and care settings.
- They tackle long-standing issues related to data silos and vendor lock-in.
- The rising emphasis on cross-border healthcare, regional health information exchanges, and initiatives like the European Health Data Space (EHDS) is boosting the need for vendor-agnostic, standards-based image repositories.
By End User
- The Hospitals Segment Dominated the Europe Medical Image Management Market in 2025
- The hospitals segment held the largest share of the medical image management market in Europe.
- This significant market share is due to the increasing number of hospital admissions, the growing number of hospitals in European countries, the use of VNAs in hospitals to address issues with PACS growth and data compatibility, and the rising demand for enterprise-wide image data management in hospitals.
- According to Eurostat 2023, there were about 2.3 million hospital beds available in the EU, averaging 511 beds per 100,000 inhabitants.
- This widespread hospital infrastructure creates a substantial demand for medical image management solutions.
- The hospitals segment is further divided into public hospitals and private hospitals.
- Public hospitals account for the larger share, forming the backbone of healthcare across Europe, where most countries operate under universal healthcare systems.
- The UK's National Health Service (NHS), Germany's dual public-private system, and France's strong public healthcare tradition are significant users of medical image management solutions.
- The NHS Long Term Plan focuses on developing diagnostic imaging networks for quicker transfer of clinical images.
- Meanwhile, Germany's Hospital Future Act has allocated over €4.3 billion to modernize hospital IT infrastructure, including upgrades to imaging systems.
- Additionally, the hospitals segment is expected to have the highest growth rate during the forecast period, driven by ongoing digital transformation, PACS replacement cycles, and the integration of AI-powered imaging solutions.
Geographic analysis
Europe
Largest shareThe Europe medical image management market is projected to reach USD 2.38 billion by 2032 from an estimated USD 1.45 billion in 2025, at a CAGR of 7.3% during the forecast period from 2025 to 2032. Medical image management systems provide solutions to acquire, store, retrieve, distribute, and display medical images and related diagnostic information across healthcare organizations. These systems include Picture Archiving and Communication Systems (PACS), Vendor Neutral Archives (VNA), Application-Independent Clinical Archives (AICA), and enterprise or universal viewers. They help healthcare providers manage imaging data from various modalities, including X-ray, computed tomography (CT), magnetic resonance imaging (MRI), ultrasound, mammography, and nuclear medicine. Key factors driving this market include increasing investments in medical imaging technology, the growing use of healthcare IT and electronic health records (EHR), rising demand for medical image management solutions due to aging populations and more chronic diseases, and advancements in diagnostic imaging technology. The European digital health sector is growing quickly, with startups raising about €4.3 billion (around $4.8 billion) in 2024, showing a 27% increase from the previous year. Between 2021 and 2027, the European Commission has allocated over €14 billion to digital health projects through significant programs like Horizon Europe, EU4Health (with a €5.3 billion budget), and the Digital Europe Programme (€7.6 billion). This funding will boost the deployment of improved medical imaging and data management solutions. Medical image management solutions are now vital in modern healthcare, replacing film-based processes, lowering storage costs, enhancing workflow efficiency, and allowing smooth integration with electronic health records (EHR) and hospital information systems (HIS). This supports patient-centered care and clinical decisions in radiology, cardiology, pathology, and other imaging-focused specialties. Recent assessments show that nine out of ten hospitals in Western Europe have fully operational PACS to manage and exchange medical images, indicating the maturity and wide acceptance of this technology. With the rise of artificial intelligence (AI) in medical imaging, growth in the telehealth market in European countries, and rapidly increasing big data in healthcare, the European medical image management market is expected to grow significantly. A 2024 survey by the European Society of Radiology found that 48% of radiologists in Europe are using AI tools (up from 20% in 2018), with an additional 25% planning to implement AI. This trend is driving demand for advanced image management systems that can support AI-integrated workflows and enterprise-wide imaging strategies. In 2025, Germany held the largest share of this market in Europe. Germany leads the region due to its well-developed healthcare system, large number of hospitals, and high intensity of diagnostic imaging. The country has one of the highest rates of hospital beds, radiology departments, and imaging procedures per person in Europe. This directly increases the need for PACS, VNA, and enterprise imaging solutions. Germany is also an early adopter of digital health technologies, thanks to supportive reimbursement systems, strong investments in public and private hospitals, and the presence of major global and regional imaging IT vendors. The ongoing modernization of hospital IT systems, the replacement of PACS, and the growing use of enterprise imaging across hospital networks further strengthen Germany's leading role. Meanwhile, Turkey is becoming the fastest-growing market in Europe due to swift healthcare infrastructure growth and advancing digitization efforts. Over the last decade, Turkey has invested significantly in large public hospital projects, including city hospitals that feature modern diagnostic and imaging capabilities. Increased healthcare spending, rising patient numbers, and government initiatives to update hospital information systems are promoting first-time use of medical image management solutions. Additionally, the expanding private healthcare sector, medical tourism, and a rising number of cloud-based and cost-effective imaging IT platforms are driving Turkey's higher growth rate compared to more established Western European markets. Europe Medical Image Management Market Size & Forecast Germany Dominated the Europe Medical Image Management Market in 2025
Competitive landscape
- Koninklijke Philips N.V. · Netherlands
- Siemens Healthineers AG · Germany
- GE Healthcare Technologies, Inc. (U.S.)
- FUJIFILM Holdings Corporation · Japan
- Agfa-Gevaert NV · Belgium
- Sectra AB · Sweden
- Hyland Software, Inc. (U.S.)
- INFINITT Healthcare Co., Ltd. · South Korea
- Mach7 Technologies · Australia
- Novarad Corporation (U.S.)
- BridgeHead Software Ltd. (U.K.)
- Change Healthcare Inc. (U.S.)
- Merative (U.S.)
Frequently asked questions
The Europe medical image management market size is projected to reach USD 1.45 billion in 2025.
Cite this report
Meticulous Research. (2026). Europe Medical Image Management Market - Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRHC - 104979). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/europe-medical-image-management-market-5662