Digital Vaults Market (2024-2031)
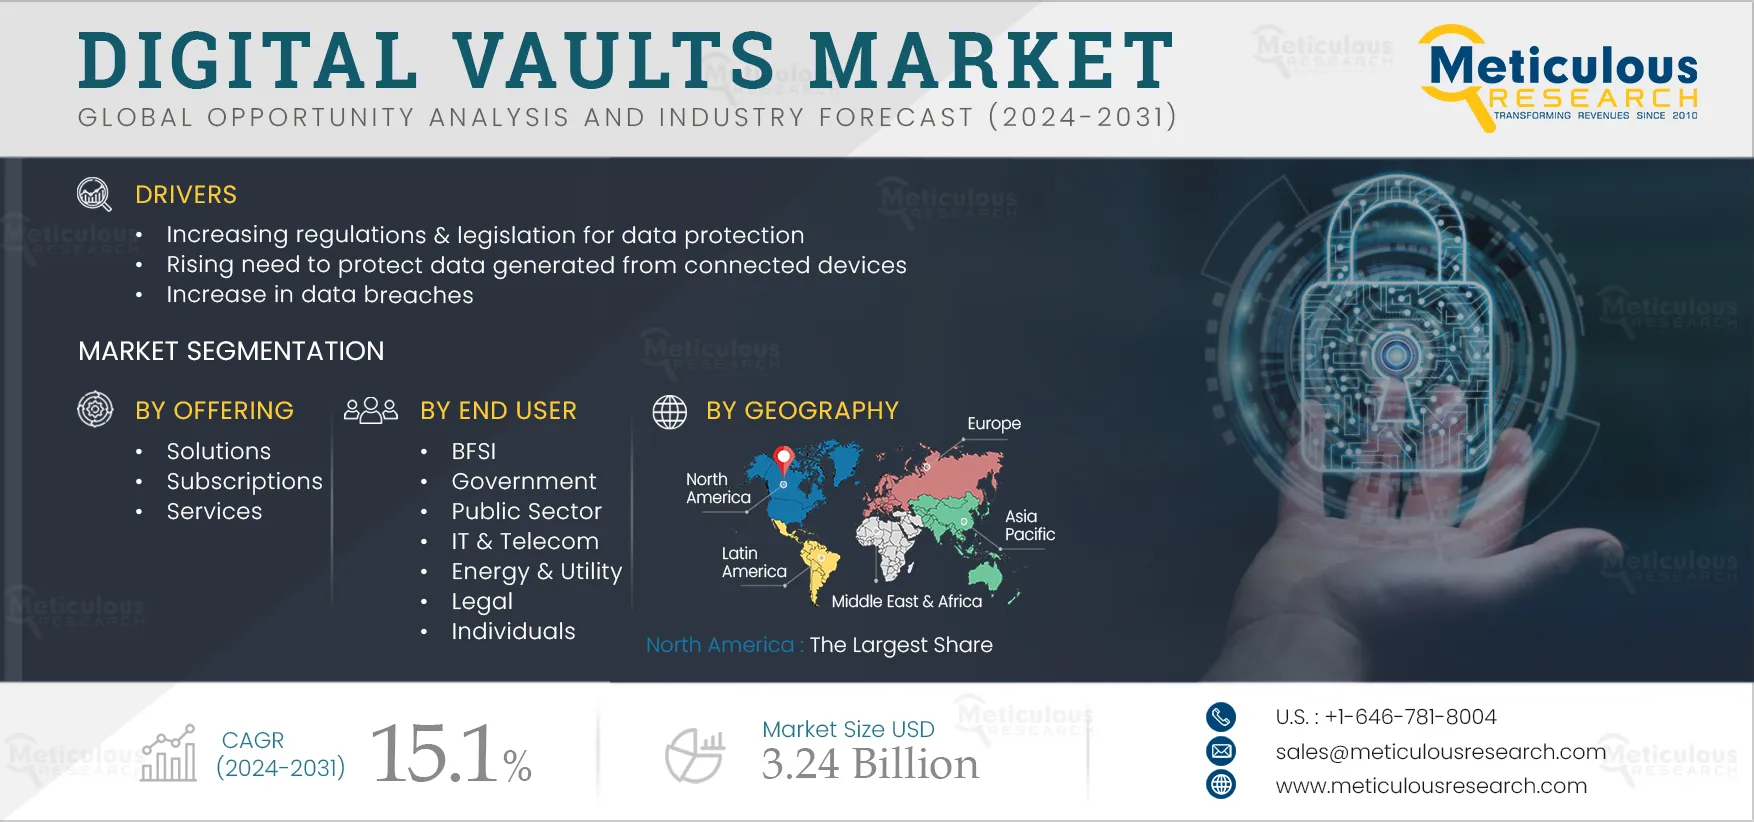
The Digital Vaults Market is expected to reach $3.24 billion by 2031, at a CAGR of 15.1% from 2024 to 2031.The growth of the digital vaults market is driven by the increasing regulations & legislation for data protection, the rising need to protect data generated from connected devices, and the increase in data breaches.
- Published
- Jul 2024
- Pages
- 170
- Format
- PDF + Excel
- Report ID
- MRICT - 104936
- Base year
- 2023
- 2031 · FORECAST
- $3.24B
- 2031
- $3.24B
- CAGR 2024–2031
- 15.1%
2023 baseline · 2024–2031 forecast at 15.1% CAGR · hover a bar for the value
Key highlights
By Offering: In 2024, the Solutions Segment to Dominate the Digital Vaults Market
By Deployment Mode: In 2024, the Cloud-based Deployments Segment to Dominate the Digital Vaults Market
By End User: In 2024, the IT & Telecom Segment to Dominate the Digital Vaults Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 170 |
| Format | |
| Forecast Period | 2024–2031 |
| Base Year | 2023 |
| CAGR (Value) | 15.1% |
| Market Size (Value) | USD 3.24 Billion by 2031 |
| Segments Covered | By Offering · Solutions · Identity and Access Management · Data Loss Prevention · Digital Asset Management · Privileged Account Management · Subscriptions · Services · Support & Maintenance Services · Deployment & Integration Services · Consulting Services · By Deployment Mode · Cloud-based Deployments · On-premise Deployments · By End User · BFSI · Government · Public Sector · IT & Telecom · Aerospace & Defense · Energy & Utility · Healthcare & Pharmaceuticals · Legal · Individuals · Other End Users |
| Countries Covered | Europe (U.K., Germany, France, Italy, Spain, Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Rest of Asia-Pacific), North America (U.S., Canada), Latin America and the Middle East & Africa |
| Key Companies | Microsoft Corporation (U.S.), IBM Corporation (U.S.), Oracle Corporation (U.S.), Fiserv, Inc. (U.S.), Google LLC (U.S.), Veritas Technologies LLC (U.S.), HashiCorp, Inc. (U.S.), Hitachi Vantara LLC (U.S.), Morgan Stanley (U.S.), CyberArk Software Ltd. (U.S.), FutureVault Inc. (U.S.), Johnson Controls International plc (Ireland), OPSWAT, Inc. (U.S.), Zoho Corporation Pvt. Ltd. (U.S.), Keeper Security, Inc. (U.S.), Safe4 Information Management Limited (U.K.), Virtual StrongBox, Inc. (U.S.), Hypervault (Belgium), ENC Security (U.S.), and Clocr Inc (U.S.) |
Report overview
Segments covered: offering, deployment, end user. Regions: Europe, Asia-Pacific, North America.
However, enterprises’ lack of awareness about data security restrains the growth of this market.
Moreover, the growing digitalization of businesses and the increasing use of digital vaults in the BFSI sector are expected to generate growth opportunities for the stakeholders in this market. However, the lack of digitalization in developing countries, the high costs of digital vaults, and the availability of alternative cybersecurity solutions are major challenges for market growth. Additionally, the growing adoption of cloud-based security solutions is a prominent trend in the digital vaults market.
Report infographic
Market dynamics
4 factors across 3 forcesData Protection Regulations Boosting the Adoption of Digital Vaults
Governments and organizations are gradually recognizing the significance of data privacy & security as social and commercial interactions are increasingly moving to online environments. The unethical practice of collecting, utilizing, and disclosing customers’ personal data to third parties without their knowledge or consent has raised data security & privacy concerns, driving the establishment of various regulations and legislation for data protection. According to the United Nations Conference on Trade and Development, out of 194 countries, 71% (137) have established data protection legislation, while 9% have draft legislation, 15% have no legislation, and 5% even lack the data to support data protection & privacy legislation. These numbers indicate countries’ high focus on implementing data privacy & security regulations.
Businesses are partnering with digital vault solution providers to secure customer data; for instance, in April 2021, Bailard, Inc. (U.S.), an independent wealth and investment management firm, partnered with FutureVault Inc. (U.S.), an industry leader in enterprise digital vault solutions, to deploy Bailard Vault. The solution provides crucial information faster and in a secure environment.
Governments’ increased focus on data protection drives the adoption of data protection & privacy solutions such as digital vaults. Organizations that do not comply with these regulations face penalties. Hence, enterprises are increasingly adopting data privacy & security solutions such as digital vaults to avoid heavy fines.
Increase In Data Breaches is Driving the Demand for Digital Vaults Market
Data breaches are becoming increasingly frequent and sophisticated. In 2022, over 392 million individuals worldwide were affected by 1,774 organizational data breaches. These data breaches compromised the information of individuals accessing financial, healthcare, and social services.
In 2020, the economic cost of information & technology asset security breaches accounted for 4-6% of the world’s GDP. In 2022, organizations had to incur USD 4.35 million in data breach costs on average globally. Also, the average cost of a data breach in the U.S. was USD 9.44 million, more than twice the global average. Approximately 82% of breaches were targeted at data stored on clouds. Organizations are seeking solutions that can provide visibility across hybrid environments and protect their data as it moves across clouds, databases, apps, and services. Thus, increasing data breaches are boosting the demand for digital vault solutions, driving the growth of this market.
Table of contents
11 chapters · 110 sections · 170 pages · click to expandSegmental analysis
| Segment | Largest share (2024) | Fastest growth (2024–2031) |
|---|---|---|
| By Offering | Solutions | Solutions |
| By Deployment Mode | Cloud-based Deployments | Cloud-based deployments |
| By End User | Large market share of this | BFSI |
By Offering
- The Solutions Segment to Dominate the Digital Vaults Market
- The solutions segment is expected to account for the largest share of above 52.0% of the digital vaults market.
- The large market share of this segment is attributed to the ability of solutions to safely store and organize documents containing sensitive client and company information; benefits to individuals and organizations such as access management; ensuring compliances; and growing security spending of organizations to store confidential data securely.
- Moreover, the solutions segment is also expected to record the highest CAGR during the forecast period.
- The growth of this segment is driven by the rising focus of key players on product development and the growing security concern of organizations to store data.
- For instance, in January 2021, Digital Vault Services GmbH (Germany), a SaaS company, launched its solution for digital guarantees, Guarantee Vault.
- Guarantee Vault is a central register for issuing and safeguarding digital guarantees.
By Deployment Mode
- The cloud-based deployments segment is expected to account for the larger share of above 80.0% of the digital vaults market.
- The large market share of this segment is attributed to the increasing avenues for cloud-based deployments, the superior flexibility and affordability offered by cloud-based deployments, and the increasing adoption of cloud-based solutions by small & medium-sized enterprises.
- Moreover, the cloud-based deployments segment is also expected to record the highest CAGR during the forecast period.
- The rapid evolution of new security avenues for cloud-based deployments is expected to drive the growth of the cloud-based deployments segment in the coming years.
- For instance, in October 2022, the Dubai International Financial Centre (DIFC) Courts (UAE) launched a global digital vault, ‘tejouri’.
- Tejouri provides a unique platform that functions simultaneously as a cloud vault and an online safe for data.
By End User
- The IT & Telecom Segment to Dominate the Digital Vaults Market
- The IT & telecom segment is expected to account for the largest share of above 25.0% of the digital vaults market.
- The large market share of this segment is attributed to the rapid adoption of digital technologies, the rise in data breaches and cyber-attacks, and the strong focus of stakeholders to deploy digital vault services.
- Stakeholders are focusing on data security in the IT & Telecom sector to provide seamless customer services.
- For instance, in April 2023, the Telecommunications and Digital Government Regulatory Authority (TDRA) introduced the Digital Vault Project for the banking, insurance, and telecommunication sectors.
- However, the BFSI segment is expected to record the highest CAGR during the forecast period.
- The growth of this segment is driven by factors such as the rising focus of key players on product development, growing security concerns in financial organizations, and rising digitization in the financial sector.
- For instance, in April 2021, Skyflow Inc. (U.S.), a vault provider, launched Payments Data Privacy Vault, the zero-trust data vault in the industry for handling sensitive payments and personal information securely.
Geographic analysis
North America
Largest shareIn 2024, North America is expected to account for the largest share of 30.0% of the digital vaults market. The large market share of this segment is attributed to organizations' strong focus on cybersecurity, the presence of big tech companies, their strong emphasis on safeguarding valuable data, and increased data breach attacks. The top tech companies provide digital vault solutions to various industries to store valuable information securely. The presence of leading key players in the region contributes to a large market share. In 2024, North America Region to Dominate the Digital Vaults Market
Asia-Pacific
Fastest growthHowever, the Asia-Pacific is expected to record the highest CAGR of 15.8% during the forecast period. Ongoing digital transformation in the banking and financial sector, increasing fintech businesses, and increased cyberattacks in the Asia-Pacific region are factors expected to drive the growth of the digital vaults market in the coming years. Countries in the Asia-Pacific region are working to strengthen their cybersecurity capabilities through increased investment, education, and international cooperation, contributing to market growth.
Competitive landscape
- June 2023
Google LLC (U.S.) added new capabilities to Vault solutions. These features support custom and default file-level retention rules based on Google Drive labels.
- March 2023
IBM Corporation (U.S.) collaborated with Cohesity, Inc. (U.S.), a leading data security & data management platform provider, on IBM Storage Defender, a solution that increases data security and resiliency in hybrid cloud environments. IBM Storage Defender features a cyber vault and clean room features with automated recovery functions to restore business-critical data in hours or minutes from what used to take days.
- July 2022
Veritas Technologies LLC (U.S.) collaborated with Relativity (U.S.), a global legal and compliance technology company, to collaborate on two key innovative solutions. The first is an integration of Relativity's AI-powered communication surveillance platform. The second is more interconnectivity between RelativityOne and Relativity Server and Veritas archiving and e-discovery solutions, Enterprise Vault, eDiscovery Platform, Veritas Advanced Discovery, and Discovery Accelerator.
- Microsoft Corporation (U.S.)
- IBM Corporation (U.S.)
- Oracle Corporation (U.S.)
- Fiserv, Inc. (U.S.)
- Google LLC (U.S.)
- Veritas Technologies LLC (U.S.)
- HashiCorp, Inc. (U.S.)
- Hitachi Vantara LLC (U.S.)
- Morgan Stanley (U.S.)
- CyberArk Software Ltd. (U.S.)
- FutureVault Inc. (U.S.)
- Johnson Controls International plc · Ireland
- OPSWAT, Inc. (U.S.)
- Zoho Corporation Pvt. Ltd. (U.S.)
- Keeper Security, Inc. (U.S.)
- Safe4 Information Management Limited (U.K.)
- Virtual StrongBox, Inc. (U.S.)
- Hypervault · Belgium
- ENC Security (U.S.)
- Clocr Inc (U.S.)
Frequently asked questions
The digital vaults market study focuses on market assessment and opportunity analysis through the sales of digital vaults solutions, subscriptions, and services across different regions and countries. This study is also focused on competitive analysis for digital vaults based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies.
Cite this report
Meticulous Research. (2024). Digital Vaults Market - Global Opportunity Analysis and Industry Forecast (2024-2031) (Report No. MRICT - 104936). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/digital-vaults-market-5619