Co-Packaged Optics (CPO) Market (2026-2036)
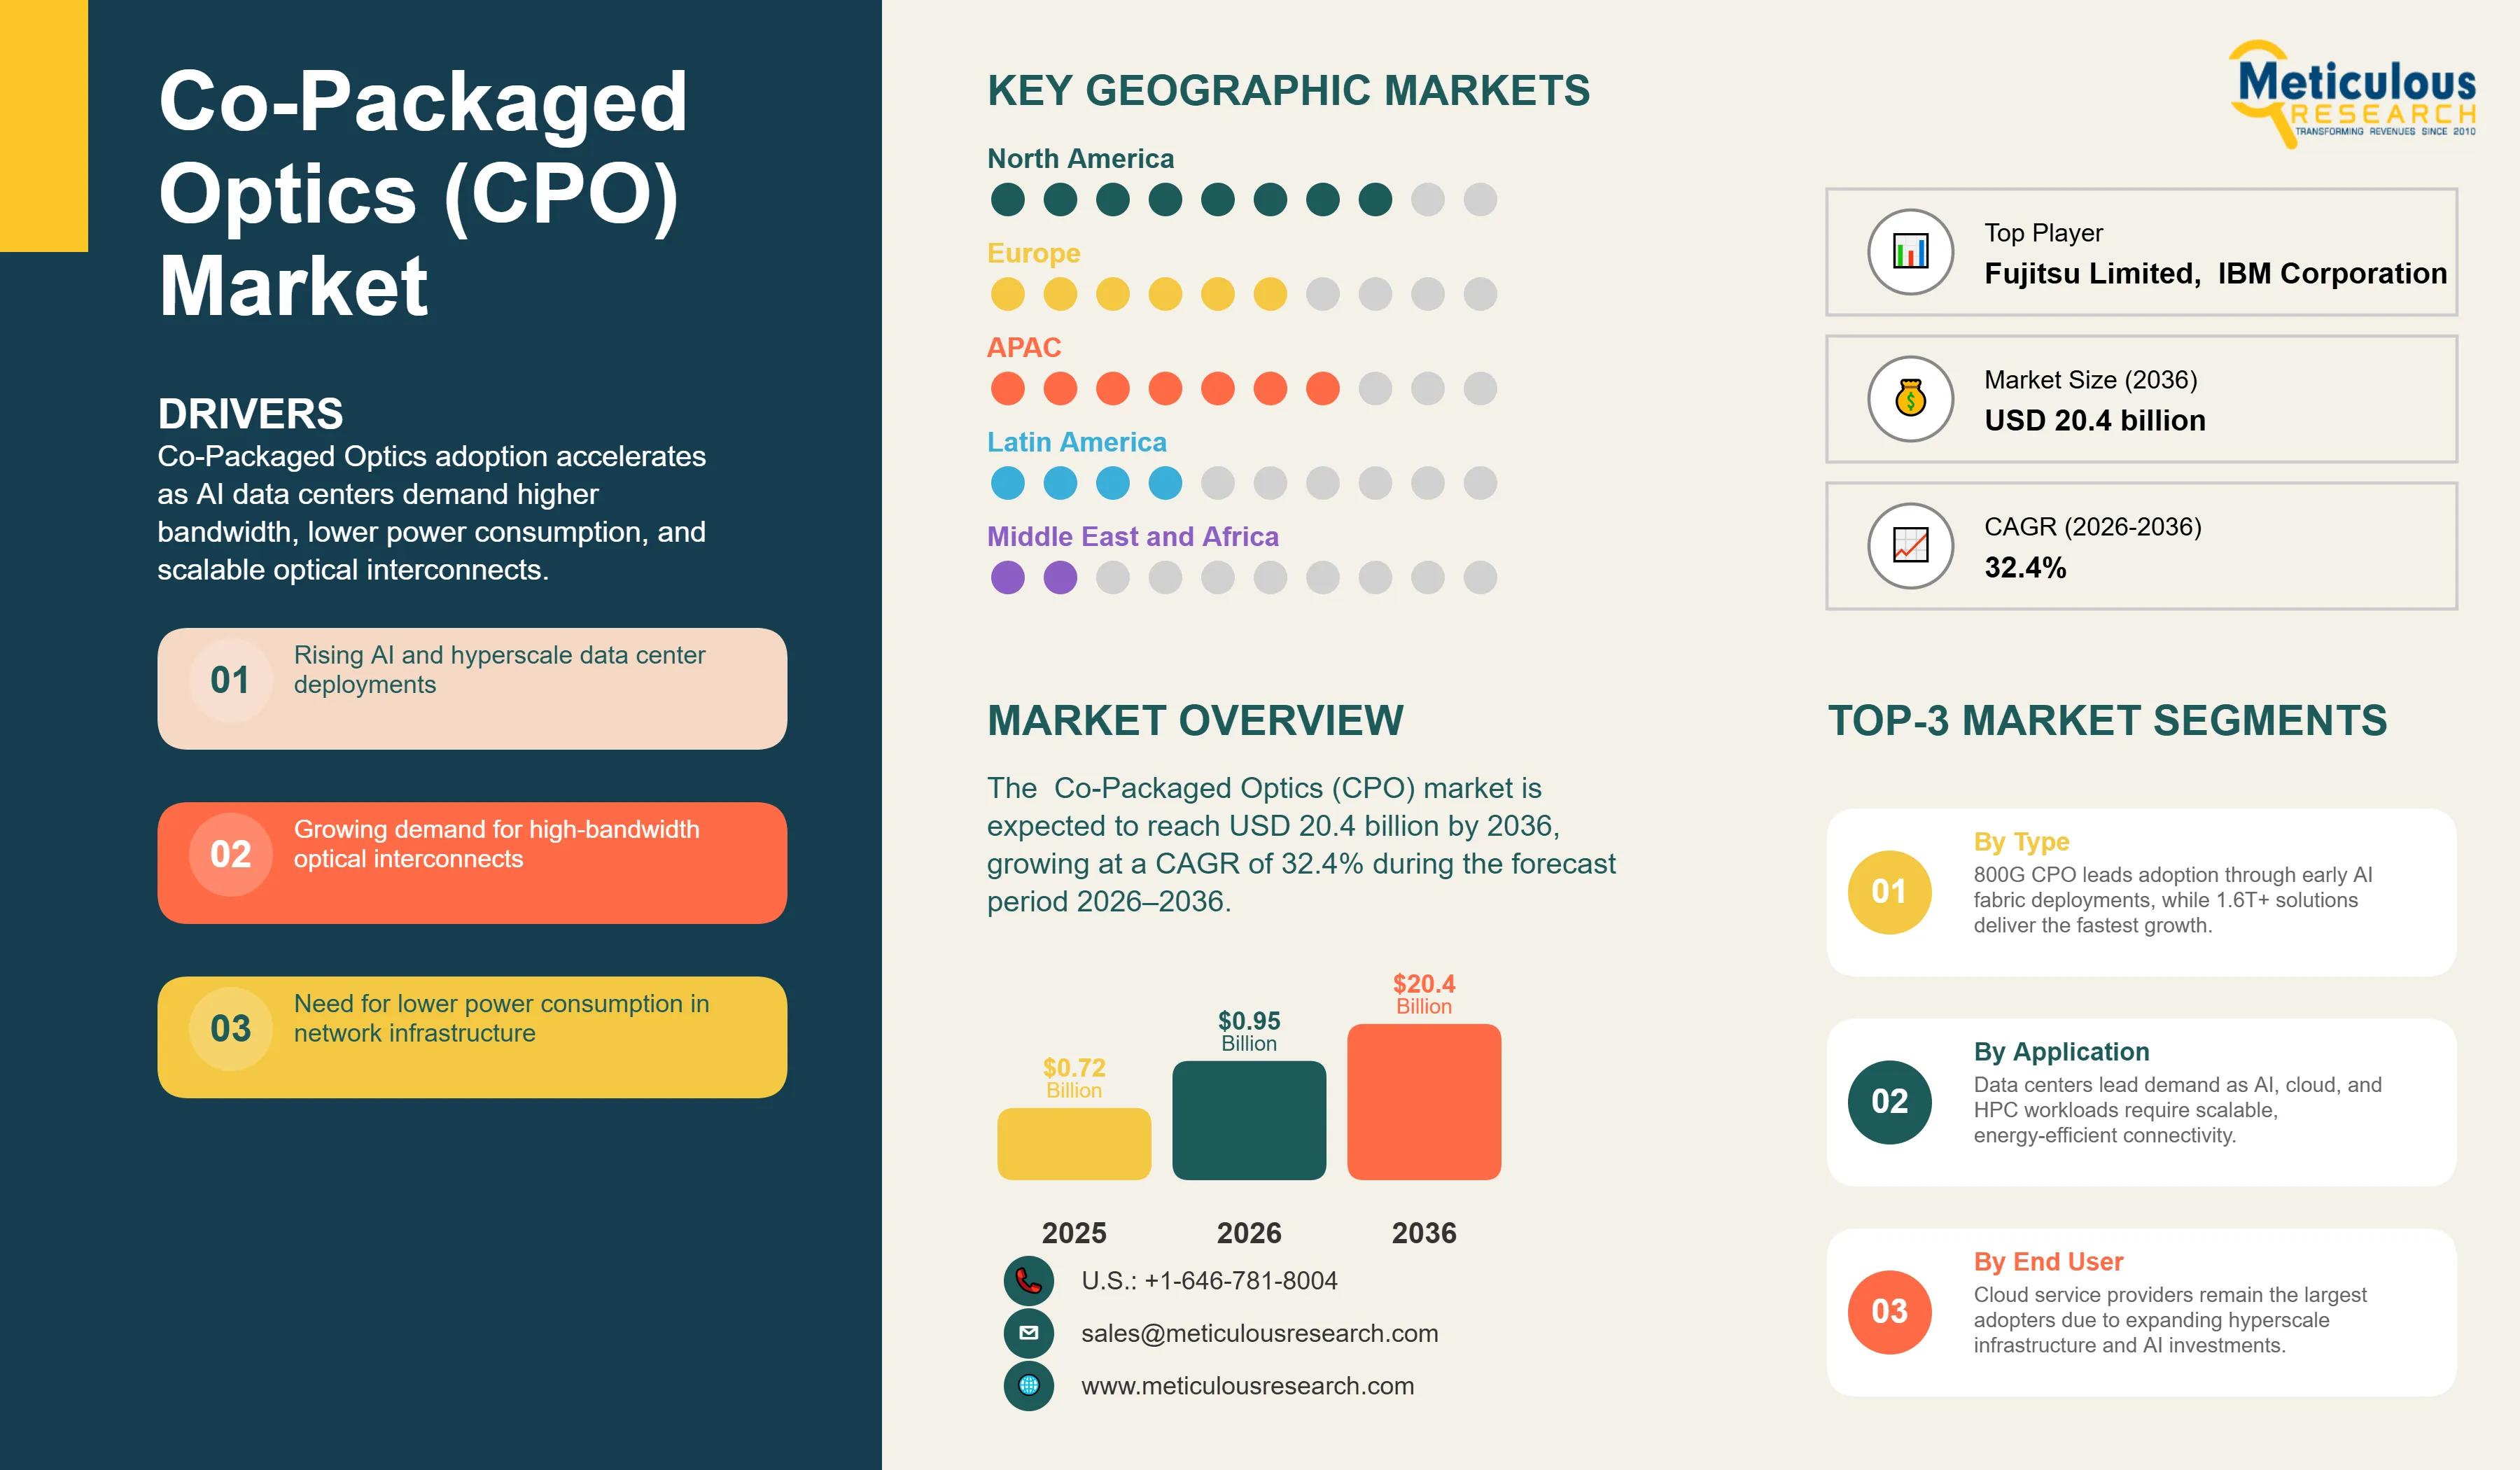
The global Co-Packaged Optics (CPO) market is estimated to be USD 0.95 billion in 2026. This market is expected to reach USD 20.4 billion by 2036, growing at a CAGR of 32.4% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 318
- Format
- PDF + Excel
- Report ID
- MRSE - 1042065
- Base year
- 2025
- 2026 · ESTIMATED
- $950.0M
- 2036
- $20.40B
- CAGR 2026–2036
- 32.4%
2025 baseline · 2026–2036 forecast at 32.4% CAGR · hover a bar for the value
Key highlights
The global CPO market is projected to reach USD 18.40 billion by 2036, growing at a CAGR of 30.8% during the forecast period 2026–2036.
North America is expected to dominate the global market in 2026, driven by the presence of leading hyper-scale data center operators and AI hardware giants.
Asia Pacific is projected to witness significant growth, fueled by its dominance in semiconductor manufacturing and advanced packaging facilities.
By type, the 800G CPO segment is expected to hold the largest share in 2026, driven by early deployments in AI scale-out fabrics, while 1.6T and above CPO is projected for the fastest growth.
By component, the optical engines segment is expected to account for the largest share in 2026, due to their critical role in electro-optical conversion.
By application, the data center segment is expected to account for the largest share in 2026, driven by the exponential growth of AI and HPC workloads.
Key players operating in the global market include Broadcom Inc., Marvell Technology, Inc., Intel Corporation, and Cisco Systems, Inc.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 950.0 million |
| Market Size (2036) | USD 20.40 billion |
| CAGR (2026–2036) | 32.4% |
| Format | PDF, Excel & Cloud Portal · 318 pages |
| Segments Covered | By Type · By Component · By Application · By End User |
| Key Companies | Broadcom, Marvell, Intel, Cisco, NVIDIA, Ayar Labs, Ranovus, Coherent, Lumentum, TSMC, IBM, AMD, Molex, Corning, TE Connectivity, POET Technologies, Sumitomo Electric, Furukawa Electric, Celestial AI, GlobalFoundries |
Report overview
Segments covered: type, component, application, end user.
The global Co-Packaged Optics (CPO) market is emerging as a transformative segment of next-generation data center and high-performance computing (HPC) interconnect infrastructure, addressing the growing challenges of power consumption, bandwidth density, and signal integrity. CPO integrates optical engines directly alongside host electrical ICs such as switch ASICs, substantially shortening electrical traces and overcoming the limitations of conventional pluggable optical transceivers. This architecture is becoming increasingly important as the industry transitions toward 51.2 Tbps and higher-capacity switch platforms for AI clusters and hyperscale networks. Broadcom's 51.2T Bailly CPO switch platform demonstrated approximately 70% lower optical interconnect power consumption and an eightfold improvement in silicon area efficiency compared with traditional pluggable transceivers, while pluggable optics account for nearly 50% of the power consumption and more than 50% of the cost of conventional switch systems.
The technology is enabled by advances in silicon photonics and the industry's move toward 800G and 1.6T Ethernet. The IEEE 802.3dj Task Force is developing standards for 200 Gb/s, 400 Gb/s, 800 Gb/s and 1.6 Tb/s Ethernet operation, reflecting the growing demand for ultra-high-speed connectivity in AI and cloud environments. Furthermore, commercial deployments of 51.2T CPO switches have begun entering volume production, with benchmark testing showing more than 40% system-level power savings compared with systems based on conventional pluggable transceivers.
The market is primarily driven by the explosive growth of artificial intelligence, machine learning and cloud services, which require increasingly higher bandwidth and lower latency. As AI clusters scale to hundreds of thousands of accelerators, traditional copper interconnects and pluggable optics are approaching their physical and power limits. Consequently, hyperscale operators and semiconductor companies are accelerating the adoption of optical I/O and co-packaged architectures to enable higher throughput, improved energy efficiency and lower total cost of ownership, positioning CPO as a foundational technology for future AI infrastructure.
A primary driver for the CPO market is the urgent need to overcome the 'power wall' and 'bandwidth bottleneck' in data centers, particularly with the advent of 51.2T and 102.4T network switch ASICs. Traditional pluggable optics consume significant power, with interconnect power consumption ranging from 15-25 pJ/bit. CPO solutions, by integrating optics closer to the ASIC, can reduce this to under 5 pJ/bit, representing up to a 4x reduction in energy per bit. This substantial power saving is critical for managing the soaring energy demands of hyperscale data centers and AI clusters. Furthermore, CPO enables higher bandwidth density, as the physical space on the front panel of a 1RU switch becomes insufficient for traditional pluggable modules at 102.4T speeds, making CPO an architectural necessity for future network generations.
Despite its advantages, the CPO market faces significant restraints, primarily stemming from manufacturing complexity and the nascent stage of its ecosystem development. The integration of optical and electrical components on a single package requires advanced heterogeneous integration techniques, including precision alignment of optical fibers and thermal management of closely packed components. This complexity leads to higher manufacturing costs and lower yields compared to traditional discrete components. Thermal management is a critical challenge, as CPO relocates the heat source (lasers/optics) closer to the ASIC, necessitating innovative cooling solutions. Additionally, the CPO ecosystem, including test and measurement equipment, supply chain, and standardization efforts, is still maturing, which can hinder broader adoption and increase development costs for early adopters.
Significant opportunities for growth in the CPO market are driven by the relentless demand for AI/ML acceleration, the proliferation of edge computing, and the long-term potential of quantum networking. AI clusters, with their massive GPU-to-GPU interconnects, are the 'primary early CPO battleground,' where CPO is critical for maintaining signal integrity and reducing latency in massive Ethernet/InfiniBand fabrics. As AI processing moves closer to the data source, edge computing infrastructure will increasingly require CPO for high-bandwidth, low-power connectivity. Furthermore, CPO is a foundational technology for future quantum networking, enabling the ultra-low latency and high-fidelity optical links required for quantum entanglement distribution and quantum computing interconnects. Continuous advancements in silicon photonics and heterogeneous integration will unlock new applications and drive market expansion.
Report infographic
Market dynamics
2 factors across 1 forceTransition to Higher Data Rates (800G, 1.6T, 3.2T)
A pivotal trend in the Co-Packaged Optics (CPO) market is the industry's migration toward higher data rates, with 800G deployments expanding and 1.6T and 3.2T interfaces under development. This evolution is being driven by surging bandwidth requirements in AI clusters and hyperscale data centers. According to the IEEE 802.3dj Task Force, ongoing standards development targets 200 Gb/s electrical lanes supporting 800GbE and 1.6TbE Ethernet, while the OIF has completed CEI-224G specifications for 224 Gbps electrical interfaces, laying the foundation for next-generation optical interconnects. The Ethernet Alliance estimates that global Ethernet switch bandwidth has increased from 640 Gbps systems a decade ago to 51.2 Tbps platforms today, representing an 80-fold increase. As conventional pluggable optics face power and density limitations, CPO architectures are increasingly viewed as a practical solution for enabling ultra-high bandwidth within acceptable energy budgets.
Increased Adoption in AI/ML Infrastructure
The most significant trend is the accelerating adoption of CPO in AI and machine learning infrastructure. According to the International Energy Agency (IEA), global investment in data centers reached approximately USD 500 billion in 2024, with AI-related infrastructure accounting for a rapidly increasing share. Meanwhile, the U.S. Department of Energy's Frontier supercomputer delivers more than 1 exaflop of performance using over 9,400 nodes interconnected through high-speed networking, highlighting the growing need for scalable interconnect technologies. AI workloads are highly bandwidth-intensive, requiring efficient communication between GPUs, accelerators, and switches. Consequently, leading companies such as Broadcom, NVIDIA, Marvell, and Ayar Labs are actively developing CPO-enabled platforms to support next-generation AI superclusters. Broadcom has reported that co-packaged optics can reduce optical interconnect power consumption by nearly 70% compared with traditional pluggable transceivers, making the technology increasingly attractive as AI models continue to expand in size and complexity.
Table of contents
12 chapters · 117 sections · 318 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Type | 800G CPO | 1.6T and above CPO |
| By Component | Optical engines | — |
| By Application | Data center | — |
| By End User | Cloud service providers (CSPs) | — |
By Type
- The 800G CPO segment is expected to hold the largest share in 2026, driven by its early commercial deployments in AI scale-out fabrics and initial 51.2T switch cycles.
- However, the 1.6T and above CPO segment is projected to exhibit the fastest growth during the forecast period as next-generation 102.4T and 204.8T switch architectures become prevalent.
- Lower data rate CPO solutions (e.g., 400G) will continue to find niche applications, but the market momentum is clearly shifting towards higher bandwidths.
By Component
- The optical engines segment is expected to account for the largest share in 2026.
- Optical engines, comprising lasers, modulators, photodetectors, and silicon photonics waveguides, are the core of CPO technology, responsible for electro-optical conversion.
- The electrical ICs (e.g., switch ASICs, DSPs) co-packaged with the optics also represent a significant segment.
- Other components, including thermal management solutions, connectors, and substrates, are crucial for the overall performance and reliability of CPO modules.
By Application
- The data center segment is expected to account for the largest share in 2026.
- Hyperscale data centers, driven by the exponential growth of AI, machine learning, and cloud services, are the primary adopters of CPO due to their immense bandwidth and power efficiency requirements.
- High-performance computing (HPC) also represents a significant application, where CPO enables supercomputing systems to achieve unprecedented computational speeds.
- Other applications, including telecommunications and specialized industrial networks, are emerging as potential growth areas for CPO.
By End User
- Cloud service providers (CSPs) are expected to hold the largest share in 2026.
- CSPs, operating hyperscale data centers, are at the forefront of CPO adoption to manage their massive and rapidly growing network traffic.
- Enterprise data centers are also expected to gradually adopt CPO as their bandwidth needs increase.
- Telecommunications service providers will integrate CPO into their core and access networks to support 5G and future broadband demands.
- Other end users, including government and research institutions, will leverage CPO for specialized HPC and secure communication networks.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global CPO market in 2026, primarily due to the concentration of leading hyper-scale data center operators (e.g., Google, Microsoft, Meta) and AI hardware giants (e.g., NVIDIA, Broadcom, Marvell). These companies are at the forefront of CPO research, development, and deployment, driving early adoption and technological innovation. The region also benefits from a robust ecosystem of silicon photonics startups and academic research institutions, fostering continuous advancements in CPO technology. North America
Asia-Pacific
Asia Pacific is projected to witness significant growth during the forecast period, fueled by its unparalleled dominance in semiconductor manufacturing and advanced packaging facilities. Countries like China, Taiwan (TSMC), and Japan are critical hubs for the production and assembly of CPO components. The region also has a rapidly expanding data center infrastructure and a growing demand for AI and cloud services, which will drive the adoption of CPO solutions in local markets. Asia Pacific
Europe
Europe represents a growing market for CPO, particularly in specialized HPC, scientific research, and telecommunications infrastructure. The region has strong initiatives in developing advanced photonics technologies and is investing in next-generation data centers. European companies and research institutions are actively contributing to CPO standardization efforts and developing innovative solutions for energy-efficient optical interconnects. Europe
Latin America
Latin America represents an emerging market for CPO, with gradual adoption driven by increasing investments in digital infrastructure and the growing demand for advanced computing solutions in various industries. While still in its nascent stages, the region is expected to see increased interest in CPO technology as local industries seek to improve efficiency and performance in areas like data centers and telecommunications. Government initiatives to promote technological development and attract foreign investment will play a crucial role in accelerating market growth. Latin America
Middle East & Africa
The Middle East & Africa region is expected to witness steady growth in the CPO market, primarily driven by investments in data centers, smart city initiatives, and the development of local technology ecosystems. Countries like the UAE and Saudi Arabia are actively diversifying their economies and investing in advanced technologies, including AI. The increasing demand for AI and HPC solutions in various sectors will contribute to the adoption of CPO in this region. Middle East & Africa
Competitive landscape
The competitive landscape of the global CPO market is characterized by strategic partnerships between semiconductor companies, optical component manufacturers, and data center operators. Key players are actively involved in standardization bodies like the OIF and Ethernet Alliance to ensure interoperability and accelerate market adoption. Technological leadership in silicon photonics, advanced packaging, and high-speed electrical interfaces is crucial for gaining a competitive edge. The market is also seeing increasing collaboration between CPO developers and AI hardware providers to optimize solutions for next-generation AI accelerators and network architectures.
- Broadcom
- Marvell
- Intel
- Cisco · Acacia
- NVIDIA
- Ayar Labs
- Ranovus
- Coherent
- Lumentum
- TSMC
- IBM
- AMD
- Molex
- Corning
- TE Connectivity
- POET Technologies
- Sumitomo Electric
- Furukawa Electric
- Celestial AI
- GlobalFoundries
Frequently asked questions
The market is projected to reach USD 20.4 billion by 2036, growing at a CAGR of 32.4% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Co-Packaged Optics (CPO) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRSE - 1042065). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/co-packaged-optics-market-6748