Targeted Protein Degradation (TPD) Market (2026-2036)
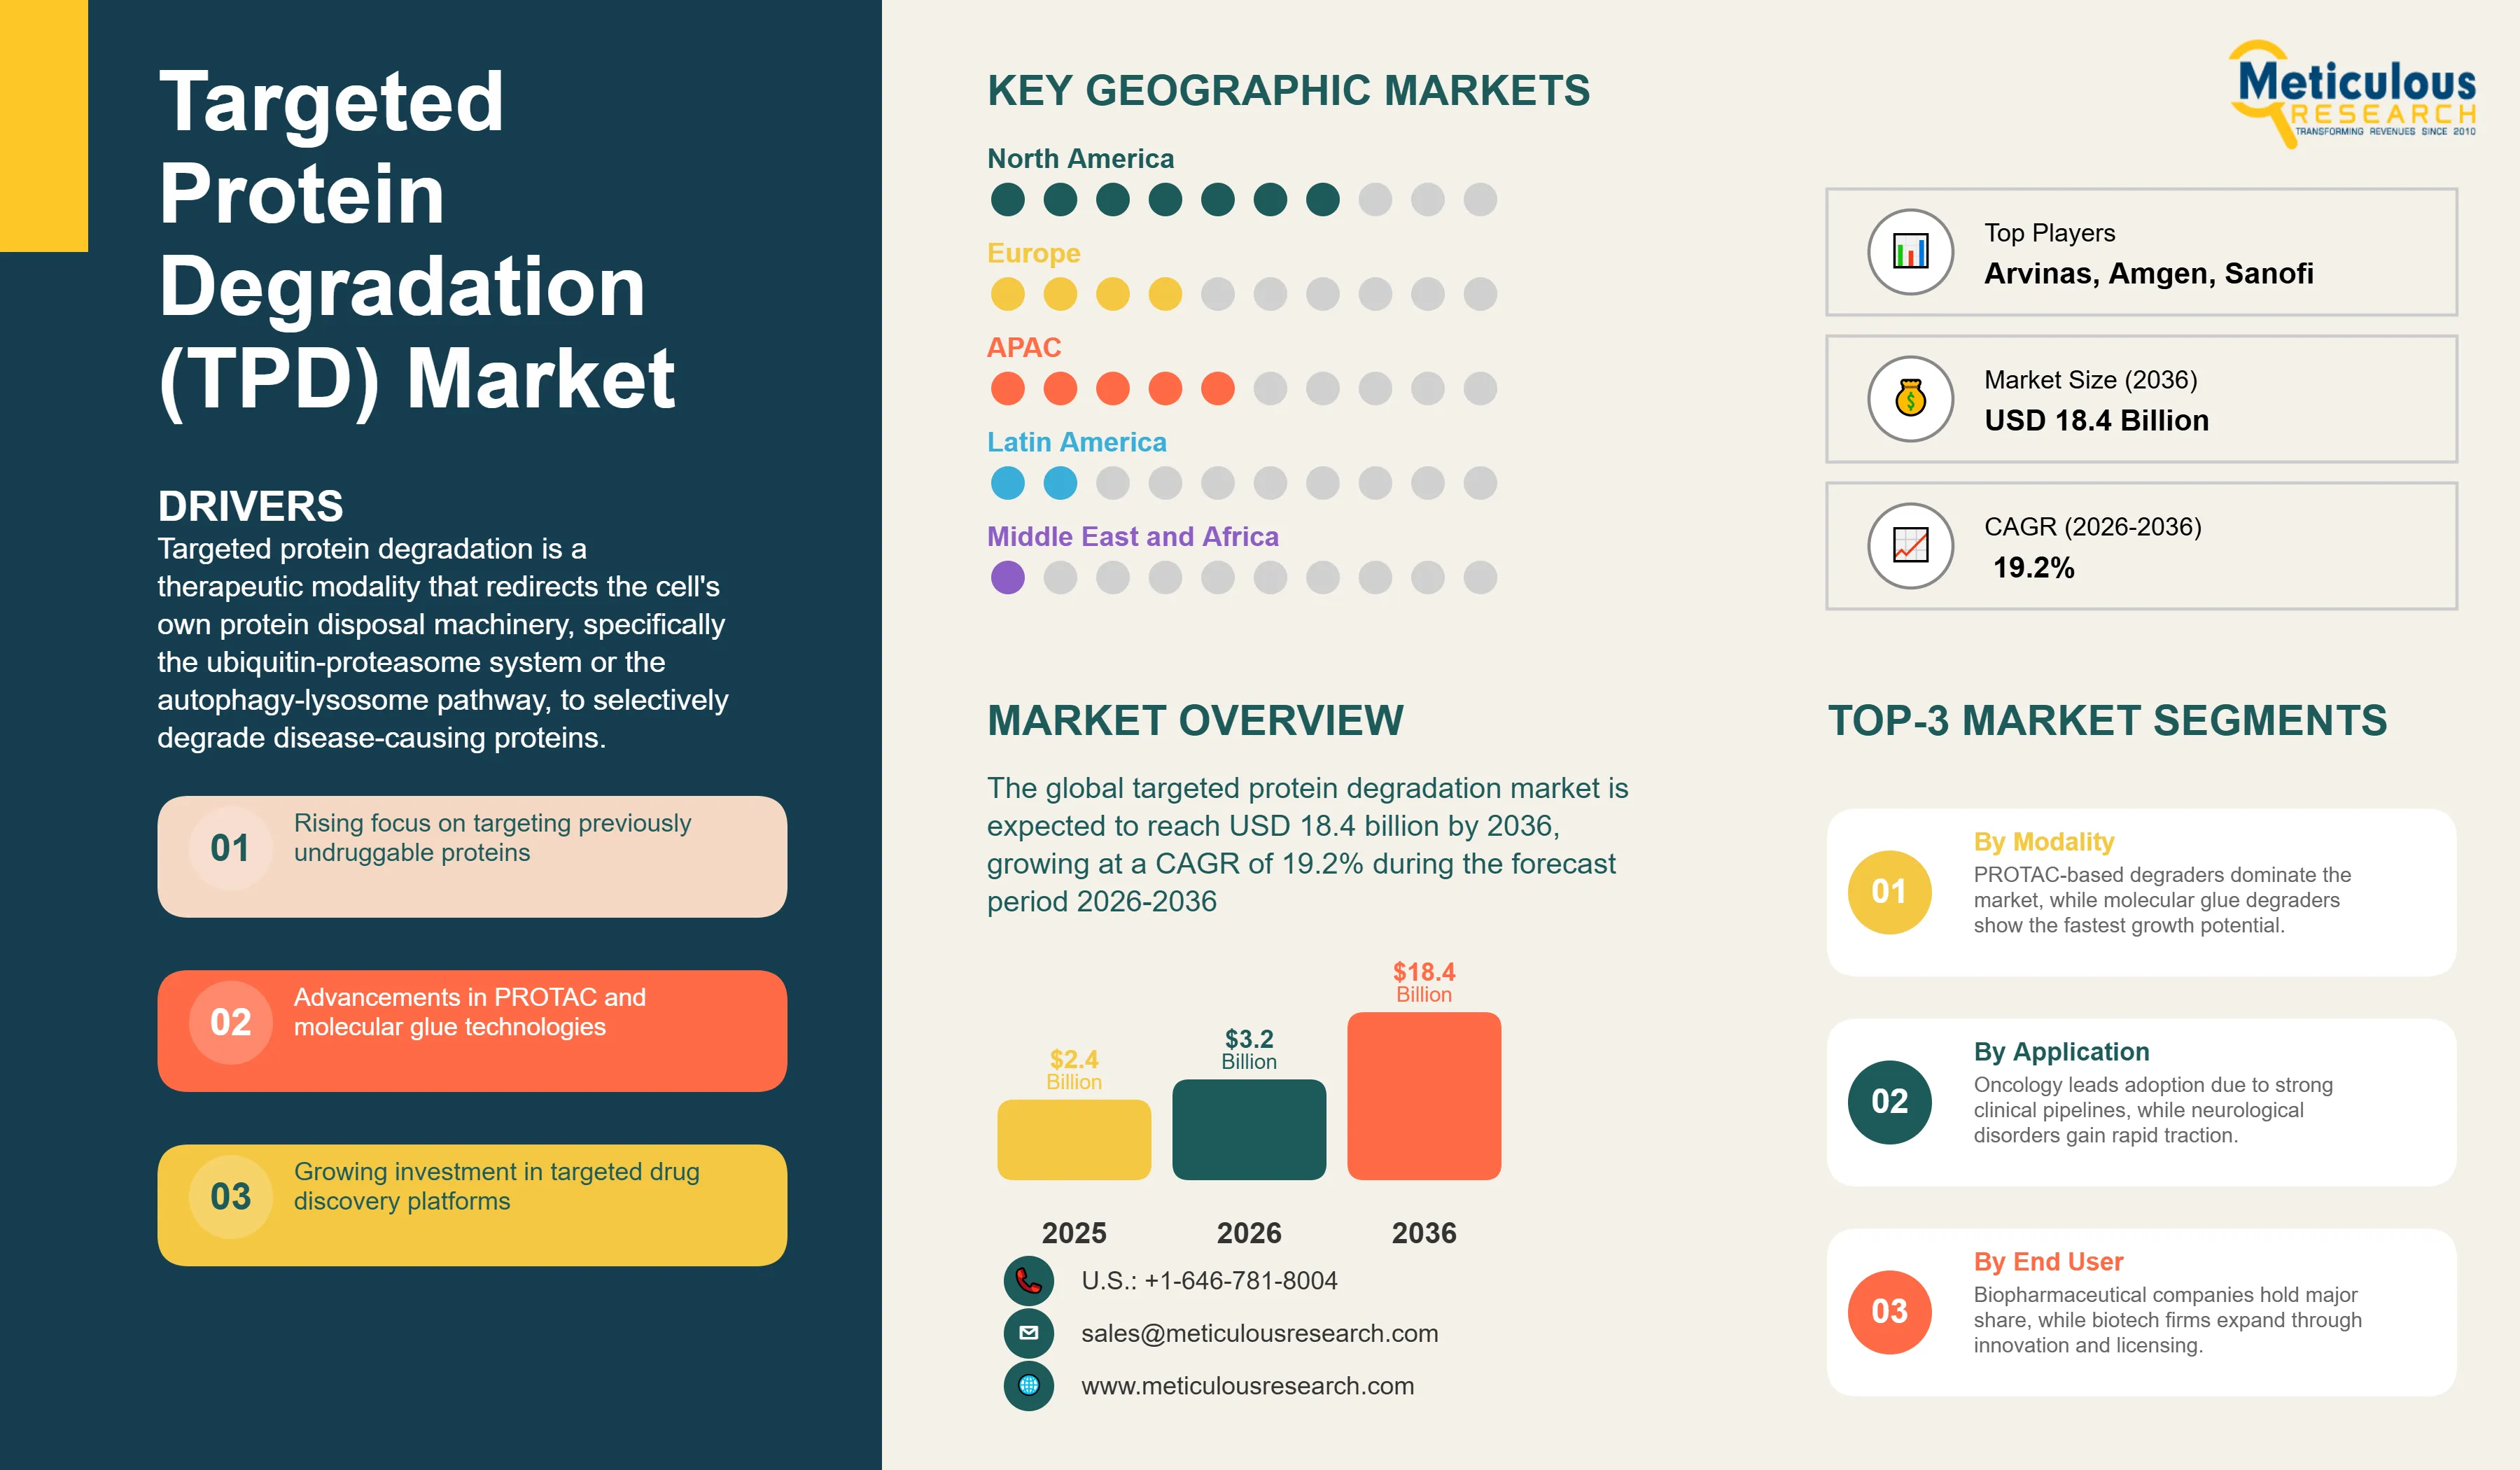
The global targeted protein degradation market was valued at USD 2.4 billion in 2025. This market is expected to reach USD 18.4 billion by 2036 from an estimated USD 3.2 billion in 2026, growing at a CAGR of 19.2% during the forecast period 2026-2036.
- Published
- May 2026
- Pages
- 278
- Format
- PDF + Excel
- Report ID
- MRHC - 1041980
- Base year
- 2025
- 2025 · BASELINE
- $2.40B
- 2036
- $18.40B
- CAGR 2026–2036
- 19.2%
2025 baseline · 2026–2036 forecast at 19.2% CAGR · hover a bar for the value
Key highlights
The global targeted protein degradation market is projected to reach USD 18.4 billion by 2036.
The market is expected to grow at a CAGR of 19.2% during the forecast period 2026-2036.
The global TPD market was valued at USD 2.4 billion in 2025 and is estimated to reach USD 3.2 billion in 2026.
North America is expected to dominate the global TPD market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By modality, the PROTAC-based degraders segment is expected to hold the largest share of the market in 2026, while the molecular glue degraders segment is projected to register the highest CAGR during the forecast period.
By product and service, the therapeutics (clinical-stage) segment is expected to hold the largest share in 2026, while the platforms and technologies segment is projected to register the highest CAGR during the forecast period.
By development stage, the clinical stage segment is expected to hold the largest share in 2026 and is also projected to register the fastest advancement during the forecast period as programs progress toward Phase 3.
By application, the oncology segment is expected to hold the largest share in 2026, while the neurological disorders segment is projected to register the highest CAGR during the forecast period.
By end user, the biopharmaceutical companies segment is expected to hold the largest share in 2026, while the biotechnology companies segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 18.4 Billion |
| Market Size in 2026 | USD 3.2 Billion |
| Market Size in 2025 | USD 2.4 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 19.2% |
| Format | PDF, Excel & Cloud Portal · 278 pages |
| Dominating Modality | PROTAC-based Degraders |
| Fastest Growing Modality | Molecular Glue Degraders |
| Dominating Product & Service | Therapeutics (Clinical-stage) |
| Fastest Growing Product & Service | Platforms & Technologies |
| Dominating Development Stage | Clinical Stage |
| Fastest Growing Development Stage | Clinical Stage (Phase II/III advancement) |
| Dominating Application | Oncology |
| Fastest Growing Application | Neurological Disorders |
| Dominating End User | Biopharmaceutical Companies |
| Fastest Growing End User | Biotechnology Companies |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: modality, product & service, application, end user.
According to Arvinas' 2025 annual report, the company's ARV-471 (vepdegetamide), a PROTAC degrader targeting estrogen receptor, demonstrated a 37.1% clinical benefit rate in heavily pretreated ER-positive HER2-negative breast cancer in its Phase 2 VERITAC-2 trial, and this program along with ARV-766 for prostate cancer represent the most clinically advanced PROTAC therapeutics globally, providing the commercial proof-of-concept that is attracting billions of dollars of pharmaceutical industry investment into the TPD field.
Targeted protein degradation is a therapeutic modality that redirects the cell's own protein disposal machinery, specifically the ubiquitin-proteasome system or the autophagy-lysosome pathway, to selectively degrade disease-causing proteins. Unlike conventional small molecule inhibitors, which bind to the active site of a target protein and block its function, a degrader molecule acts as a chemical bridge connecting the target protein to an E3 ubiquitin ligase enzyme, which tags the target with ubiquitin chains that mark it for destruction by the proteasome. This event-driven pharmacology has two profound advantages over occupancy-based inhibition: first, the degrader molecule is released intact after each catalytic degradation event and can recruit additional target molecules in a substoichiometric manner, meaning very small drug doses can eliminate large quantities of disease protein; second, degradation eliminates all protein functions, including scaffolding and protein-protein interaction functions that cannot be inhibited by blocking the active site, potentially making previously undruggable proteins tractable.
The market is growing rapidly because the pharmaceutical industry has recognized TPD as the most significant new drug modality since monoclonal antibodies, capable of addressing the estimated 80 to 90% of disease-relevant proteins that are currently undruggable by conventional small molecules because they lack well-defined binding pockets suitable for inhibitor design. According to a 2024 analysis published in Nature Reviews Drug Discovery, the number of PROTAC-type molecules in active clinical development exceeded 30 programs across oncology, immunology, and other therapeutic areas, more than doubling from 14 programs in 2021. The publication of Phase 2 clinical data from Arvinas' vepdegetamide PROTAC in breast cancer, which demonstrated clinically meaningful objective responses in patients who had failed multiple prior lines of therapy including CDK4/6 inhibitors and fulvestrant, represents the most important clinical validation milestone in the field's history.
The broader pharmaceutical industry's recognition of TPD is reflected in the scale of investment. According to Evaluate Pharma's 2025 drug development report, TPD-focused companies collectively raised over USD 2 billion in venture capital and public equity financing in 2024, with major pharmaceutical companies including Bristol Myers Squibb, Pfizer, Merck, Novartis, and Sanofi all entering the field through licensing deals, acquisitions, or internal programs. Bristol Myers Squibb's acquisition of Celgene in 2019 brought the molecular glue immunomodulatory drug lenalidomide, already a blockbuster cancer treatment, into its portfolio and established BMS as a leading molecular glue developer. The company disclosed in its 2025 R&D pipeline communications that molecular glue and PROTAC programs represent one of its highest-priority internal development areas.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Focus on "Undruggable" Targets
The fundamental promise of targeted protein degradation, that it can degrade disease-relevant proteins that cannot be inhibited by conventional small molecules, is addressing one of drug discovery's most longstanding limitations. Conventional small molecule drugs require binding to a well-defined hydrophobic pocket on their target protein, a structural feature that approximately 80 to 90% of disease-relevant proteins lack. According to 2024 review literature, the human proteome contains roughly 20,000 proteins, but only a minority have been validated as drug targets, leaving a large fraction of disease-relevant proteins still considered difficult to drug with conventional small molecules or biologics. KRAS is one of the most important oncogenic targets in human cancer, historically viewed as undruggable until the approval of sotorasib for KRAS G12C mutations. It is now also a major focus for PROTAC and other targeted protein degradation programs.
Advancements in PROTAC & Molecular Glue Technologies
The technical foundations of PROTAC design have matured considerably since the first proof-of-concept studies, with improvements in linker chemistry, E3 ligase recruitment, cell permeability, and selectivity that are enabling the design of drug-like degraders with favorable pharmacokinetic and pharmacodynamic profiles. According to a 2025 review in the Journal of Medicinal Chemistry, the number of distinct E3 ligases being utilized for PROTAC design has expanded from the initial two predominantly used (CRBN and VHL) to over 10 validated ligases, significantly expanding the range of cellular compartments and target proteins accessible to PROTAC degradation. The development of cereblon E3 ligase modulators, which are both the mechanism of lenalidomide and the platform for most advanced PROTAC programs, has produced a deep understanding of molecular glue-ligase interactions that is informing next-generation molecular glue design at Monte Rosa, C4 Therapeutics, and BMS.
Table of contents
13 chapters · 158 sections · 278 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Modality | PROTAC-based Degraders | Molecular glue degraders |
| By Product & Service | Therapeutics (Clinical-stage) | Platforms and technologies |
| By Development Stage | Clinical Stage | Clinical stage |
| By Application | Oncology | Neurological disorders |
| By End User | Biopharmaceutical Companies | Biotechnology companies |
By Modality
- PROTAC-based Degraders to Hold the Largest Share
- The PROTAC-based degraders segment is expected to account for the largest share of the global TPD market.
- PROTACs benefit from the most extensive clinical development history in the TPD field, with Arvinas' ARV-471 and ARV-766, Kymera's KT-333 and KT-413, Nurix's NX-2127, and C4 Therapeutics' CFT8919 representing a growing cohort of PROTAC programs in active clinical trials.
- The PROTAC modality also benefits from the most developed rational design frameworks, with published structure-activity relationships, computational models for ternary complex prediction, and extensive medicinal chemistry optimization data accumulated across the field since the first PROTAC clinical programs began in 2019.
- According to a 2024 Nature Reviews Drug Discovery analysis, PROTACs represented over 65% of all active TPD clinical programs.
- However, the molecular glue degraders segment is projected to register the highest CAGR during the forecast period.
- BMS's mezigdomide receiving FDA Breakthrough Therapy Designation for multiple myeloma per its 2025 pipeline communications, combined with Monte Rosa's demonstration that molecular glues can be rationally designed using the QuEEN computational platform, has transformed molecular glues from serendipitously discovered compounds into a rationally designable drug class.
- The structural simplicity of molecular glues relative to the bifunctional PROTAC structure gives them inherently better drug-like properties including molecular weight, lipophilicity, and cell permeability, which are expected to translate into better oral bioavailability and broader therapeutic applicability.
By Product & Service
- Therapeutics (Clinical-stage) to Hold the Largest Share
- The therapeutics segment, specifically clinical-stage candidates, is expected to account for the largest share of the global TPD market.
- Arvinas' ARV-471 and ARV-766 PROTAC programs, BMS's mezigdomide molecular glue program, and the growing cohort of PROTAC and molecular glue programs from Kymera, Nurix, and C4 Therapeutics collectively represent a clinical-stage asset base with significant commercial value reflected in licensing deals, partnership payments, and company valuations.
- However, the platforms and technologies segment is projected to register the highest CAGR during the forecast period.
- The growing recognition that the competitive advantage in TPD lies in proprietary platform capabilities for degrader design, E3 ligase discovery, and molecular glue identification is driving above-average investment in TPD discovery platform development and licensing.
- Monte Rosa's QuEень platform, Kymera's ImPROTAC platform, and multiple AI-enhanced degrader design platforms represent the growing commercial value of TPD technology platforms that are being licensed to pharmaceutical companies at increasingly large deal values.
By Development Stage
- Clinical Stage to Hold the Largest Share
- The clinical stage segment is expected to account for the largest share of the global TPD market by revenue, reflecting that the commercial value in the market is concentrated in clinical-stage assets that are generating licensing deal payments, partnership milestones, and direct R&D investment from pharmaceutical companies.
- According to ClinicalTrials.gov's 2025 database, over 30 PROTAC and molecular glue programs are registered in active clinical trials, a number that has more than doubled since 2021 per the 2024 Nature Reviews Drug Discovery analysis.
- The clinical stage segment is also projected to see the most significant advancement during the forecast period as the current wave of Phase 1 and Phase 2 programs mature into Phase 2 and Phase 3 studies, generating progressively more valuable clinical data packages.
- Arvinas' planned Phase 3 initiation for ARV-471 in combination with palbociclib per its 2025 investor communications and BMS's Phase 3 advancement of mezigdomide per its 2025 pipeline disclosure represent the leading commercial milestones expected in the clinical stage segment.
By Application
- Oncology to Hold the Largest Share
- The oncology segment is expected to account for the largest share of the global TPD market.
- Oncology was the first clinical application for PROTAC and molecular glue degraders for the same reasons it is the first application for most novel therapeutic modalities: the urgent medical need, the high commercial value of effective treatments, and the relatively accessible regulatory pathways for cancer drugs accelerating clinical development.
- All of the most advanced clinical TPD programs are in oncology, including Arvinas' breast and prostate cancer PROTACs, BMS's multiple myeloma molecular glue, and the Kymera and C4 Therapeutics hematological malignancy programs.
- However, the neurological disorders segment is projected to register the highest CAGR during the forecast period.
- The protein aggregation diseases that define neurodegeneration represent the most scientifically compelling application for protein degradation outside oncology, as accumulation of misfolded tau in Alzheimer's and alpha-synuclein in Parkinson's drives neuronal death in ways that TPD approaches are theoretically well-suited to address.
- According to the Alzheimer's Association's 2025 Alzheimer's Disease Facts and Figures, approximately 7.2 million Americans are living with Alzheimer's disease, representing a very large and urgent unmet medical need that is driving growing investment in degrader approaches for tauopathy.
By End User
- Biopharmaceutical Companies to Hold the Largest Share
- The biopharmaceutical companies segment is expected to account for the largest share of the global TPD market.
- Large pharmaceutical companies including Bristol Myers Squibb, Pfizer, Merck, Novartis, AbbVie, and Sanofi are collectively investing very large sums in TPD through internal programs, licensing agreements with specialist biotech companies, and direct acquisitions.
- Bristol Myers Squibb's internal molecular glue programs including mezigdomide, Sanofi's licensing deal with Kymera valued potentially around USD 1 billion in milestones per Kymera's 2025 annual report, and multiple other large pharma TPD investments collectively make biopharmaceutical companies the largest end user category by investment and revenue.
- However, the biotechnology companies segment is projected to register the highest CAGR during the forecast period.
- Specialist TPD biotechnology companies including Arvinas, Kymera, Nurix, C4 Therapeutics, Monte Rosa, and a growing cohort of newer entrants represent the innovation engine of the TPD market and are growing their revenues through licensing deals, milestone payments, and direct program development at above-average rates as their clinical programs advance and their platform capabilities are increasingly recognized as strategically valuable by larger pharmaceutical companies.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global TPD market. The United States is the center of global TPD innovation, home to Arvinas, Kymera Therapeutics, Nurix Therapeutics, C4 Therapeutics, and Monte Rosa Therapeutics, collectively the five most commercially advanced specialist TPD companies globally. The concentration of leading academic TPD research programs, including Professor Craig Crews' laboratory at Yale where PROTAC technology was invented and major programs at Harvard, Stanford, and MIT, provides the scientific talent pipeline for U.S. TPD company formation. PhRMA’s 2025 reporting indicates that U.S. biopharmaceutical R&D investment reached a new high in 2024, and targeted protein degradation programs are an increasingly important part of that capital allocation. FDA engagement with novel drug modalities has also helped improve regulatory visibility for first-in-human and U.S.-led development strategies. TPD Market by Region: North America Leading by Share, Asia-Pacific by Growth
Asia-Pacific
Fastest growthHowever, the Asia-Pacific TPD market is expected to grow at the fastest CAGR during the forecast period. China has developed a substantial domestic TPD research and commercial ecosystem, with multiple Chinese biotechnology companies including Cullgen, Haisco Pharmaceutical, and Hinova Pharmaceuticals developing PROTAC programs for oncology indications. According to a 2025 analysis of ClinicalTrials.gov and Chinese clinical trial registries, Chinese TPD programs in clinical development have grown significantly since 2022, with China-based companies initiating clinical trials for PROTAC degraders in hematological malignancies and solid tumors. Japan's pharmaceutical companies including Eisai, which is listed in the report's company profiles, have been active in exploring TPD approaches for neurodegenerative disease applications, leveraging Eisai's strong central nervous system research expertise. South Korea's growing biotechnology industry and Singapore's biomedical research hub are contributing to Asia-Pacific's accelerating TPD ecosystem development.
Europe
Europe is a strong TPD scientific and commercial market, anchored by the academic origins of the field at the interface of European and U.S. universities and by the commercial activities of major European pharmaceutical companies. Novartis, Boehringer Ingelheim, and Sanofi all have active internal TPD programs and have disclosed licensing arrangements with specialist TPD companies. The UK's Wellcome Sanger Institute and multiple European universities are active in TPD target identification and degrader design research. Switzerland, home to Novartis and Roche, is a center of European pharmaceutical TPD investment and clinical development activity. The Netherlands hosts a growing biotechnology sector with academic spin-out TPD programs.
Competitive landscape
- Arvinas Inc. (U.S.)
- C4 Therapeutics Inc. (U.S.)
- Kymera Therapeutics Inc. (U.S.)
- Nurix Therapeutics Inc. (U.S.)
- Monte Rosa Therapeutics Inc. (U.S.)
- Bristol Myers Squibb (U.S.)
- Amgen Inc. (U.S.)
- Genentech/Roche (U.S./Switzerland)
- Boehringer Ingelheim · Germany
- Novartis AG · Switzerland
- Pfizer Inc. (U.S.)
- Merck & Co. Inc. (U.S.)
- Sanofi · France
- AbbVie Inc. (U.S.)
- Eisai Co. Ltd. · Japan
Frequently asked questions
The global targeted protein degradation market is expected to reach USD 18.4 billion by 2036 from an estimated USD 3.2 billion in 2026, at a CAGR of 19.2% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Targeted Protein Degradation (TPD) Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRHC - 1041980). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/targeted-protein-degradation-market-6663