Metal Forging Market (2025-2032)
The Metal Forging Market is expected to reach $153.9 billion by 2032, at a CAGR of 7.4% from 2025 to 2032.
- Published
- May 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041196
- Base year
- 2024
- 2032 · FORECAST
- $153.9B
- 2032
- $153.9B
- CAGR 2025–2032
- 7.4%
2024 baseline · 2025–2032 forecast at 7.4% CAGR · hover a bar for the value
Key highlights
By Method: In 2025, the Open Die Forging Segment to Dominate the Metal Forging Market
By Material: In 2025, the Steel Segment to Dominate the Metal Forging Market
By End-use Industry: In 2025, the Automotive Segment to Dominate the Metal Forging Market
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR | 7.4% |
| Market Size | USD 153.9 Billion by 2032 |
| Segments Covered | By Method · Closed Die Forging · Open Die Forging · Cold Forging · Roll Forging · Upset Forging · Other Methods · By Material · Steel · Aluminum · Titanium · Nickel Alloys · Magnesium · Other Materials · By End-use Industry · Automotive · Oil & Gas · Aerospace & Defense · Construction · Agriculture · Machines & Tools · Mining & Metals · Other End-use Industries |
| Countries Covered | Europe (Germany, U.K., France, Italy, Spain, Netherlands, Switzerland, Sweden, Denmark, and Rest of Europe), Asia-Pacific (China, Japan, India, South Korea, Australia & New Zealand, Indonesia, Thailand, Vietnam, Malaysia, Singapore, and Rest of Asia- Pacific), North America (U.S., Canada), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (UAE, Israel, and Rest of Middle East & Africa) |
| Key Companies | Arconic Corporation (U.S.), Nippon Steel Corporation (Japan), Precision Castparts Corp. (U.S.), Larsen & Toubro Limited (India), Bharat Forge Limited (India), thyssenkrupp AG (Germany), BRÜCK GmbH (Germany), ELLWOOD Group, Inc. (U.S.), Metal Forging Pvt. Ltd. (India), CELSA Group (Spain) Ovako AB (Sweden), Lolu Alloys Ltd (U.K.), Scot Forge Company (U.S.), Alcoa Corporation (U.S.), and ATI Inc.(U.S.) |
Report overview
Segments covered: method, material, end-use industry. Regions: Europe, Asia-Pacific, North America, Latin America, Middle East & Africa.
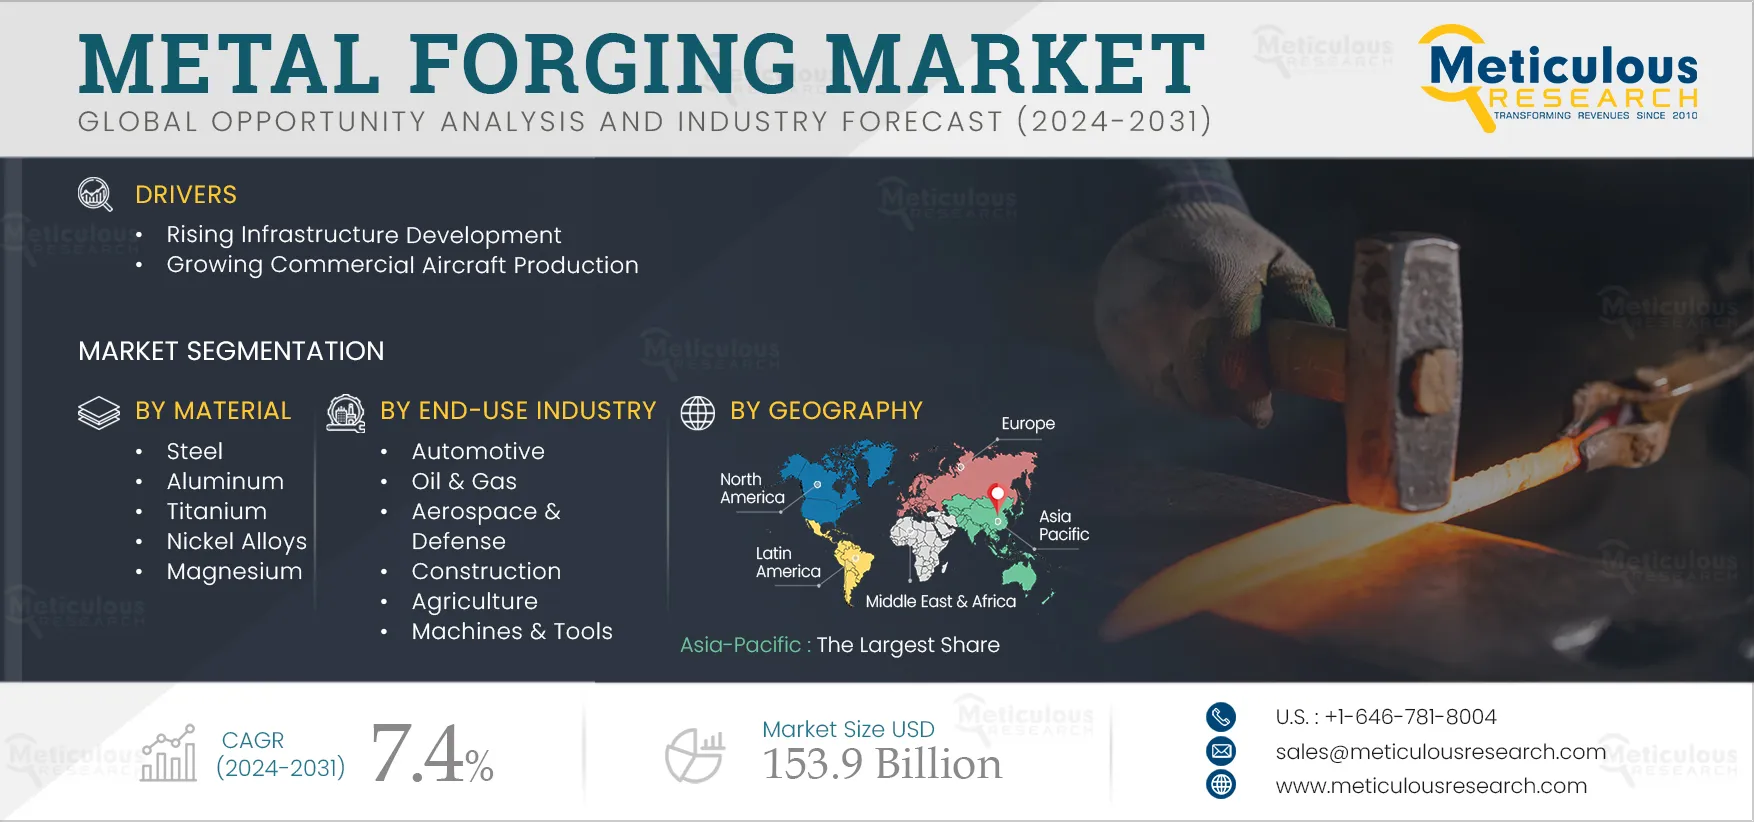
The growth of the metal forging market is driven by the rising infrastructure development and growing commercial aircraft production. Furthermore, the adoption of industry 4.0 technology and advancements in forging technology are expected to offer significant growth opportunities for players operating in the metal forging market.
Report infographic
Market dynamics
5 factors across 3 forcesRising Infrastructure Development
Rising infrastructure development plays a pivotal role in driving the growth of the metal forging market through several interconnected mechanisms. Infrastructure projects such as roads, bridges, dams, and buildings require a substantial amount of metal components, ranging from structural supports to specialized parts like hinges and fasteners. Metal forging provides a cost-effective method for producing these components in large quantities while ensuring high strength and durability, meeting the stringent requirements of infrastructure projects. Infrastructure development frequently involves expanding transportation networks such as highways, railways, and airports. These projects require a wide range of forged components for vehicles, trains, aircraft, and related infrastructure. Forged metal parts offer the necessary strength-to-weight ratio, reliability, and safety standards demanded by the transportation sector, driving demand for forging services. Such factors help to drive the growth of the market.
Growing Commercial Aircraft Production
The expansion of commercial aircraft production significantly contributes to the growth of the metal forging market as commercial aircraft manufacturers prioritize lightweight materials to improve fuel efficiency and reduce operating costs. Forged metal parts offer an excellent combination of strength and weight savings compared to cast or machined components. Components such as landing gear parts, engine components, wing structures, and fuselage frames require the superior mechanical properties provided by forging processes. Advances in aerospace engineering and design often require innovative solutions to meet evolving performance criteria. Forged metal parts play a crucial role in enabling these advancements, whether it's the development of next-generation aircraft with improved fuel efficiency, enhanced aerodynamics, or greater passenger comfort. Forging processes allow for the production of complex shapes and geometries that traditional manufacturing methods struggle to achieve. Such factors help to drive the growth of the market.
Table of contents
11 chapters · 119 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Method | Open Die Forging | Cold forging |
| By Material | Steel | Aluminum |
| By End-use Industry | Automotive | Construction |
By Method
- The Open Die Forging Segment to Dominate the Metal Forging Market
- The open die forging segment is expected to account for the largest share of above 49.0% of the metal forging market.
- The growth of this segment is attributed to its ability to produce a wide range of shapes and sizes, from simple bars to complex geometries.
- This versatility attracts industries with diverse forging needs, including aerospace, automotive, oil and gas, construction, and heavy machinery.
- Open die forging also offers flexibility in production volumes.
- It can efficiently produce both small batches and large quantities of parts, allowing manufacturers to adapt to varying market demands and customer orders without significant retooling or setup costs.
- However, the cold forging segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment can be attributed to various factors, as it enhances the mechanical properties of the forged parts, such as strength, hardness, and durability.
- The cold working process strengthens the metal by inducing strain hardening and aligning the grain structure, resulting in parts with superior mechanical performance.
- These enhanced properties make cold-forged components desirable for applications requiring high strength and reliability, such as automotive, aerospace, and industrial equipment.
- Cold forging is a high-speed manufacturing process capable of producing parts at a rapid rate.
- With advancements in technology and automation, cold forging systems can achieve high production volumes while maintaining consistent quality.
By Material
- The Steel Segment to Dominate the Metal Forging Market
- The steel segment is expected to account for the largest share of above 44.0% of the metal forging market.
- The growth of this segment is attributed to various factors, as steel is renowned for its exceptional strength and durability, making it a preferred material for forging applications.
- Forged steel components exhibit superior mechanical properties, including high tensile strength, toughness, and resistance to wear and fatigue.
- These properties make forged steel parts ideal for critical applications in industries such as automotive, aerospace, oil and gas, construction, and power generation.
- Moreover, steel forging offers tight control over the metallurgical properties of the finished parts, ensuring consistent quality and performance.
- The forging process refines the grain structure of the steel, eliminating defects and enhancing the mechanical properties of the material.
- This results in forged steel components with superior strength, toughness, and dimensional accuracy, meeting the stringent quality standards of industries such as automotive and aerospace.
- However, the aluminum segment is projected to register the highest CAGR during the forecast period.
- The growth of this segment can be attributed to various factors, as aluminum has a low density and lightweight characteristics, making it an ideal material for applications where weight reduction is critical.
- Forged aluminum components offer high strength-to-weight ratios, making them suitable for aerospace, automotive, and transportation industries seeking to improve fuel efficiency and performance.
- Moreover, aluminum exhibits excellent thermal and electrical conductivity properties, making it a preferred choice for heat transfer and electrical applications.
- Forged aluminum heat sinks, electrical connectors, and transmission components benefit from these properties, ensuring efficient energy transfer and thermal management in various electronic and automotive systems.
By End-use Industry
- The Automotive Segment to Dominate the Metal Forging Market
- The automotive segment is expected to account for the largest share of above 66.0% of the metal forging market.
- Metal forging is widely used in the production of critical engine components such as crankshafts, connecting rods, camshafts, and pistons.
- These components undergo high levels of stress and must withstand extreme operating conditions.
- Forged steel or aluminum alloys offer the necessary strength, durability, and fatigue resistance required for engine performance and reliability.
- Also, forged steel components are used in the construction of vehicle chassis and structural members to enhance rigidity, crashworthiness, and occupant safety.
- Metal forging is also utilized in the production of wheel hubs, bearings, and other wheel-related components.
- Forged wheel hubs provide the necessary strength and durability to support vehicle loads and withstand dynamic forces during braking, acceleration, and cornering.
- Such factors help to drive the growth of the metal forging market for automotive during the forecast period.
- However, the construction segment is projected to register the highest CAGR during the forecast period.
- Metal forging is utilized in construction for a variety of applications where strength, durability, and precision are paramount.
- Forged steel components are integral to the construction of buildings, bridges, and other infrastructure projects.
- Structural steel forgings such as beams, columns, and girders provide the framework and support necessary to withstand the structural loads and forces imposed by the built environment in which forging ensures the required strength, stiffness, and dimensional accuracy of structural components, contributing to the overall stability and safety of construction projects.
- Additionally, metal forging is used in the manufacture of pile-driving equipment used for foundation construction and deep excavation projects.
- It ensures the durability, impact resistance, and precision alignment of pile driving components to achieve efficient and reliable pile installation in various soil conditions.
- Such factors help to drive the growth of the metal forging market for construction during the forecast period.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of above 51.0% of the metal forging market. The Asia-Pacific region, particularly countries like China, India, Japan, and South Korea, has been experiencing rapid industrialization and infrastructure development. This growth has led to increased demand for forged metal components in sectors such as automotive, construction, aerospace, energy, and manufacturing. Advancements in forging technology, materials, and processes have improved the efficiency, quality, and capabilities of metal forging in the Asia-Pacific region. Automation, robotics, computer numerical control (CNC) machining, and simulation software enhance the productivity, accuracy, and flexibility of forging operations. These technological advancements drive the adoption of metal forging in various industries and support the region's manufacturing competitiveness. Moreover, the market in Asia-Pacific is projected to register the highest CAGR of 8.5% during the forecast period. In 2025, Asia-Pacific to Dominate the Metal Forging Market
Competitive landscape
- August 2024
Apollo Global Management, Inc. (U.S.) acquired the lightweight metals manufacturer Arconic Corporation (U.S.). The company will continue to operate under the Arconic name and brand, and the deal was finalized at USD 4.6 billion.
- February 2022
Bharat Forge (India), a leading auto component player, and its subsidiary, BF Industrial Solutions (India), entered into a definitive agreement to acquire 100% of Coimbatore-based JS Autocast Foundry India. This acquisition will enable Bharat Forge to expand its product portfolio in the industrial sector, customer base, and manufacturing presence in South India.
- Arconic Corporation (U.S.)
- Nippon Steel Corporation · Japan
- Precision Castparts Corp. (U.S.)
- Larsen & Toubro Limited · India
- Bharat Forge Limited · India
- BRÜCK GmbH · Germany
- ELLWOOD Group, Inc. (U.S.)
- Metal Forging Pvt. Ltd. · India
- CELSA Group (Spain) Ovako AB · Sweden
- Lolu Alloys Ltd (U.K.)
- Scot Forge Company (U.S.)
- Alcoa Corporation (U.S.)
- ATI Inc.(U.S.)
Frequently asked questions
The metal forging market is expected to reach $153.9 billion by 2032, at a CAGR of 7.4% from 2025 to 2032.
Cite this report
Meticulous Research. (2024). Metal Forging Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRCHM - 1041196). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/metal-forging-market-5879