Fog Computing Market (2025-2035)
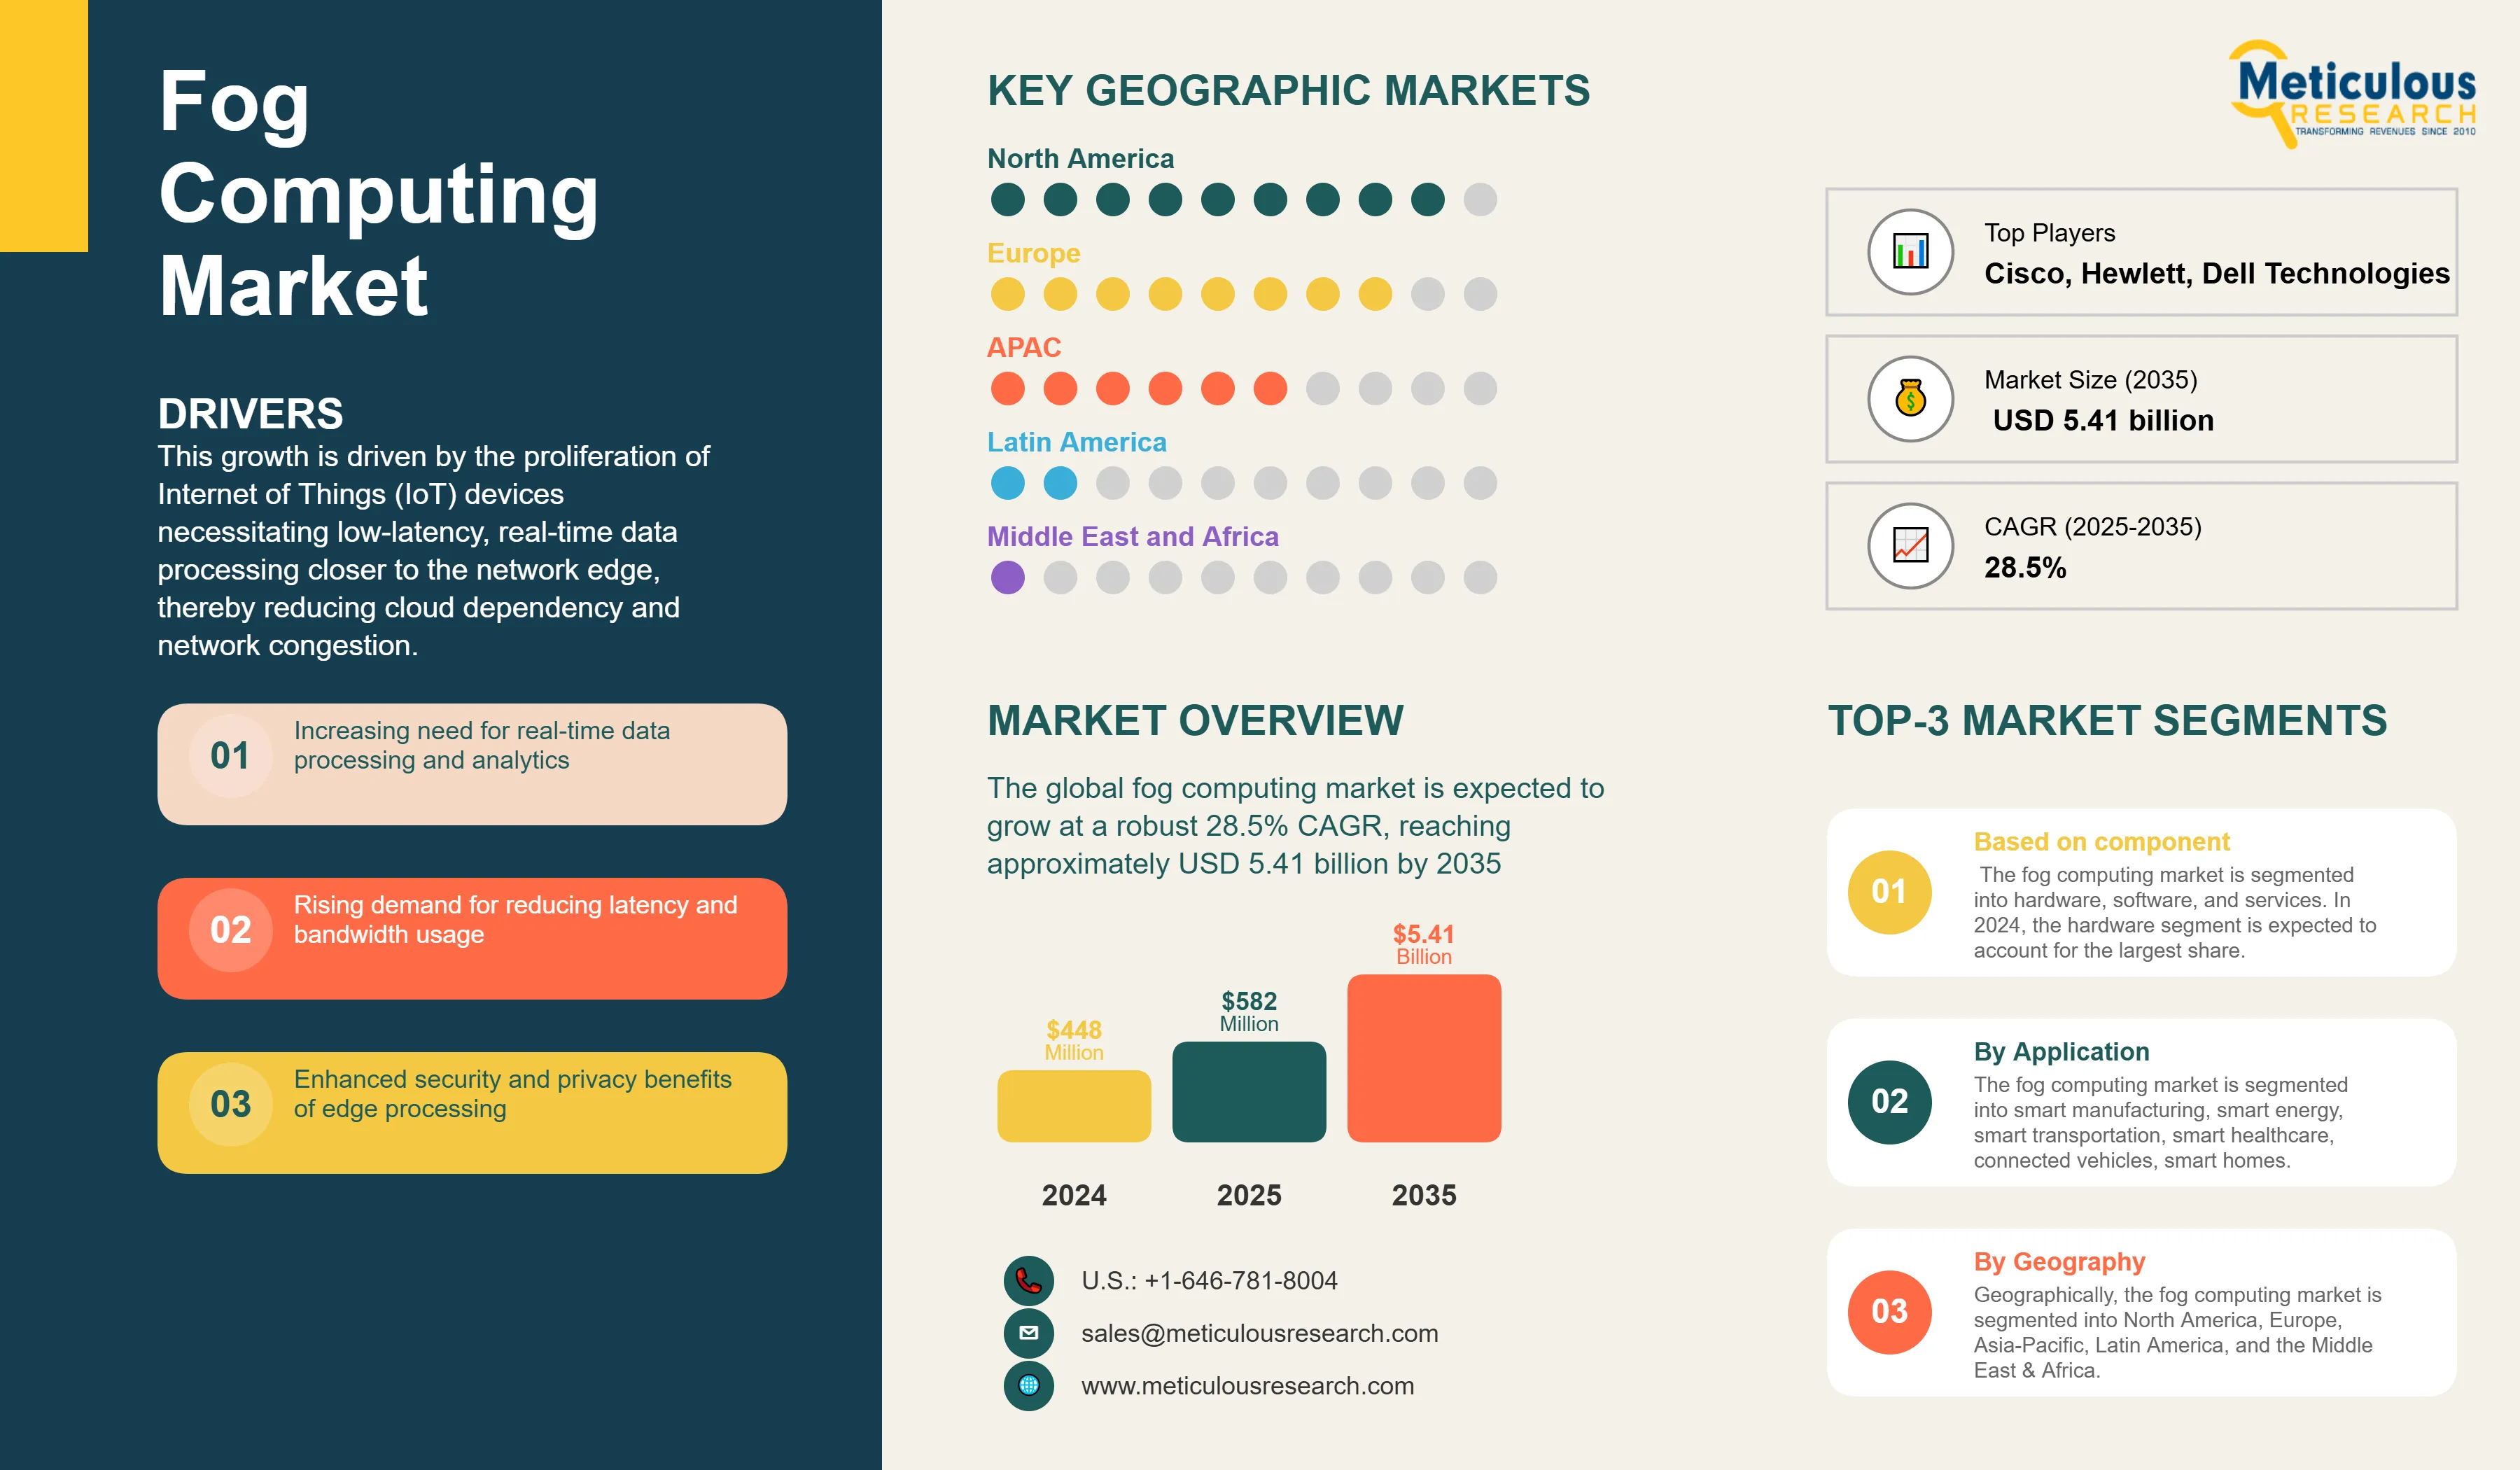
The global fog computing market was valued at USD 448 million in 2024. This market is expected to grow at a robust 28.5% CAGR, reaching USD 5.41 billion by 2035 from USD 582 million in 2025.
- Published
- Aug 2025
- Pages
- 200
- Format
- PDF + Excel
- Report ID
- MRICT - 1041541
- Base year
- 2024
- 2024 · BASELINE
- $448.0M
- 2035
- $5.41B
- CAGR 2025–2035
- 28.5%
2024 baseline · 2025–2035 forecast at 28.5% CAGR · hover a bar for the value
Key highlights
The global fog computing market was valued at USD 448 million in 2024.
This market is expected to grow at a robust 28.5% CAGR, reaching USD 5.41 billion by 2035 from USD 582 million in 2025.
North America dominates the global fog computing market, accounting for more than 35% market share in 2025, owing to its robust IoT infrastructure and early 5G inception.
Asia-Pacific is the fastest-growing region in the fog computing market, with projected growth rate exceeding 30% by 2035.
Germany's robust industrial base and digital innovation positions it to witness substantial growth in the fog computing industry.
Report summary
| Particulars | Details |
|---|---|
| Market size (2025) | USD 582 million |
| Revenue forecast in 2035 | USD 5.41 billion |
| CAGR (2025-2035) | 28.5% |
| Format | PDF, Excel & Cloud Portal · 200 pages |
| Base Year | 2024 |
| Forecast period | 2025 – 2035 |
| Report coverage | Market size and forecast, competitive landscape and benchmarking, country/regional level analysis, key trends, growth drivers and restraints |
| Segments covered | Component (Hardware, Software), Deployment Mode, Application (Security, Smart Manufacturing), Geography |
| Regional scope | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
| Key companies profiled | Cisco Systems; Hewlett Packard Enterprise; IBM; Dell Technologies; Intel Corporation; Huawei Technologies; Microsoft; FogHorn Systems; Zededa; Stratus Technologies; Vapor IO; ClearBlade; Litmus Automation; and NetFoundry. |
| Customization | Comprehensive report customization with purchase. Addition or modification to country, regional & segment scope available |
| Pricing Details | Access customized purchase options to meet your specific research requirements. Explore flexible pricing models |
Report overview
Segments covered: application.
This growth is driven by the proliferation of Internet of Things (IoT) devices necessitating low-latency, real-time data processing closer to the network edge, thereby reducing cloud dependency and network congestion. Moreover, the robust IoT adoption and advanced digital infrastructure, smart city projects, expansion of 5G networks, and increased industrial automation further propels the business growth.
Key developments focus on integrating fog computing with AI capabilities, enhanced security frameworks such as blockchain, and improved fog-to-cloud orchestration. Industry giants including Cisco, IBM, Huawei, and Dell are actively innovating solutions that enable decentralized computing architectures, underscoring fog’s critical role in digital transformation and mission-critical applications across sectors such as healthcare, manufacturing, and autonomous vehicles.
Report infographic
Key Factors Impacting Global Fog Computing Market (2025–2035)
Base CAGR: 28.5%
|
Category |
Key Factor |
Short-Term Impact (2025–2028) |
Long-Term Impact (2029–2035) |
Estimated CAGR Impact |
|
Drivers |
1. Growing IoT Device Proliferation and Demand for Low Latency |
Real-time responsiveness gains |
Sustained demand across verticals |
▲ +5.8% |
|
2. Expansion of 5G Networks and Edge AI Integration |
Faster data transfer, reduced lag |
Automation of edge ecosystems |
▲ +4.5% |
|
|
3. Increasing Adoption in Smart Cities and Industrial Automation |
Pilot-scale deployments |
Autonomous operations and scaling |
▲ +3.9% |
|
|
Restraints |
1. Integration Complexity and Lack of Standardization |
Fragmented edge implementation |
Slower interoperability progress |
▼ −2.1% |
|
2. Security Vulnerabilities at the Edge |
Increased risk exposure |
Persistent need for cybersecurity |
▼ −2.5% |
|
|
Trends |
1. Adoption of hybrid fog-cloud architectures |
Flexible resource allocation |
Integrated edge-cloud infrastructure |
▲ +2.9% |
|
Opportunities |
1. Expansion in smart city and smart manufacturing applications |
Emerging commercial pilots |
Infrastructure-led growth |
▲ +4.1% |
|
2. Integration with 5G and AI technologies |
Enhanced data-driven workflows |
Next-gen intelligent edge solutions |
▲ +3.6% |
|
|
Challenges |
1. Managing complex distributed architectures |
Operational bottlenecks |
Need for standard architecture models |
▼ −1.6% |
Market dynamics
5 factors across 2 forcesGrowing IoT Device Proliferation and Demand for Low Latency
The exponential rise of connected IoT devices projected to exceed 30 billion globally by 2030 according to the International Monetary Fund. It further drives the demand for fog computing as a solution to reduce latency and bandwidth overload on cloud systems. Fog computing caters to these requirements by allowing data processing and lowering the time it requires to transfer data to a centralized cloud. This functionality ensures quick response applications including avoiding accidents with self-driving vehicles or tracking critical health metrics in real time.
Expansion of 5G Networks and Edge AI Integration
The global deployment of 5G technology enables the expansion of fog computing applications by providing ultra-low latency and enhanced bandwidth. Edge AI that integrates into fog nodes, facilitates advanced data processing, predictive maintenance, and security analytics at the periphery. Also, the convergence of 5G and AI is set to expedite digital transformations by facilitating the adoption of fog computing, that is further expected to foster the development of intelligent factories, connected vehicles, and real-time health monitoring.
Increasing Adoption in Smart Cities and Industrial Automation
Smart city initiatives globally increasingly rely on fog computing to support traffic management, public safety, and energy efficiency through real-time processing of sensor data. Similarly, manufacturers adopt fog-enabled solutions for predictive maintenance and operational efficiency. For instance, the U.S. government’s Smart Cities initiative leverages fog computing to improve urban environments by transforming data closer to its source, allowing rapid response times and enhanced efficiency. Thus, the rapid urbanization and increasing use in smart cities, anchors this growth trend, thereby promoting business potential.
Table of contents
12 chapters · 139 sections · 200 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2035) |
|---|---|---|
| Other segments | Software | — |
| By Application | Building and home automation | — |
Other segments
- Cost-Saving Fog Software Boosts Efficiency by Reducing Data Transmission and Bandwidth Needs
- The software segment held the largest share and dominated the overall fog computing market.
- By reducing the necessity for extensive data transmission to centralized clouds, fog computing software enhances operational efficiency and reduces costs.
- Businesses minimize bandwidth consumption and associated expenses by processing data locally.
- This localized processing reduces the necessity for high bandwidth and lowers operational costs.
- Fog computing software, which offers operational efficiencies and cost-saving benefits, is a cost-effective solution for businesses that are seeking to optimize their IT expenditures.
By Application
- Fog Computing Catalyzes Smart City Advancements in Building Automation
- Building and home automation segment accounted for substantial market share in 2025 and is set to grow at 27.2% CAGR in the coming years.
- Governments globally are investing billions to deploy sensor networks and real-time analytics platforms using fog architectures.
- For example, several U.S. and European cities have reported up to 20% reductions in traffic congestion and energy consumption attributable to fog-enabled IoT systems.
- Additionally, intelligent traffic management systems, powered by fog computing and IoT also led to significant energy savings.
- By optimizing traffic flow and reducing idling time, these systems highlighted the potential to lower fuel consumption and associated emissions, with studies demonstrating reductions in energy consumption of up to 20% in certain cases.
- Thus, the increasing emergence of smart city projects and robust potential showcased by fog computing in optimizing resources is set to proliferate the market growth.
Geographic analysis
North America
Largest shareNorth America dominates the global fog computing market, accounting for more than 35% market share in 2025, owing to its robust IoT infrastructure and early 5G inception. The region is characterized by advanced digital infrastructure, strong demand for low-latency, and localized data processing. Fog computing has now become a crucial component of the digital transformation strategy in the country as organizations in key sectors are adopting fog computing models. For example, in October 2024, Hewlett Packard Enterprise (HPE), employed its Edgeline EL8000 Converged Edge System at a aerospace engineering factory in the U.S. The fog-enabled platform was implemented throughout the production lines to analyze data from high-precision sensors in real time without transferring it to the cloud. This enabled more rapid corrective action, reduced the duration of part inspections, and improved quality control. According to HPE, this deployment exemplified the utilization of fog computing by American manufacturers to enhance visibility, speed, and control over critical peripheral operations. Also, the presence of key market players, increasing emphasis on fog security protocols, bolsters North America’s position in the fog computing market. In 2024, the U.S. maintained a leading position and dominated the global fog computing industry. Organizations are placing a higher priority on safeguarding sensitive information in response to the proliferation of cyber threats and data intrusions. Cybercrime impacted more than 53 million U.S. citizens during the first half of 2022. By processing data locally, fog computing minimizes the necessity of transmitting it to centralized cloud servers, thereby reducing the risk of data breaches and providing enhanced security. This method guarantees the security of sensitive information and the adherence to rigorous data protection regulations. Additionally, presence of major market participants such as Cisco, HPE, Dell Technologies, and Intel that invest heavily in research & development, to advance fog computing technologies further boosts the innovation pipeline, offering immense business avenues in the coming years. This innovative ecosystem supported by robust venture capital and public-private partnerships, is advancing fog computing into the mainstream of business operations in the U.S. North America: Leads Fog Computing Market, Driven by Advanced IoT Infrastructure Widespread Industrial Use that Supports Low-Latency Fog Solutions is Driving Regional Growth Large-scale Industrial Fog Adoption Supports the Fog Computing Market Growth in China
Asia-Pacific
Fastest growthAsia-Pacific is the fastest-growing region in the fog computing market, with projected growth rate exceeding 30% by 2035. Supported by emphasis on digital infrastructure, extensive IoT ecosystem, and robust industrial base, Asia Pacific is emerging as a significant force in the fog computing industry. Countries such as China are adopting novel strategies that promotes the adoption of AI, smart cities, 5G, and industrial automation, making fog computing a critical enabler. Particularly in high-density urban areas, intelligent manufacturing centers, and next-generation transportation networks, China requires real-time applications with low latency. By enabling quicker, more localized data processing, fog computing addresses these requirements. Similarly, Japan’s industrial automation and robotics sectors are integrating fog nodes for real-time analytics; While South Korea, with its advanced 5G ecosystem, is deploying fog computing in connected healthcare and mobility solutions to enhance responsiveness and data security. The rapid adoption of smart factories and edge-powered automation in Asia-Pacific region is set to boost regional business growth in the coming years. China dominates the Asia-Pacific fog computing market and accounted for highest market size in 2024. The country is set to witness robust growth in the coming years owing to comprehensive digital infrastructure upgrades and government policies favouring homegrown technology. The necessity of fog computing is further emphasized by China's aspirations to integrate AI and 5G. Further, the government's support for fog computing in China serves to further accelerate its momentum. National initiatives such as Digital China and Made in China 2025 prioritize industrial digitalization and edge-intelligent technologies. Furthermore, major technology providers such as Huawei, Alibaba Cloud, ZTE, and Inspur are advancing key developments in the fog computing industry. For example, Huawei’s EdgeStation enables the processing of large quantities of data locally, thereby enabling real-time video analytics, autonomous vehicle coordination, and crane operation monitoring, all without the need for the central cloud. This deployment is indicative of China's growing dependence on fog computing to modernize infrastructure and facilitate large-scale, real-time, AI-driven operations. Presence of Major Players That Enable Advancements in the Fog Computing Industry
Europe
Germany's robust industrial base and digital innovation positions it to witness substantial growth in the fog computing industry. Fog computing enables localized processing at the network edge, making it lucrative in industries that value operational effectiveness, data privacy, and real-time responsiveness. German firms are actively implementing sensors, robots, and AI-powered systems that rely on fast, decentralized computing. For example, in March 2025, Bosch Rexroth announced a fog-enabled iteration of ctrlX AUTOMATION platform, implemented at selected German production facilities. With the inclusion of fog nodes and edge controllers, shop-floor devices are now able to process and share information without depending on the cloud. Furthermore, the strong integration of industrial IoT (IIoT) technologies across industries like automotive, machinery, logistics, and energy also contribute to Germany's market dominance. Germany Leads European Fog Adoption Through Focus on Privacy, Industrial Automation, And Compliance
Competitive landscape
The fog computing market is characterized by competitive innovation among established IT and networking firms and emerging edge specialists. Cisco Systems has prominent industry position with its ‘Edge Fog Fabric’ technology driven by AI-powered analytics to cater to latency and bandwidth issues. Similarly, usva.io, a decentralized fog computing platform employs underutilized computing resources. This platform improves sustainability by lowering dependence on centralized data silos and optimizes operational costs by channelizing computing services closer to the edge. Other notable competitors include Huawei, Dell Technologies, FogHorn Systems, and Oracle, each advancing fog-to-cloud integration, security features, and scalable management. Collaborations and partnerships further accelerate adoption across sectors demanding real-time, secure data processing.
- April 2025
Cisco launched an improvised Edge Fog Fabric platform incorporating AI-powered analytics to refine real-time processing capabilities and network resource optimization, simplifying complex industrial latency issues and assisting smart manufacturing.
- December 2024
Fogwing introduced its industrial IoT platform incorporating edge computing with machine learning functionalities. This platform channelizes real-time data processing at the edge, enabling sectors such as manufacturing, automotive, and pharmaceuticals to drive decision making. It aids in lowering the latency and bandwidth usage, leading to enhanced operational efficiency.
- Cisco Systems
- Hewlett Packard Enterprise
- IBM
- Dell Technologies
- Intel Corporation
- Huawei Technologies
- Microsoft
- FogHorn Systems
- Zededa
- Stratus Technologies
- Vapor IO
- ClearBlade
- Litmus Automation
- NetFoundry
Frequently asked questions
The Fog Computing Market size is estimated to be USD 582 million in 2025 and grow at a CAGR of 28.5% to reach USD XX billion by 2035.
Cite this report
Meticulous Research. (2025). Fog Computing Market - Global Opportunity Analysis and Industry Forecast (2025–2035) (Report No. MRICT - 1041541). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/fog-computing-market-6224