Data Center Interconnect (DCI) Market (2026-2036)
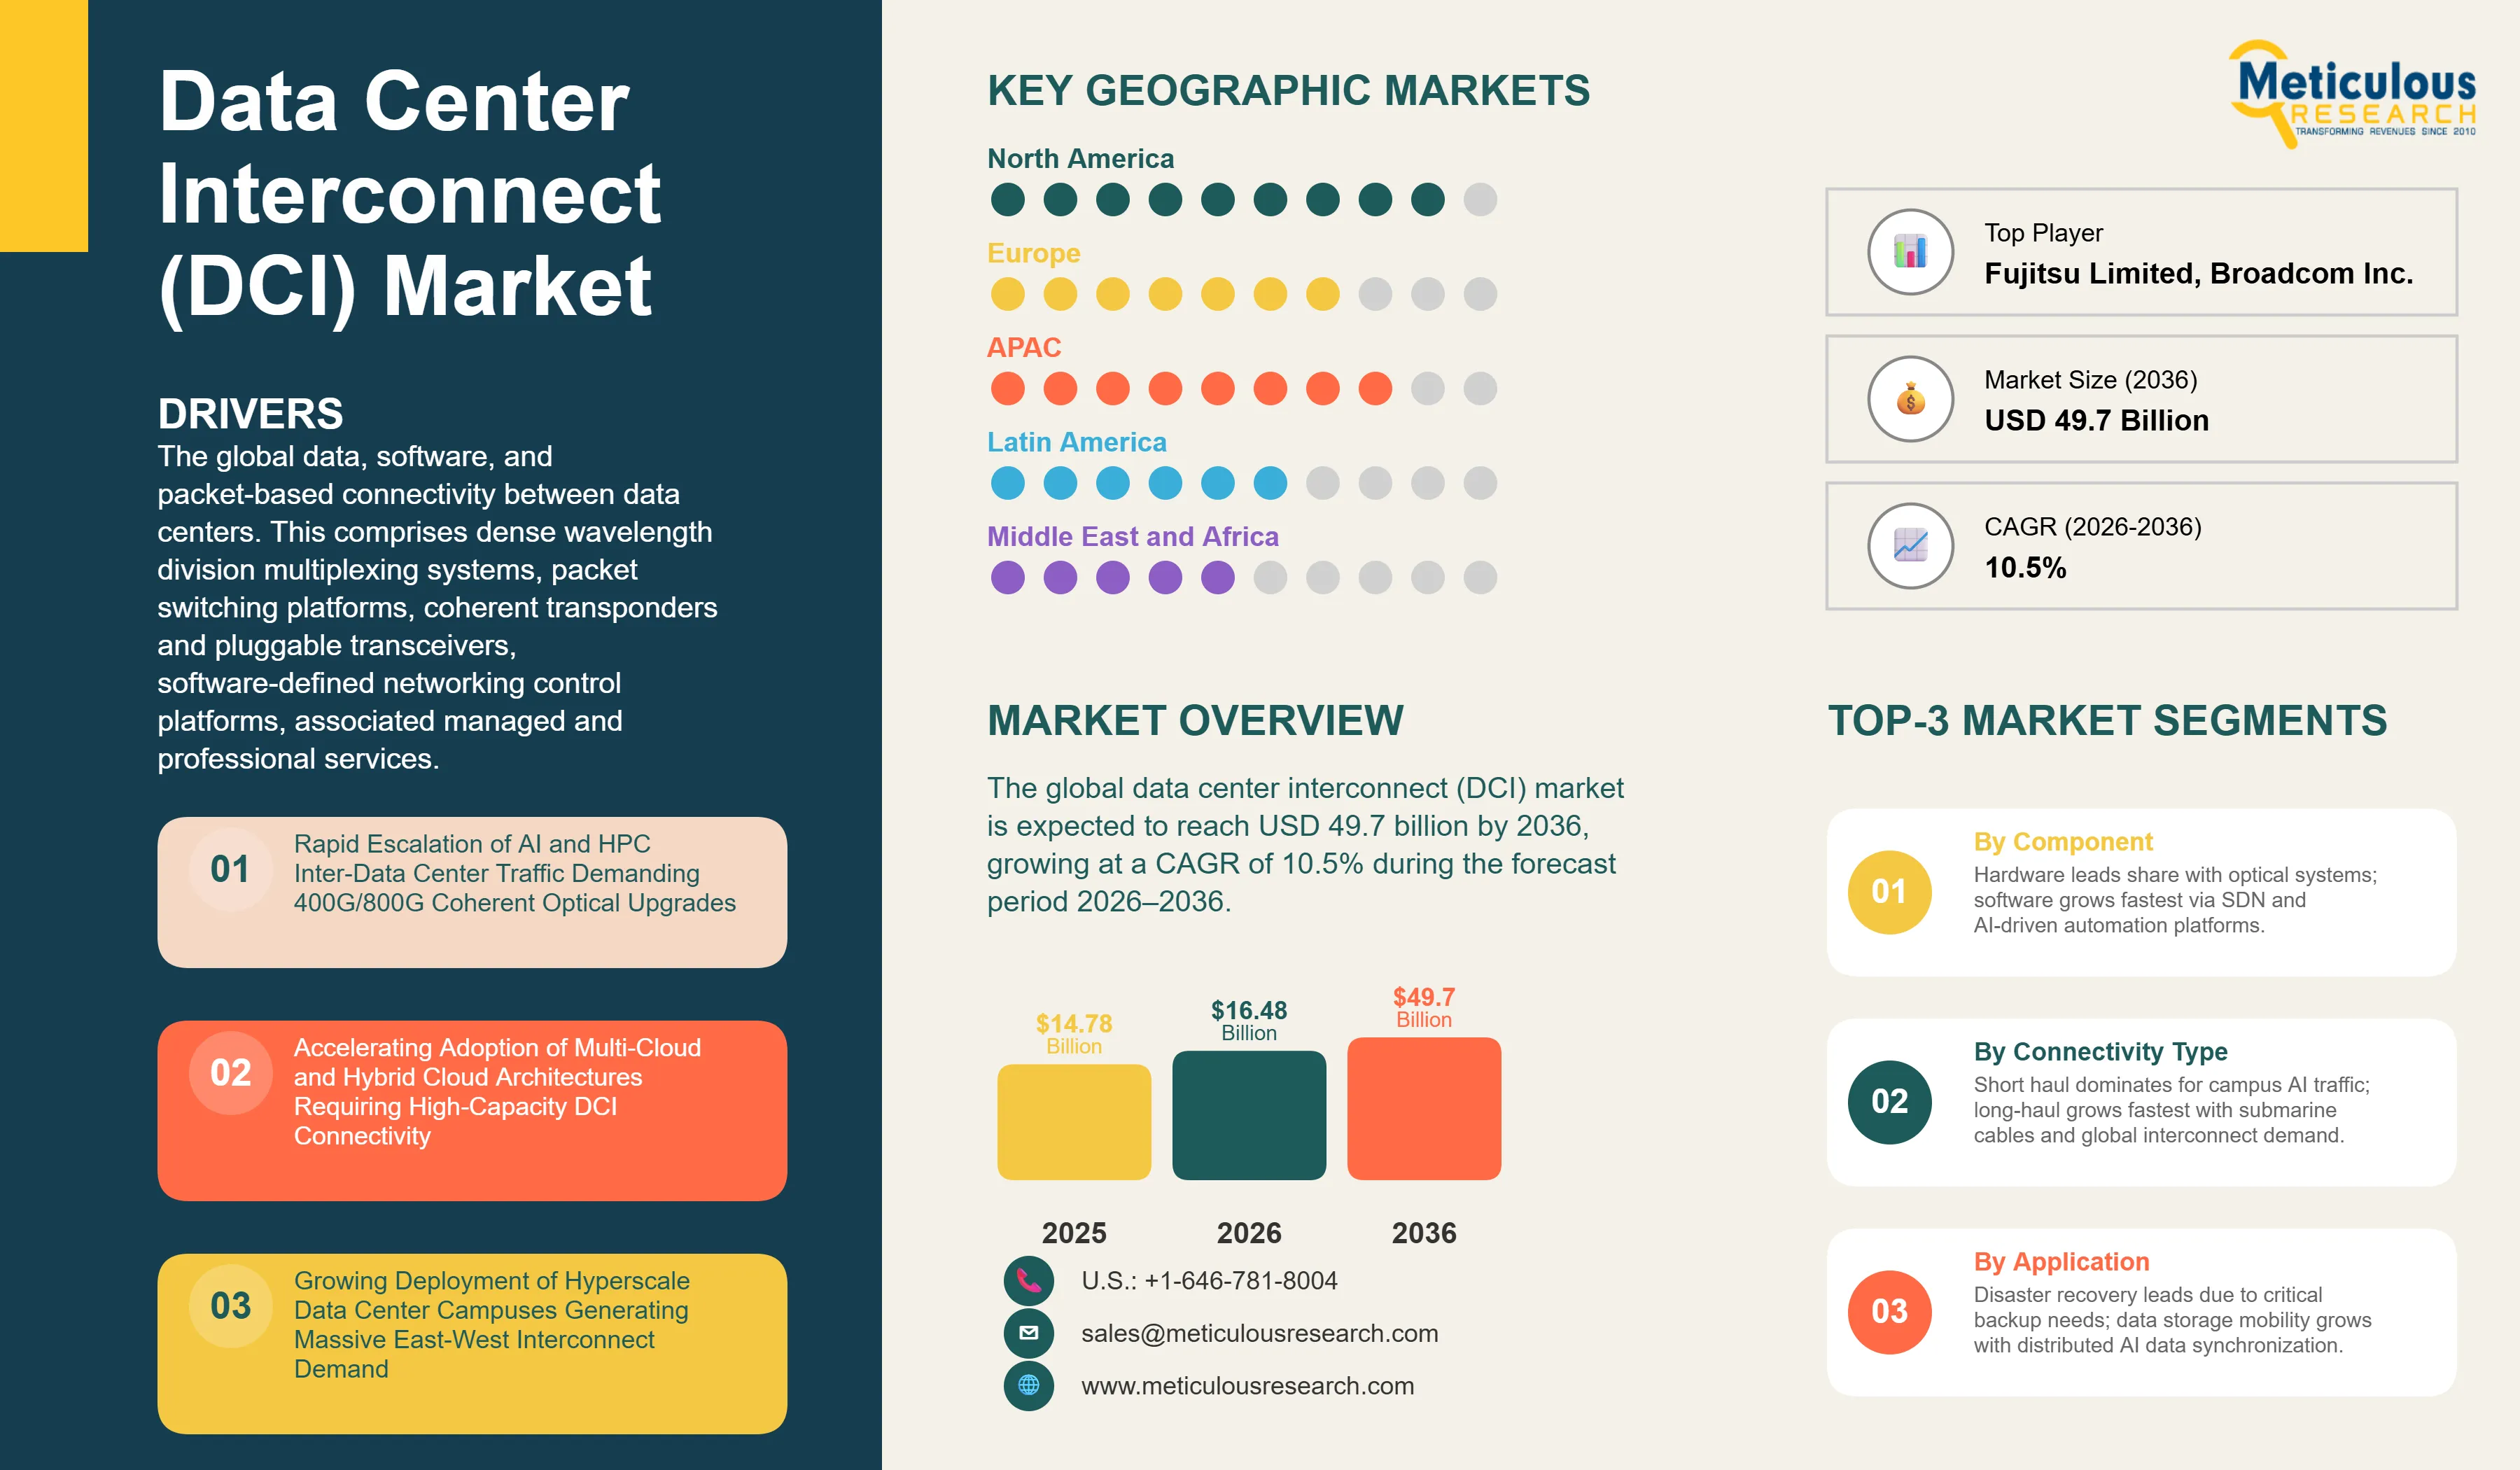
The global data center interconnect (DCI) market was valued at USD 14.78 billion in 2025. This market is expected to reach USD 49.7 billion by 2036 from an estimated USD 16.48 billion in 2026, growing at a CAGR of 10.5% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MR-1862
- Base year
- 2025
- 2025 · BASELINE
- $14.78B
- 2036
- $49.70B
- CAGR 2026–2036
- 10.5%
2025 baseline · 2026–2036 forecast at 10.5% CAGR · hover a bar for the value
Key highlights
The global data center interconnect (DCI) market is projected to reach USD 49.7 billion by 2036.
The market is expected to grow at a CAGR of 10.5% during the forecast period 2026–2036.
The global DCI market was valued at USD 14.78 billion in 2025 and is estimated to reach USD 16.48 billion in 2026.
North America is expected to dominate the global DCI market with the largest market share in 2026, driven by the highest concentration of hyperscale cloud providers globally, the most advanced coherent optical networking infrastructure, and the leading role of U.S.-based technology companies in driving 400G/800G DCI technology adoption.
Asia Pacific is projected to witness the fastest growth during the forecast period, driven by the massive expansion of data center capacity across China, Japan, India, South Korea, and Southeast Asia, government-led digital infrastructure investments, and the accelerating adoption of AI workloads requiring high-bandwidth inter-data center connectivity.
By component, the hardware segment is expected to hold the largest market share of approximately 45–50% in 2026.
By component, the software segment is projected to register the highest CAGR during the forecast period, driven by the rapid adoption of software-defined networking and AI-driven DCI control platforms that automate bandwidth provisioning, latency steering, and failover management.
By connectivity type, the short-haul segment is expected to account for the largest share of the global DCI market in 2026.
By connectivity type, the long-haul segment is projected to grow at the highest CAGR during the forecast period, driven by the growing demand for transcontinental AI training cluster connectivity and the expansion of submarine cable infrastructure.
By application, the disaster recovery and business continuity segment is expected to account for the largest share in 2026, while the data storage mobility segment is projected to register the highest CAGR during the forecast period.
By end-user industry, communication service providers are expected to account for the largest share in 2026, while internet content and carrier-neutral providers are projected to register the highest CAGR during the forecast period.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 49.7 Billion |
| Market Size in 2026 | USD 16.48 Billion |
| Market Size in 2025 | USD 14.78 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 10.5% |
| Format | PDF, Excel & Cloud Portal · 280 pages |
| Dominating Component | Hardware |
| Fastest Growing Component | Software |
| Dominating Connectivity Type | Short-Haul (< 10 km) |
| Fastest Growing Connectivity Type | Long-Haul (> 80 km) |
| Dominating Application | Disaster Recovery & Business Continuity |
| Fastest Growing Application | Data Storage Mobility |
| Dominating End-User Industry | Communication Service Providers |
| Fastest Growing End-User Industry | Internet Content & Carrier-Neutral Providers |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: component, connectivity type, application, end-user industry.
The global data center interconnect (DCI) market covers the hardware, software, and services used to enable high-capacity, low-latency optical and packet-based connectivity between data centers. This comprises dense wavelength division multiplexing systems, optical transport network equipment, packet switching platforms, coherent transponders and pluggable transceivers, reconfigurable optical add/drop multiplexers, software-defined networking control platforms, and associated managed and professional services.
DCI infrastructure functions as the backbone of modern distributed computing architectures, enabling disaster recovery, workload migration, storage synchronization, and large-scale AI training cluster connectivity. These capabilities represent a key demand driver shaping the market during the 2026–2036 forecast period.
The growth of the global data center interconnect (DCI) market is primarily driven by the rapid increase in AI and machine learning workload-driven inter-data center traffic, which requires ultra-high bandwidth and low-latency connectivity. The ongoing transition from 100G to 400G and 800G coherent optical technologies across hyperscale and colocation environments is further accelerating demand. In addition, the growing adoption of multi-cloud and hybrid cloud architectures is increasing the need for flexible, high-capacity interconnect solutions between geographically distributed data center assets.
However, the market faces certain constraints. Upgrading legacy interconnect infrastructure to support 400G and 800G coherent optical platforms requires significant capital investment. At the same time, interoperability challenges across multi-vendor DCI environments add operational complexity, particularly for large-scale deployments.
Despite these challenges, several growth opportunities are emerging. The development of co-packaged optics and 1.6 Tbps coherent transport technologies is expected to enable next-generation bandwidth scaling. The expansion of edge data centers is also driving demand for metro DCI solutions that support low-latency edge-to-core connectivity. In parallel, the increasing adoption of software-defined networking and AI-driven automation is improving network efficiency and enabling dynamic capacity management.
A key trend shaping the market is the expansion of submarine cable infrastructure, which enhances global interconnect capacity and supports cross-border data flows. Additionally, the growing adoption of open optical networking architectures is enabling greater vendor interoperability and cost optimization across DCI deployments.
Report infographic
Market dynamics
3 factors across 1 forceRapid Transition to 400G/800G and Emerging 1.6T Coherent Optical Technologies
The migration from 100G to 400G, 800G, and emerging 1.6T coherent‑optical transport is the key technology trend in the global data center interconnect (DCI) market. This transition is driven by the surge in AI‑related traffic in hyperscale data center networks, where GPU clusters require aggregate bandwidths of hundreds of terabits per second for distributed model training and inference.
The shift is generating a structural upgrade cycle across metro, regional, and long‑haul DCI infrastructure as operators exhaust the capacity of legacy optical systems. Industry leaders such as Ciena, Infinera, Nokia, and Huawei are competing primarily on spectral efficiency and coherent‑DSP performance, while co‑packaged optics are moving from laboratory demonstrations toward early commercial deployment in hyperscale AI‑focused data centers.
Growing Adoption of Software-Defined Networking for Intelligent DCI Automation
The integration of software‑defined networking (SDN) and AI‑driven control platforms into DCI infrastructure is a significant trend reshaping the global market. Traditional DCI management required manual configuration of optical transport paths, bandwidth allocations, and failover policies, which are increasingly inadequate for the dynamic, multi‑site, multi‑cloud environments operated by modern hyperscale and enterprise organizations.
SDN‑enabled DCI control platforms provide real‑time telemetry, automated bandwidth provisioning, intelligent traffic steering, and self‑healing failover capabilities, which reduce operational costs and improve network resilience. The software segment of the DCI market is projected to post a CAGR of around 12-13% through the forecast period, as controllers automate bandwidth pooling, latency‑based steering, and failover at scale across increasingly complex, multi‑vendor DCI environments.
AI-Optimized DCI Infrastructure as a Distinct and Fast-Growing Market Category
The increasing demand for purpose-built, AI-optimized DCI infrastructure, engineered for all-to-all east-west traffic patterns of distributed AI training clusters, rather than traditional north-south client-server traffic, is emerging as the fastest-growing category within the global DCI market. This shift indicates a structural change in data center networking requirements, driven by the scale, intensity, and communication patterns of AI workloads.
AI training environments requiring 400 Gbps to 800 Gbps bandwidth per connection are driving the adoption of coherent optical technologies, photonic switching architectures, and software-defined control platforms. These solutions enable the orchestration of thousands of simultaneous optical paths with sub-microsecond latency, ensuring efficient workload synchronization across geographically distributed GPU clusters.
As a result, data center operators are increasingly investing in high-capacity, low-latency DCI architectures designed specifically for AI cluster interconnectivity. This transition is driving a new wave of infrastructure upgrades and greenfield deployments, positioning AI-optimized DCI as a key revenue growth segment within the broader DCI market over the forecast period.
Table of contents
12 chapters · 127 sections · 280 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Hardware | Software |
| By Connectivity Type | Short-Haul | Long-haul |
| By Application | Disaster Recovery & Business Continuity | Data storage mobility |
| By End-user Industry | Communication Service Providers | Internet content and carrier-neutral providers |
By Component
- The Hardware Segment to Dominate the Global DCI Market
- The hardware segment is expected to account for the largest share of the global DCI market.
- The large share of this segment is attributed to the high capital expenditure cycle underway across hyperscale, colocation, and communication service provider networks as operators procure DWDM optical transport systems, OTN equipment, and packet switching platforms to upgrade legacy 100G interconnect infrastructure to 400G and 800G coherent optical platforms.
- The hardware segment covers DWDM systems, OTN switching equipment, coherent transponders and pluggable transceivers, reconfigurable optical add/drop multiplexers, and packet switching and routing platforms, all of which are in active large-volume procurement across global DCI deployments.
- However, the software segment is poised to grow at the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the growing adoption of software-defined networking and control platforms that automate complex DCI operations at scale, the growing deployment of AI-driven network analytics and predictive maintenance platforms, and the increasing adoption of network functions virtualization, enabling cloud-native, on-demand provisioning of DCI services.
By Connectivity Type
- The Short-Haul Segment to Hold the Largest Share
- The short-haul segment is expected to account for the largest share of the global DCI market.
- This dominance is driven by the need for dense, high-bandwidth interconnects to support the surge in east-west AI training traffic within campus-scale hyperscale environments.
- Multiple AI clusters distributed across buildings within the same campus require terabit-scale optical connectivity, which is efficiently enabled by short-haul DCI infrastructure.
- However, the long-haul segment is poised to register the highest CAGR during the forecast period.
- This growth is driven by increasing demand for interconnecting geographically distributed AI campuses, as hyperscalers expand deployments to access power availability and renewable energy sources.
- In addition, the ongoing expansion of submarine cable infrastructure linking major data center hubs is further driving demand for long-haul coherent optical transport at 400G and 800G data rates.
By Application
- The Disaster Recovery & Business Continuity Segment to Hold the Largest Share
- The disaster recovery and business continuity segment is expected to account for the largest share of the global DCI market.
- This is driven by the non-discretionary nature of disaster recovery investments, which are mandated by regulatory requirements and enterprise continuity policies across industries.
- In addition, synchronous data replication between geographically separated primary and backup sites requires high-bandwidth, low-latency DCI connectivity, further driving the demand.
- However, the data storage mobility segment is poised to register the highest CAGR during the forecast period.
- This growth is driven by the increasing adoption of distributed AI training architectures, which require real-time synchronization of large datasets across multiple locations.
- The shift toward active-active multi-site storage environments is also driving demand for persistent, low-latency interconnect solutions to enable seamless data movement across data centers.
By End-user Industry
- Communication Service Providers to Hold the Largest Share
- The communication service providers segment is expected to account for the largest share of the global DCI market.
- This is driven by the role of telecom carriers in owning and operating the underlying optical transport infrastructure that supports all categories of DCI connectivity, as well as the large-scale hardware procurement required to serve enterprise and hyperscale customer demand.
- However, the internet content and carrier-neutral providers segment is projected to grow at the highest CAGR from 2026 to 2036.
- This growth is driven by aggressive DCI capacity expansion by hyperscale cloud providers such as Amazon Web Services, Microsoft Corporation, Alphabet Inc., and Meta Platforms, Inc., which are investing heavily in proprietary optical transport infrastructure to support AI workload distribution across geographically distributed data center campuses.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global DCI market. The largest share of this region is mainly due to the highest global concentration of hyperscale cloud‑provider data center deployments and AI training infrastructure, the most advanced coherent‑optical networking ecosystem anchored by Ciena, Cisco, Arista, Lumentum, and Marvell, and the largest DCI capital‑expenditure (capex) budgets deployed by Amazon, Microsoft, Google, and Meta in support of their AI‑infrastructure expansion programs.
Asia-Pacific
Fastest growthHowever, the Asia Pacific DCI market is expected to grow at the fastest CAGR during the forecast period. The region’s rapid growth is driven by the massive expansion of data center capacity across China, Japan, India, South Korea, and Southeast Asia, the increasing deployment of AI‑oriented data center campuses requiring high‑bandwidth short‑haul and metro DCI infrastructure, and significant investment in submarine‑cable infrastructure connecting Asia Pacific data center hubs with North America and Europe. China’s domestic AI data center expansion, led by Huawei, Alibaba Cloud, Tencent Cloud, and Baidu, is generating substantial DCI hardware procurement demand addressed primarily by domestic vendors, while India, Japan, and Singapore are attracting significant hyperscale DCI investment from global cloud providers, further driving Asia Pacific’s position as the fastest‑growing DCI region.
Competitive landscape
- Ciena Corporation (U.S.)
- Cisco Systems, Inc. (U.S.)
- Nokia Corporation · Finland
- Huawei Technologies Co., Ltd. · China
- Juniper Networks, Inc. (U.S.)
- Infinera Corporation (U.S.)
- Arista Networks, Inc. (U.S.)
- Ribbon Communications Inc. (U.S.)
- Fujitsu Limited · Japan
- ZTE Corporation · China
- Lumentum Holdings Inc. (U.S.)
- Marvell Technology, Inc. (U.S.)
- Coherent Corp. (U.S.)
- Corning Incorporated (U.S.)
- Broadcom Inc. (U.S.)
Frequently asked questions
The global DCI market is expected to reach USD 49.7 billion by 2036 from an estimated USD 16.48 billion in 2026, at a CAGR of 10.5% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Data Center Interconnect (DCI) Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MR-1862). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/data-center-interconnect-market-6545