Containerized Data Center Market (2026-2036)
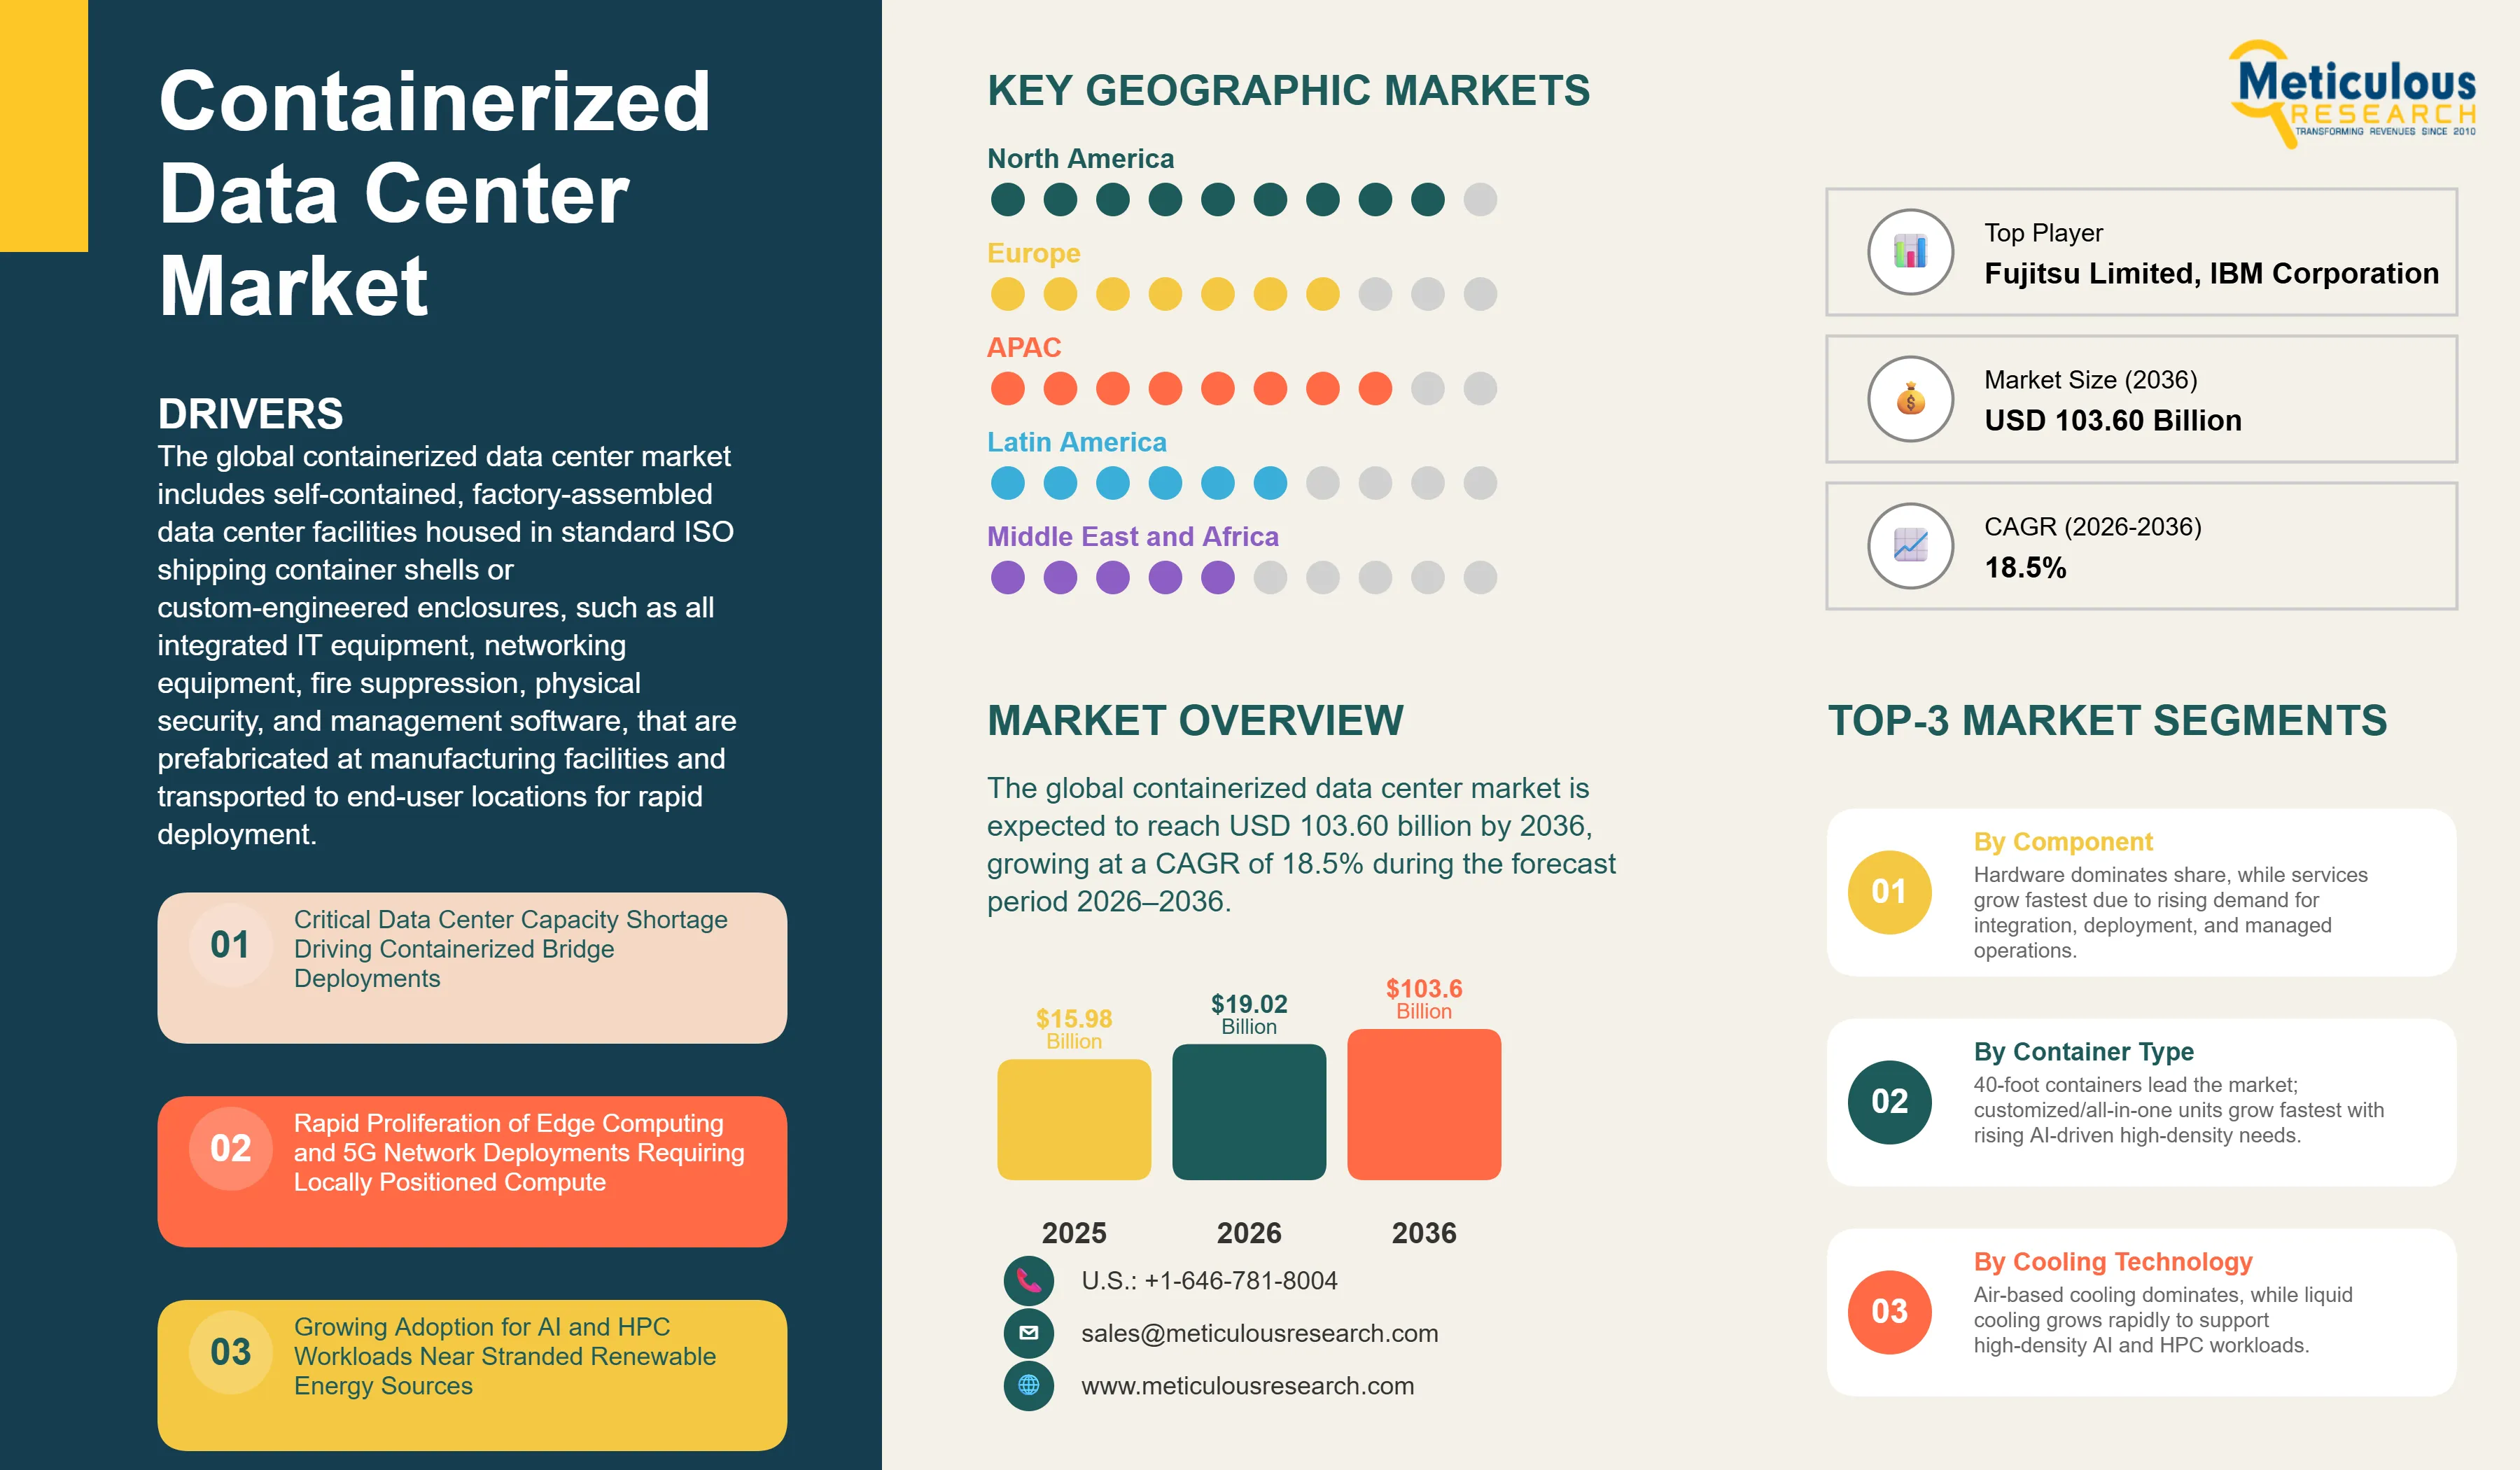
The global containerized data center market was valued at USD 15.98 billion in 2025. This market is expected to reach USD 103.60 billion by 2036 from an estimated USD 19.02 billion in 2026, growing at a CAGR of 18.5% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 280
- Format
- PDF + Excel
- Report ID
- MR-1859
- Base year
- 2025
- 2025 · BASELINE
- $15.98B
- 2036
- $103.6B
- CAGR 2026–2036
- 18.5%
2025 baseline · 2026–2036 forecast at 18.5% CAGR · hover a bar for the value
Key highlights
The global containerized data center market is projected to reach USD 103.6 billion by 2036.
The market is expected to grow at a CAGR of 18.5% during the forecast period 2026–2036.
The global containerized data center market was valued at USD 15.98 billion in 2025 and is estimated to reach USD 19.02 billion in 2026.
North America is expected to dominate the global containerized data center market with the largest market share in 2026, driven by the highest density of hyperscale operators deploying containerized units as bridge capacity for AI campus buildouts and the leading role of U.S.-based cloud providers as primary drivers of containerized data center procurement.
Asia Pacific is projected to witness the fastest growth during the forecast period, driven by massive digital infrastructure expansion across China, India, Japan, Singapore, and Southeast Asia, aggressive 5G network densification programs, and India's data-localization framework driving sovereign cloud deployment through portable modular solutions.
By component, the hardware segment is expected to hold the largest market share in 2026.
By component, the services segment is projected to register the highest CAGR during the forecast period, driven by growing demand for integration, installation, managed operations, and maintenance services as containerized deployments become more technically complex with AI-grade configurations.
By container type, the 40-foot segment is expected to account for the largest share of the global containerized data center market in 2026.
By container type, the customized/all-in-one segment is projected to register the highest CAGR during the forecast period, driven by growing requirements for bespoke thermal envelopes and direct-to-chip liquid cooling manifolds for AI and HPC workloads.
By cooling technology, the air-based cooling segment is expected to account for the largest share in 2026, while the liquid-based cooling segment is projected to register the highest CAGR during the forecast period.
By deployment location, the core/campus segment is expected to account for the largest share in 2026, while the edge/micro segment is projected to register the highest CAGR during the forecast period.
By end use, the BFSI segment is expected to account for the largest share of the market in 2026, while the healthcare segment is projected to register the highest CAGR.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 103.6 Billion |
| Market Size in 2026 | USD 19.02 Billion |
| Market Size in 2025 | USD 15.98 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 18.5% |
| Format | PDF, Excel & Cloud Portal · 280 pages |
| Dominating Component | Hardware |
| Fastest Growing Component | Services |
| Dominating Container Type | 40-Foot |
| Fastest Growing Container Type | Customized/All-in-One |
| Dominating Cooling Technology | Air-Based Cooling |
| Fastest Growing Cooling Technology | Liquid-Based Cooling |
| Dominating Deployment Location | Core/Campus |
| Fastest Growing Deployment Location | Edge/Micro |
| Dominating End Use | BFSI |
| Fastest Growing End Use | Healthcare |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: component, container type, cooling technology, deployment location, organization size, end use.
The global containerized data center market includes self-contained, factory-assembled data center facilities housed in standard ISO shipping container shells or custom-engineered enclosures, such as all integrated IT equipment, cooling systems, power infrastructure, networking equipment, fire suppression, physical security, and management software, that are prefabricated at manufacturing facilities and transported to end-user locations for rapid deployment. These solutions serve as complete, standalone data centers that can be operational within 8 to 12 weeks of order placement, compared to 18 to 36 months for equivalent greenfield brick-and-mortar construction, making them critical for organizations facing time-sensitive capacity requirements, land and permitting constraints, remote location deployments, or regulatory data localization mandates.
The growth of the containerized data center market is primarily driven by the shortage of traditional greenfield data center capacity. Multi-year grid interconnection delays and permitting backlogs have constrained new builds, compelling hyperscale operators and cloud providers to deploy containerized modular units as interim or bridge capacity for AI campus expansions. In parallel, the rapid proliferation of edge computing and 5G networks is increasing demand for locally deployable, scalable infrastructure. The adoption of containerized data centers is also rising for AI and HPC workloads in remote locations, particularly near stranded renewable energy sources.
However, the containerized data center market faces certain constraints. Standard containerized configurations typically offer lower rack power density compared to purpose-built facilities, limiting their suitability for ultra-high-density workloads. In addition, integration with existing IT and facility infrastructure can be complex, while premium AI-ready containerized deployments involve relatively high upfront costs, particularly for advanced cooling and power systems.
Despite these challenges, several growth opportunities are emerging in the overall containerized data center market. Governments in emerging markets are increasingly adopting containerized solutions to support sovereign AI cloud deployments and meet data localization requirements. The defense sector also presents a strong opportunity, driven by demand for ruggedized, portable data center solutions. Furthermore, the emergence of White-Space-as-a-Service and leasing models is expanding adoption among mid-sized enterprises by reducing upfront capital investment barriers.
A key trend shaping the containerized data center market is the transition toward liquid-cooled containerized data center configurations. These systems are designed to support next-generation AI GPU workloads with significantly higher rack power densities, enabling containerized solutions to address more advanced and compute-intensive use cases over the forecast period.
Report infographic
Market dynamics
3 factors across 1 forceAI-Ready Liquid-Cooled Containerized Configurations Becoming a Distinct Product Category
The development of containerized data center formats specifically engineered for AI GPU clusters is creating a distinct and rapidly growing premium product category within the broader containerized data center market. These systems incorporate direct-to-chip cooling capable of managing 60 to 120+ kW rack densities, high-voltage DC power distribution architectures, and NVLink-compatible GPU rack formats.
Huawei’s AI‑optimized FusionModule‑style data‑center solutions, Schneider Electric’s EcoStruxure Modular Data Center architecture for AI, and Vertiv’s prefabricated, AI‑optimized containerized solutions are purpose‑built for NVIDIA Blackwell and future‑generation GPU deployments, commanding significantly higher per‑container pricing than standard configurations and serving as a primary revenue‑growth driver within the containerized‑data‑center hardware segment through the forecast period.
Containerized Deployments as Permanent Strategy for Cryptocurrency Mining Facility Conversion
The repurposing of decommissioned cryptocurrency mining facilities in the U.S. into AI compute campuses has emerged as a growing application of containerized data center infrastructure. These sites, characterized by high power density, low building-to-land ratios, and established grid interconnections, are being retrofitted with containerized AI clusters that can be deployed rapidly and at scale within existing electrical capacity, often without significant new construction.
This trend is generating strong demand for containerized AI deployments at facilities previously operated by companies such as Riot Platforms, Inc., Core Scientific, Inc., and Marathon Digital Holdings, Inc. It represents a structural shift in which stranded energy infrastructure assets are being repurposed into high-value AI compute capacity.
Sovereign AI Containerized Deployments in Emerging Markets
The combination of data localization requirements, limited large-scale greenfield data center construction expertise, and the urgency to deploy domestic AI computing capacity is driving governments in emerging markets, particularly across the Middle East, Africa, and Southeast Asia, to adopt containerized data center solutions as a key enabler of sovereign AI cloud infrastructure, rather than relying solely on traditional purpose-built campuses.
Initiatives such as Saudi Arabia HUMAIN AI, the United Arab Emirates AI infrastructure programs, and India IndiaAI Mission are incorporating modular and containerized deployments as part of their rapid AI capacity expansion strategies. These solutions enable significantly faster deployment, typically within 6 to 12 months, compared to the 3–5 year timelines required for conventional data center construction.
Table of contents
14 chapters · 129 sections · 280 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Hardware | Services |
| By Container Type | 40-Foot | Customized/all-in-one |
| By Cooling Technology | Air-Based Cooling | Liquid-based cooling |
| By Deployment | Core/Campus | Edge/micro |
| By End Use | BFSI | Healthcare |
By Component
- The Hardware Segment to Dominate the Global Containerized Data Center Market
- The hardware segment is expected to account for the largest share of the global containerized data center market.
- The large share of this segment is attributed to the capital-intensive nature of containerized data center procurement, in which IT equipment, cooling systems, and power infrastructure represent the majority of total system value.
- IT equipment, such as servers, storage, and networking hardware, constitutes the highest-value hardware sub-segment, followed by cooling systems, which are the rapidly evolving hardware component as liquid cooling integration into containerized formats accelerates.
- However, the services segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing technical complexity of AI-ready containerized data center deployments, which require specialized expertise for liquid cooling commissioning, high-voltage DC power configuration, and NVIDIA Corporation GPU cluster integration.
- In addition, the rising adoption of managed services models is further driving the growth of the overall services market, as vendors increasingly operate and maintain containerized infrastructure on behalf of end users that lack in-house technical capabilities.
By Container Type
- The 40-Foot Segment to Account for the Largest Share
- The 40-foot segment is expected to account for the largest share of the global containerized data center market.
- This dominance is attributed to its optimal balance of capacity, transportability, and total cost of ownership, enabling deployment across a wide range of use cases.
- A 40-foot container provides sufficient internal volume to accommodate approximately 8 to 20 standard server racks along with integrated cooling and power systems, while remaining within standard ISO shipping dimensions that allow efficient transportation via road networks globally.
- However, the customized/all-in-one segment is poised to register the highest CAGR during the forecast period.
- This growth is driven by the increasing demand for bespoke containerized configurations engineered specifically for AI GPU clusters, which require advanced thermal management, high-capacity power distribution, and specialized structural designs that exceed the capabilities of standard 40-foot ISO container formats.
- These customized solutions are designed to support high-density AI workloads and are typically priced at a premium, reflecting their higher level of engineering complexity and application-specific optimization.
By Cooling Technology
- The Air-Based Cooling Segment to Hold the Largest Share
- The air-based cooling segment is expected to account for the largest share of the global containerized data center market.
- This dominance reflects the large installed base of air-cooled containerized units deployed for conventional server workloads, as well as the lower upfront cost and operational simplicity associated with air-based systems.
- However, the liquid-based cooling segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing deployment of AI GPU clusters in containerized environments, which require advanced cooling solutions to manage rack densities exceeding 60 kW, levels that are beyond the effective thermal limits of air-based systems in enclosed container configurations.
By Deployment
- The Core/Campus Segment to Hold the Largest Share
- The core/campus segment is expected to account for the largest share of the global containerized data center market.
- This is driven by large-scale deployment of containerized AI clusters at hyperscale campuses as bridge capacity, as well as their use for overflow capacity during the construction of permanent facilities.
- However, the edge/micro segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the proliferation of 5G-enabled edge computing, smart city infrastructure, and autonomous vehicle ecosystems that require locally distributed and rapidly deployable containerized compute capacity.
By End Use
- The BFSI Segment to Account for the Largest Share
- The BFSI segment is expected to account for the largest share of the global containerized data center market.
- This is driven by the extensive use of containerized solutions by the financial services industry for branch-level compute, disaster recovery, and regulatory data residency compliance across geographically distributed operations.
- The need for Tier 3 and Tier 4 equivalent reliability in compact, rapidly deployable formats, combined with strong physical security and environmental monitoring capabilities, positions BFSI as the leading end-use segment by revenue.
- However, the healthcare segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing deployment of AI-enabled diagnostic and clinical decision support applications at hospitals and clinics, which require locally deployed compute infrastructure to meet data sovereignty requirements.
- Additionally, the growing use of containerized data centers in remote healthcare settings and the rising adoption of AI-based medical imaging and genomics analysis are further accelerating demand for edge-based compute capacity near clinical data sources.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global containerized data center market. This dominance is driven by the high concentration of hyperscale operators deploying containerized units as bridge capacity for AI campus expansions, as well as the leading role of U.S.-based cloud providers in driving procurement. The region is also witnessing increasing conversion of decommissioned cryptocurrency mining facilities into containerized AI compute sites, driven by strong growth in AI server deployments and the need to address multi-year grid interconnection backlogs.
Asia-Pacific
Fastest growthHowever, the Asia Pacific containerized data center market is expected to grow at the highest CAGR from 2026 to 2036. This growth is driven by large-scale digital infrastructure expansion across China, India, Japan, Singapore, and Southeast Asia, along with aggressive 5G network densification programs that are accelerating demand for edge-based containerized deployments. In addition, data localization policies, mainly in India, are driving sovereign cloud adoption through modular solutions, while China continues to invest in distributed containerized AI compute campuses. India’s data center capacity is projected to expand significantly through 2030, with containerized solutions capturing an increasing share of new capacity due to faster deployment timelines and lower permitting complexity compared to traditional greenfield construction.
Competitive landscape
- Huawei Technologies Co., Ltd. · China
- IBM Corporation (U.S.)
- Cisco Systems, Inc. (U.S.)
- Schneider Electric SE · France
- Dell Technologies Inc. (U.S.)
- Hewlett Packard Enterprise Company (U.S.)
- Vertiv Holdings Co. (U.S.)
- ZTE Corporation · China
- Eaton Corporation plc · Ireland
- Rittal GmbH & Co. KG · Germany
- Fujitsu Limited · Japan
- Delta Electronics, Inc. · Taiwan
- BladeRoom Group Limited (U.K.)
- Nat Systems (U.S.)
- Flexnode · Sweden
Frequently asked questions
The global containerized data center market is expected to reach USD 103.6 billion by 2036 from an estimated USD 19.02 billion in 2026, at a CAGR of 18.5% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Containerized Data Center Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1859). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/containerized-data-center-market-6542