Data Center Electrical Equipment Market (2026-2036)
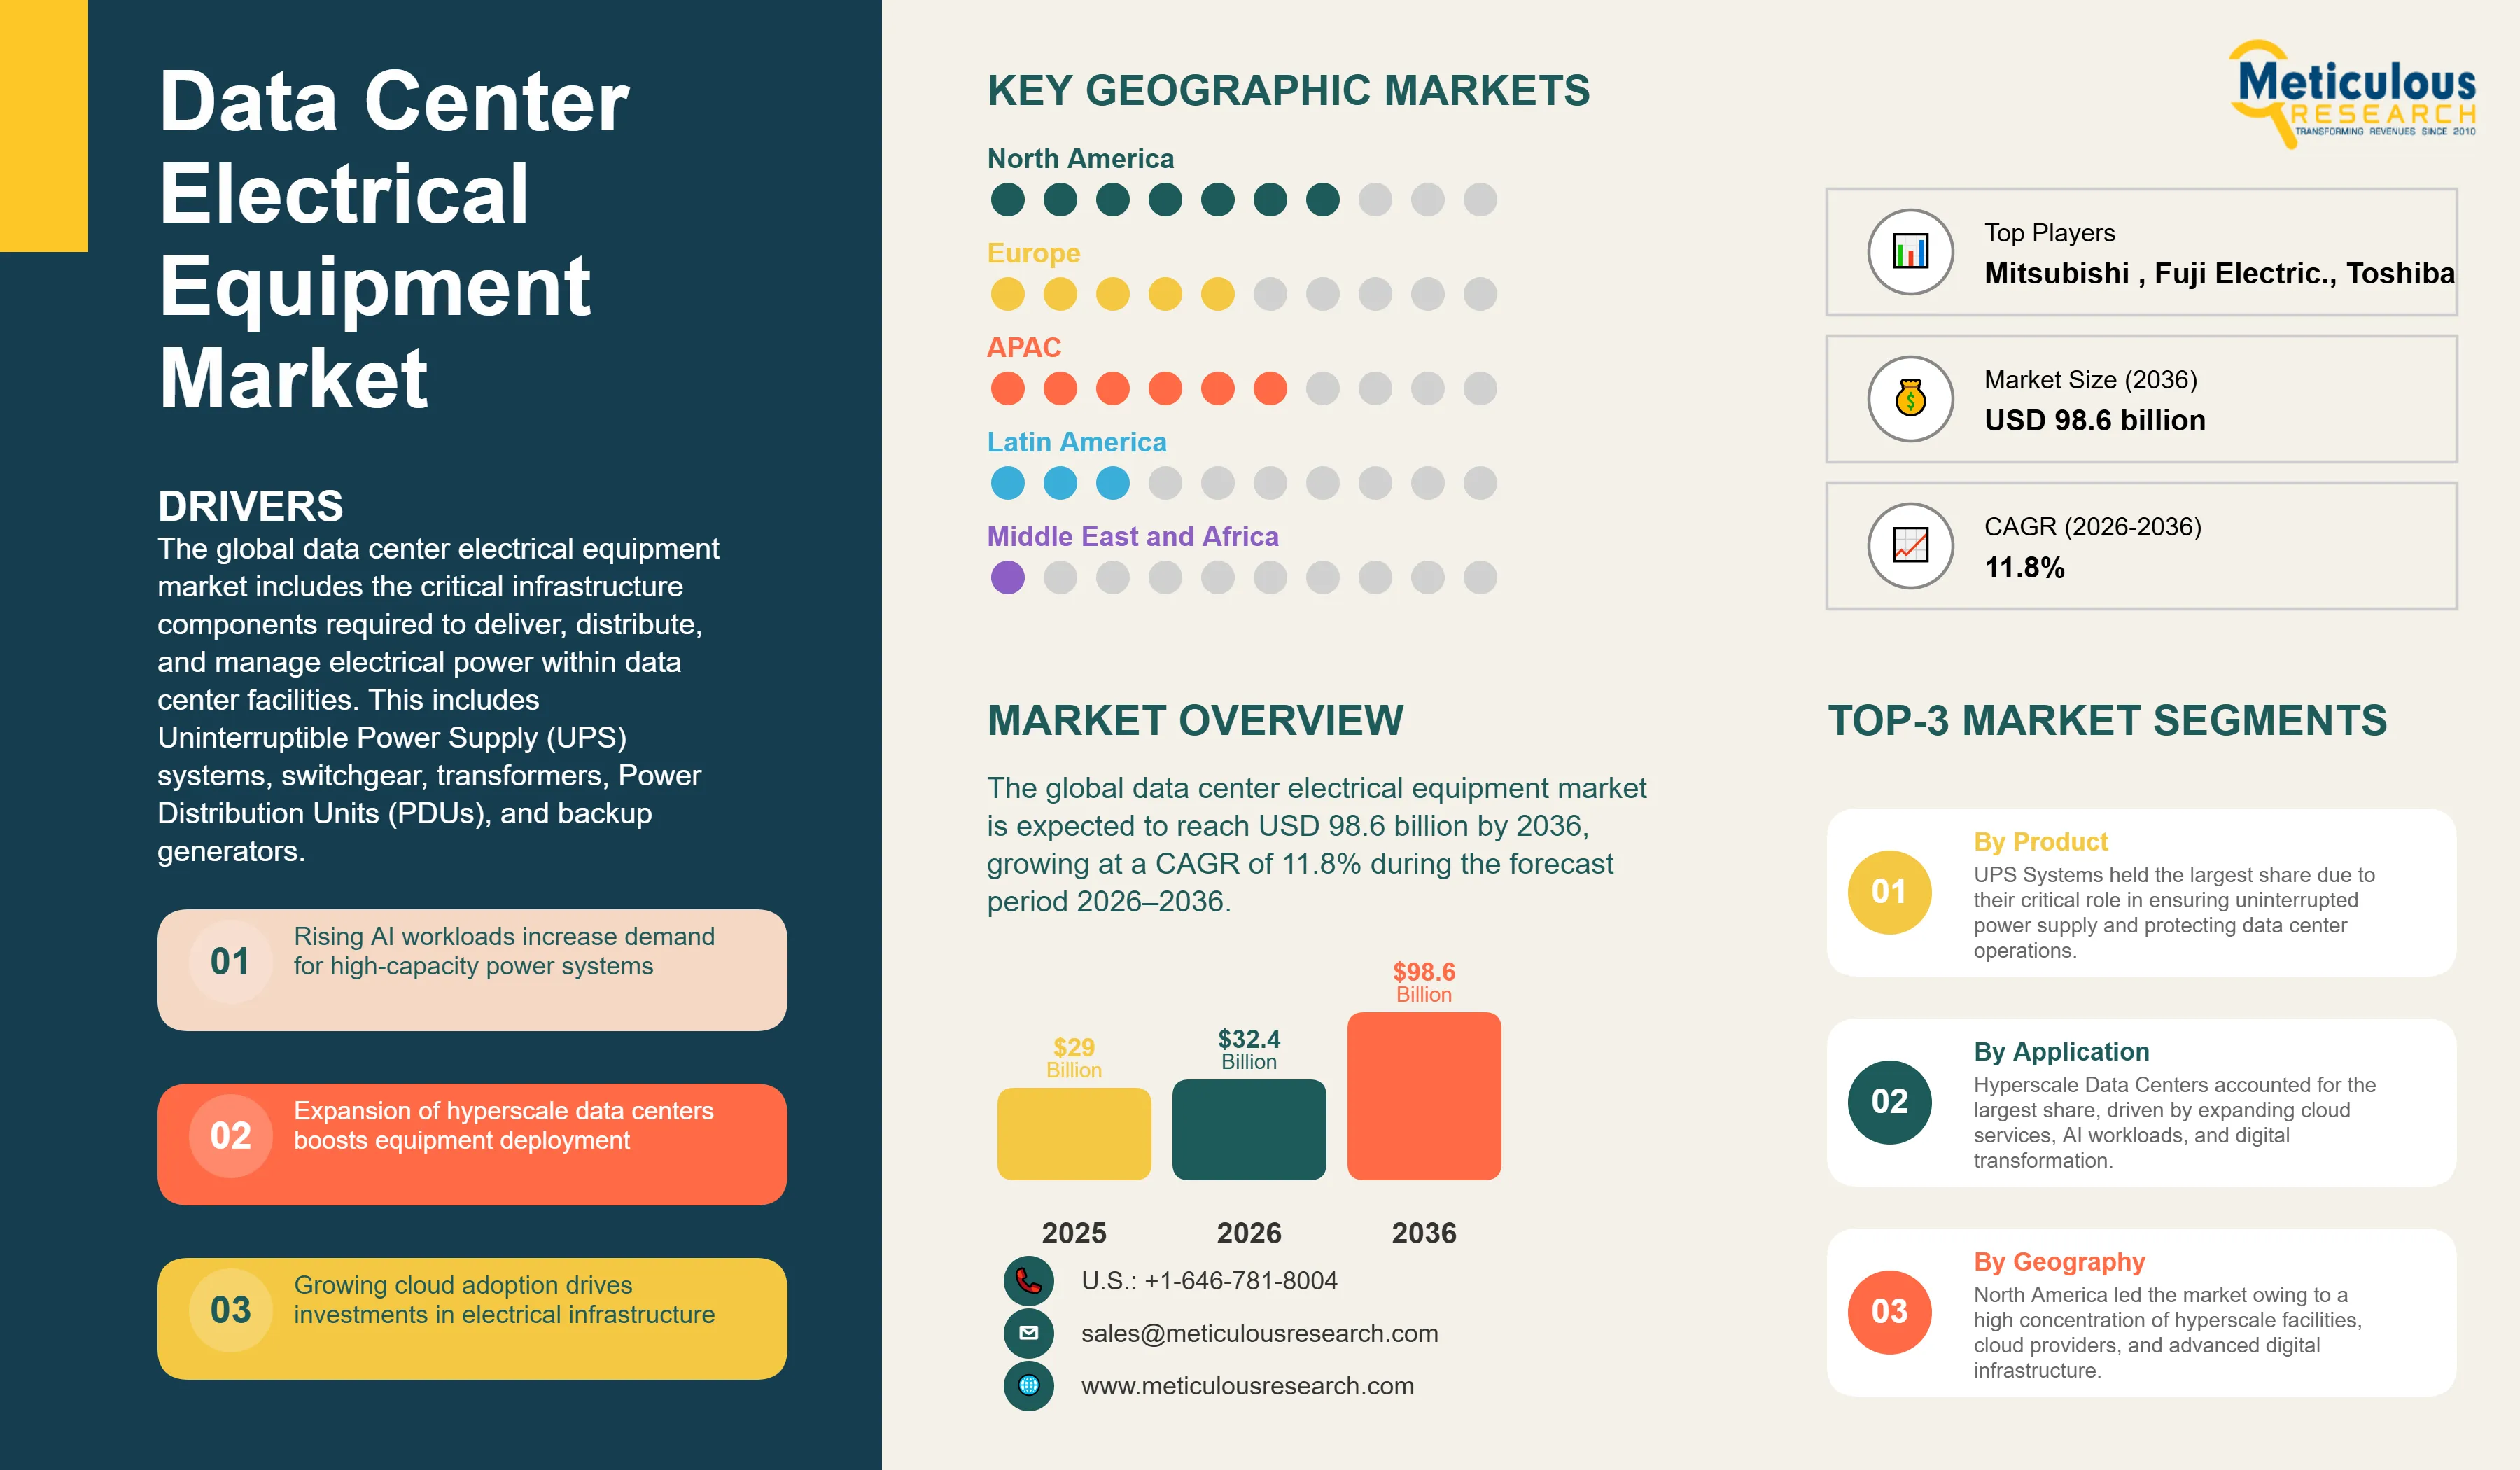
The global data center electrical equipment market was valued at USD 32.4 billion in 2026. This market is expected to reach USD 98.6 billion by 2036, growing at a CAGR of 11.8% during the forecast period 2026–2036.
- Published
- Jun 2026
- Pages
- 245
- Format
- PDF + Excel
- Report ID
- MRSE - 1042004
- Base year
- 2025
- 2026 · ESTIMATED
- $32.40B
- 2036
- $98.60B
- CAGR 2026–2036
- 11.8%
2025 baseline · 2026–2036 forecast at 11.8% CAGR · hover a bar for the value
Key highlights
The global data center electrical equipment market is projected to reach USD 98.6 billion by 2036.
The market is expected to grow at a CAGR of 11.8% during the forecast period 2026–2036.
The global data center electrical equipment market is estimated at USD 32.4 billion in 2026.
North America is expected to dominate the market with the largest share in 2026, supported by the presence of major cloud service providers and a high concentration of hyperscale facilities.
Asia-Pacific is projected to witness the fastest growth during the forecast period, driven by rapid digital transformation and expanding data center hubs in China and India.
By product, the UPS systems segment is expected to hold the largest share in 2026, as these units are critical for ensuring continuous uptime and protecting against power disturbances.
By application, the hyperscale data center segment is expected to account for the largest share in 2026, reflecting the massive power requirements and redundant infrastructure of large-scale cloud environments.
The rise of gigawatt-scale data center campuses is a key trend, with one in three campuses expected to reach this scale by 2035, significantly increasing the demand for high-capacity electrical equipment.
Report summary
| Particulars | Details |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2036 |
| Market Size (2026) | USD 32.40 billion |
| Market Size (2036) | USD 98.60 billion |
| CAGR (2026–2036) | 11.8% |
| Format | PDF, Excel & Cloud Portal · 245 pages |
| Segments Covered | By Product · By Voltage Level · By Data Center Type: Hyperscale, Colocation, Enterprise, Edge |
Report overview
Segments covered: product, voltage level, data center type.
The global data center electrical equipment market includes the critical infrastructure components required to deliver, distribute, and manage electrical power within data center facilities. This includes Uninterruptible Power Supply (UPS) systems, switchgear, transformers, Power Distribution Units (PDUs), and backup generators. As the backbone of data center reliability, this equipment ensures that IT loads remain powered during utility outages and electrical disturbances. The market is currently undergoing a significant transformation driven by the huge scale of hyperscale data centers and the increasing power density of artificial intelligence (AI) workloads. According to the International Energy Agency (IEA), data centers accounted for approximately 1.5% of global electricity consumption in 2024, a figure that is projected to double by 2030, necessitating a corresponding expansion in electrical infrastructure.
The growth of the overall data center electrical equipment market is primarily fueled by the rapid proliferation of cloud services and the global shift toward digital economies. JLL Research projects that the data center sector will add 97 GW of new capacity between 2025 and 2030, effectively doubling the market's footprint. This expansion is characterized by a shift toward larger, more power-intensive facilities. Bloom Energy reports that by 2030, one in five data center campuses will exceed gigawatt scale, rising to one in three by 2035. At this scale, the complexity of electrical distribution increases exponentially, requiring advanced medium-voltage switchgear and high-capacity UPS systems that can provide millisecond-level response times to power fluctuations.
However, the market faces significant restraints, most notably grid connection delays and supply chain constraints. Utility time-to-power for new data center projects is currently 1.5-2 years longer than what hyperscalers and colocation providers anticipate, creating a bottleneck for market expansion. Additionally, the industry is grappling with extended lead times for critical components like transformers and high-voltage switchgear, which can exceed 50-80 weeks in some regions. Furthermore, the transition to sustainable energy sources requires data center operators to integrate microgrids and on-site renewable generation, adding a layer of complexity to the electrical design and increasing initial capital expenditure by 30-50% compared to traditional grid-only connections.
Despite these challenges, the emergence of smart power technologies and the integration of IoT-enabled electrical equipment present substantial growth opportunities. 'Smart' electrical systems provide real-time data on energy consumption and equipment health, allowing for predictive maintenance and optimized power usage. Geographic expansion in Asia-Pacific, driven by rapid urbanization and government digitalization initiatives in China and India, further supports the market's long-term outlook. The integration of liquid cooling systems also creates a demand for specialized electrical equipment capable of operating in proximity to immersion and direct-to-chip cooling infrastructures.
Report infographic
Market dynamics
7 factors across 5 forcesThe primary driver for the global
data center electrical equipment market is the exponential growth in AI-driven power density. Traditional data center racks typically operate at 5-10kW, but AI and machine learning workloads have pushed this density to 50-100kW per rack. This shift requires a fundamental redesign of the power distribution chain, driving demand for high-capacity Power Distribution Units (PDUs), advanced switchgear, and liquid-cooled UPS systems. S&P Global/451 Research estimates that global power demand from data centers will increase from 860 TWh in 2025 to 1,587 TWh by 2030, a surge largely attributed to the deployment of AI infrastructure.
Another key driver is the proliferation
of hyperscale data centers. As organizations migrate their operations to the cloud, major providers like Amazon, Google, and Microsoft are building massive facilities that require robust and redundant electrical systems. These hyperscale facilities often employ 2N or N+1 redundancy configurations, effectively doubling the amount of electrical equipment required per megawatt of IT load. The U.S. Department of Energy (DOE) reports that data center load growth has tripled over the past decade, and this trend is expected to continue as cloud adoption deepens globally.
Table of contents
11 chapters · 105 sections · 245 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product | UPS Systems | Switchgear and PDU |
By Product
- UPS Systems to Hold Largest Share
- The UPS systems segment is expected to hold the largest share of the market.
- UPS systems are the single most critical component for ensuring continuous uptime, as they provide immediate backup power during utility outages and protect sensitive IT equipment from voltage spikes and sags.
- The shift toward high-efficiency, modular UPS systems that can scale with IT load is a key driver for this segment.
- However, the Switchgear and PDU segments are projected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing complexity of power distribution within high-density data centers.
- As rack densities increase, more sophisticated switchgear and PDUs are required to manage the higher amperages and provide granular monitoring and control at the rack level.
Geographic analysis
North America
Largest shareNorth America is expected to dominate the global data center electrical equipment market in 2026, primarily due to the high concentration of hyperscale facilities and the presence of major technology companies. The U.S. Congress reports that data center annual energy use reached ~176 TWh in 2023, representing ~4.4% of total U.S. electricity. This huge energy footprint necessitates a vast and continuously growing electrical infrastructure. The key companies operating in the North American market are Schneider Electric SE, ABB Ltd., Siemens Energy AG, Eaton Corporation plc, and GE Vernova.
Asia-Pacific
Fastest growthAsia-Pacific is projected to witness the fastest growth during the forecast period. This is driven by rapid digital transformation, increasing internet penetration, and significant investments in data center infrastructure in China and India. China's state-led 'East-to-West' computing project is a major driver for new power infrastructure in the region. The key companies operating in the Asia-Pacific market are Mitsubishi Electric Corporation, Fuji Electric Co., Ltd., LS ELECTRIC Co., Ltd., CHINT Group, and Toshiba Energy Systems & Solutions Corporation.
Frequently asked questions
The market is projected to reach USD 98.6 billion by 2036, growing at a CAGR of 11.8% from 2026 to 2036.
Cite this report
Meticulous Research. (2026). Data Center Electrical Equipment Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRSE - 1042004). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/data-center-electrical-equipment-market-6687