Data Center Fire Suppression Systems Market (2026-2036)
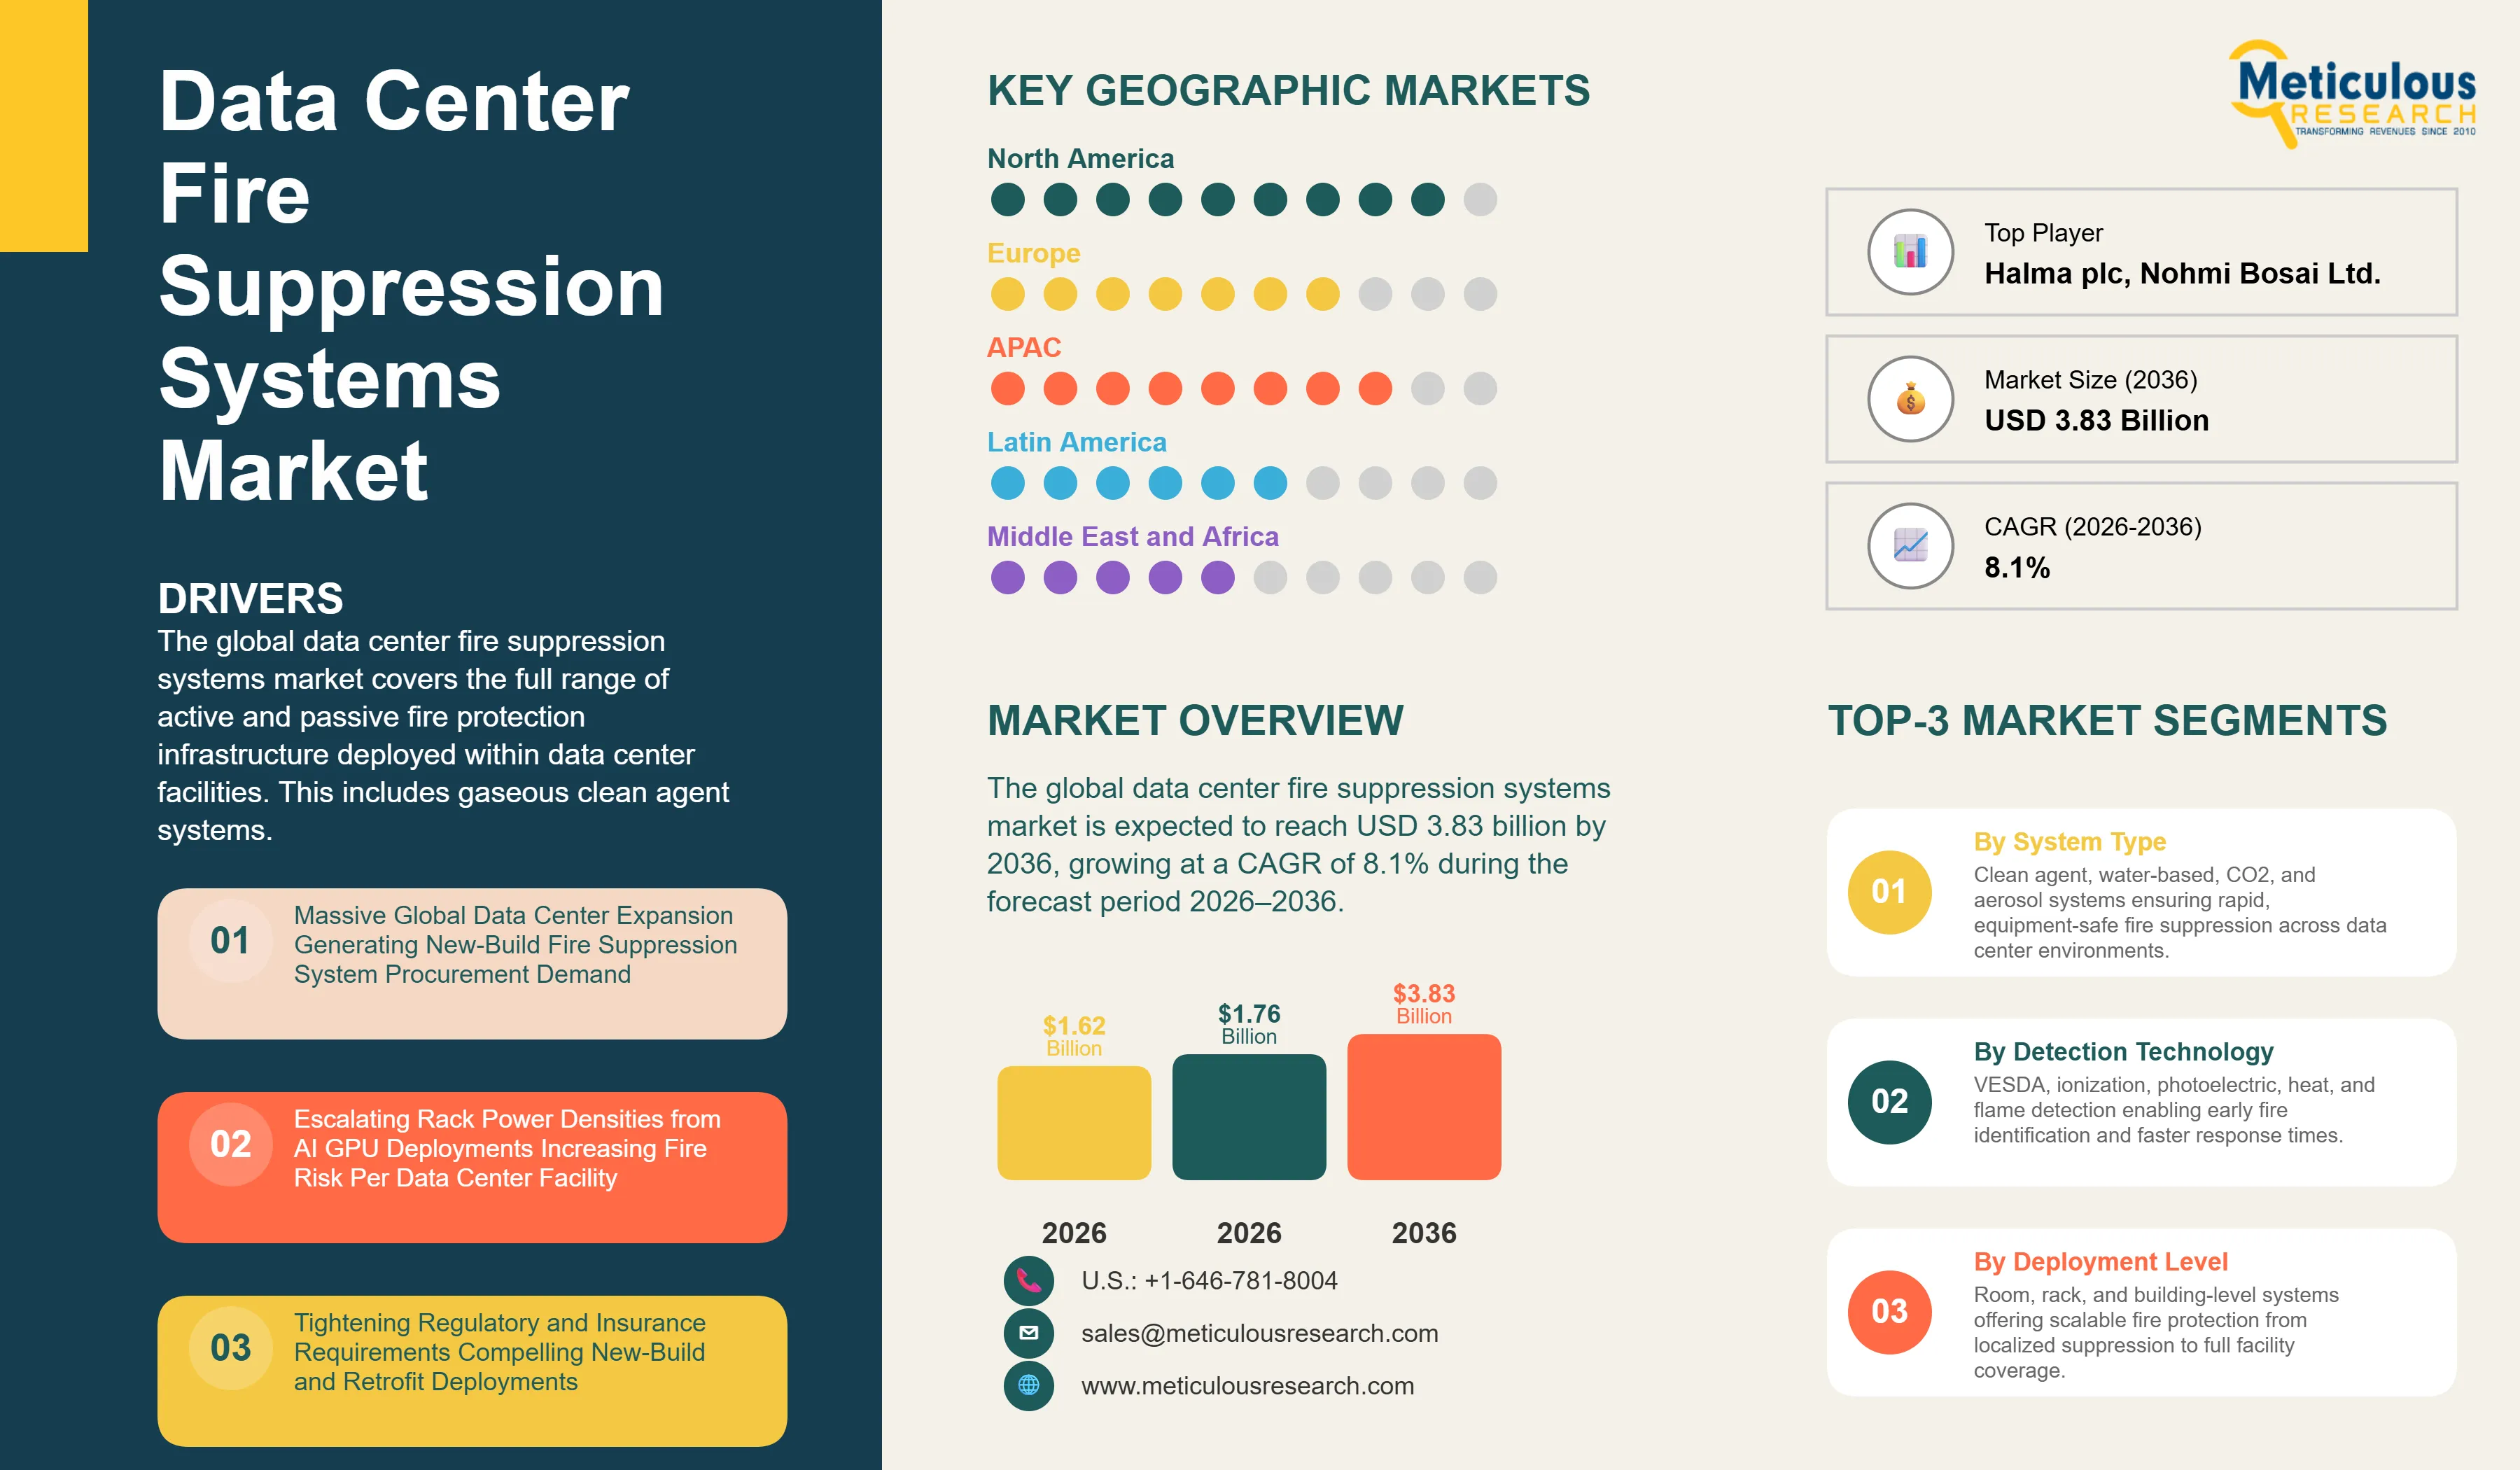
The global data center fire suppression systems market was valued at USD 1.62 billion in 2025. This market is expected to reach USD 3.83 billion by 2036 from an estimated USD 1.76 billion in 2026, growing at a CAGR of 8.1% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 283
- Format
- PDF + Excel
- Report ID
- MR-1861
- Base year
- 2025
- 2025 · BASELINE
- $1.62B
- 2036
- $3.83B
- CAGR 2026–2036
- 8.1%
2025 baseline · 2026–2036 forecast at 8.1% CAGR · hover a bar for the value
Key highlights
The global data center fire suppression systems market is projected to reach USD 3.83 billion by 2036.
The market is expected to grow at a CAGR of 8.1% during the forecast period 2026–2036.
The global data center fire suppression systems market was valued at USD 1.62 billion in 2025 and is estimated to reach USD 3.83 billion in 2026.
North America data center fire suppression systems market is expected to dominate the global data center fire suppression systems market with the largest market share in 2026, driven by the highest concentration of hyperscale and colocation data center deployments, the most stringent fire safety regulatory environment anchored by NFPA 75 and NFPA 76 standards, and the presence of leading fire suppression system manufacturers with established data center customer relationships.
Asia Pacific data center fire suppression systems market is projected to witness the fastest growth during the forecast period, driven by the massive expansion of data center capacity across China, India, Japan, and Southeast Asia, rapidly expanding regulatory frameworks mandating advanced fire safety systems, and the accelerating adoption of AI and cloud infrastructure in the region.
By system type, the clean agent systems segment is expected to hold the largest market share in 2026.
By system type, the water mist systems segment is projected to register the highest CAGR during the forecast period, driven by growing adoption of high-pressure water mist as an environmentally compliant alternative to fluorinated clean agents and an effective solution for lithium-ion battery thermal runaway suppression.
By detection technology, the VESDA/aspirating smoke detection segment is expected to account for the largest share of the market in 2026.
By deployment level, the room/hall level segment is expected to account for the largest share of the market in 2026, while the rack/cabinet level segment is projected to register the highest CAGR, driven by growing adoption of localized in-rack fire suppression for high-density AI GPU server configurations.
By data center type, the hyperscale segment is expected to account for the largest share of the market in 2026, while the edge and micro data centers segment is projected to register the highest CAGR during the forecast period.
By end use, the IT and telecom segment is expected to account for the largest share in 2026, while the healthcare segment is projected to register the highest CAGR during the forecast period.
By geography, North America is expected to dominate the market in 2026, while Asia Pacific is expected to witness the fastest growth during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 3.83 Billion |
| Market Size in 2026 | USD 1.76 Billion |
| Market Size in 2025 | USD 1.62 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 8.1% |
| Format | PDF, Excel & Cloud Portal · 283 pages |
| Dominating System Type | Clean Agent Systems |
| Fastest Growing System Type | Water Mist Systems |
| Dominating Detection Technology | VESDA/Aspirating Smoke Detection |
| Dominating Deployment Level | Room/Hall Level |
| Fastest Growing Deployment Level | Rack/Cabinet Level |
| Dominating Data Center Type | Hyperscale |
| Fastest Growing Data Center Type | Edge & Micro Data Centers |
| Dominating End Use | IT & Telecom |
| Fastest Growing End Use | Healthcare |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: system type, detection technology, deployment level, data center type, end use.
The global data center fire suppression systems market covers the full range of active and passive fire protection infrastructure deployed within data center facilities. This includes gaseous clean agent systems, water-based sprinkler and mist systems, CO2 and aerosol-based solutions, as well as associated detection technologies, control panels, alarm systems, and monitoring services. Collectively, these systems are designed to protect critical data center assets from fire-related operational, financial, and reputational risks.
Fire suppression systems are mandatory under established safety standards such as NFPA 75, NFPA 76, EN 15004, and applicable local building codes across major data center markets. As a result, fire protection infrastructure represents a non-discretionary investment for data center operators, forming an essential component of all new facility construction and periodic upgrade cycles.
The growth of the global data center fire suppression systems market is primarily driven by the rapid expansion of hyperscale and colocation data center capacity worldwide. This expansion is generating significant new-build demand for advanced fire suppression systems across all facility types.
In addition, the increasing deployment of high-density AI and GPU server configurations is elevating thermal loads and electrical fault risks, necessitating more robust and responsive fire protection solutions. Tightening global fire safety regulations and insurance requirements are further compelling operators to upgrade both new and existing facilities with compliant suppression systems.
However, the market faces certain constraints. Clean agent fire suppression systems involve high installation and recharge costs, mainly in large hyperscale environments that require substantial volumes of pressurized agents.
Moreover, increasing regulatory restrictions on high global warming potential fluorinated agents, such as HFC-227ea under the EU F-Gas framework, are limiting the use of certain legacy suppression technologies and increasing compliance complexity.
Despite these challenges, several growth opportunities are emerging. The adoption of AI-enabled very early smoke detection systems and IoT-based fire safety monitoring solutions is enabling predictive risk analytics and faster incident response.
Additionally, hybrid fire suppression approaches, combining gaseous agents with water mist systems, are gaining traction, mainly for managing lithium-ion battery-related fire risks in data center environments. The expansion of edge and micro data centers is also driving demand for compact, modular fire suppression solutions tailored to space-constrained deployments.
A key trend shaping the market is the integration of fire suppression monitoring with data center infrastructure management (DCIM) platforms. This integration enables unified visibility, centralized control, and improved operational efficiency, supporting more proactive and data-driven fire safety management across modern data center environments.
Report infographic
Market dynamics
3 factors across 1 forceAI-Driven VESDA Integration with DCIM Platforms for Predictive Fire Risk Management
The integration of very early smoke detection apparatus (VESDA) with data center infrastructure management (DCIM) platforms is transforming fire protection from a reactive emergency response function into a continuous, predictive risk management capability. By correlating smoke particle data with server operations, airflow dynamics, and thermal sensor inputs, these systems enable real-time fire risk analytics and earlier detection of potential incidents.
Solutions from Honeywell International Inc. and Siemens AG now offer API-level integration with major DCIM platforms, allowing operators to monitor fire risk alongside key performance metrics such as power usage effectiveness, cooling efficiency, and server utilization within a unified operational framework.
This integration is driving a sustained upgrade cycle, as legacy standalone fire detection systems are increasingly replaced with DCIM-integrated architectures. The trend is especially evident in hyperscale and AI-optimized data centers, where early warning capabilities and system-wide operational visibility are critical for maintaining uptime and managing high-density compute environments.
Lithium-Ion Battery Thermal Runaway Creating New Hybrid Suppression System Requirements
The rapid deployment of large-scale lithium-ion battery energy storage systems within and adjacent to data center facilities is creating new fire suppression requirements that conventional gaseous clean agent systems and traditional water-based sprinkler systems cannot fully address on their own. As battery energy storage becomes integral to data center power architectures, fire protection strategies are evolving to accommodate the unique risks associated with lithium-ion technologies.
Lithium-ion thermal runaway involves self-sustaining exothermic reactions that cannot be effectively suppressed through oxygen displacement, the primary mechanism of gaseous clean agent systems. Instead, these events require continuous cooling to reduce cell temperatures below the propagation threshold, making water-based suppression methods essential for effective mitigation.
As a result, an emerging best-practice approach is the adoption of hybrid fire suppression architectures. These systems combine water mist or direct water application for battery cooling and heat dissipation with gaseous clean agent systems deployed in surrounding areas to protect IT equipment. This hybrid model is driving simultaneous growth in both water-based and clean agent fire suppression segments within data center environments.
Rack-Level Micro-Suppression Systems for High-Density AI GPU Configurations
The adoption of in-rack micro suppression systems, incorporating miniaturized clean agent or inert gas dispensers integrated directly within server rack enclosures, is increasing as data center operators deploy high-density AI GPU configurations. In such environments, conventional room-level suppression systems can lead to disproportionate operational disruption when responding to localized fire incidents.
Rack-level suppression systems detect smoke or heat within individual enclosures and release a precisely metered quantity of suppression agent to extinguish the fire at its source. This targeted response avoids triggering full room-level discharge, thereby preserving operational continuity in adjacent racks and minimizing downtime.
This category is emerging as a fast-growing deployment-level segment within the fire suppression market. It represents a new procurement layer that complements existing room-level systems, rather than replacing them, especially in high-density and AI-optimized data center environments.
Table of contents
13 chapters · 122 sections · 283 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By System Type | Clean Agent Systems | Water mist systems |
| By Detection Technology | VESDA/Aspirating Smoke Detection | — |
| By Deployment Level | Room/Hall Level | Rack/cabinet level |
| By Data Center Type | Hyperscale | Edge and micro data centers |
| By End Use | — | Healthcare |
By System Type
- The Clean Agent Systems Segment to Dominate the Global Data Center Fire Suppression Systems Market
- The clean agent systems segment is expected to account for around 55–60% of the global data center fire suppression systems market, making it the largest technology segment.
- The large share of this segment is attributed to the universal preference of data center operators for electrically non‑conductive, residue‑free gaseous suppression agents, particularly Novec 1230, FM‑200, and inert‑gas blends, that can extinguish fires within approximately 10 seconds without damaging sensitive IT equipment, without creating secondary water damage, and without interrupting operations in adjacent zones.
- Clean agent systems are widely treated as the de‑facto standard specification in hyperscale and colocation data center fire‑protection programs globally.
- However, the water mist systems segment is projected to register the highest CAGR during the forecast period.
- The high growth of this segment is driven by the growing adoption of high‑pressure water mist as a sustainable, environmentally compliant suppression alternative, using approximately 90% less water than traditional sprinklers while still ensuring minimal operational disruption, and the emerging application of water‑mist hybrid systems for lithium‑ion battery thermal‑runaway suppression in data center BESS deployments.
By Detection Technology
- The VESDA/Aspirating Smoke Detection Segment to Hold the Largest Share
- The VESDA/aspirating smoke detection segment is expected to account for the largest share of the global data center fire suppression systems market.
- The large market share of this segment is attributed to the universal specification of VESDA and equivalent aspirating smoke detection systems by hyperscale and Tier 3+ colocation operators who require the earliest possible warning of developing fire conditions in high-value, continuously operational IT environments.
By Deployment Level
- The Room/Hall Level Segment to Hold the Largest Share
- The room/hall level segment is expected to account for the largest share of the global data center fire suppression systems market, highlighting the foundational role of data hall-level gaseous clean agent flooding systems as the primary suppression technology across all data center types.
- Room/hall level suppression indicates the highest per-installation procurement value and is the mandatory baseline specification for all new data center construction across all major regulatory jurisdictions.
- However, the rack/cabinet level segment is projected to register the highest CAGR during the forecast period.
- The high growth of this segment is driven by the growing adoption of in-rack micro-suppression systems for high-density AI GPU server configurations that require localized suppression capability to avoid the operational disruption of full data hall agent discharge for a contained rack-level fire event.
By Data Center Type
- The Hyperscale Segment to Account for the Largest Share
- The hyperscale segment is expected to account for the largest share of the global data center fire suppression systems market.
- This dominance is driven by the scale of fire suppression procurement at hyperscale AI campuses, where each 100+ MW facility requires coverage across multiple data halls, UPS and BESS rooms, and extensive support infrastructure.
- These deployments generate significant system-level spending per campus, making hyperscale operators and cloud providers the largest and most technically demanding buyers of fire suppression solutions.
- However, the edge and micro data centers segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the proliferation of distributed edge locations supporting 5G networks, industrial AI, and autonomous systems.
- These deployments require compact, self-contained fire suppression solutions suited to space-constrained and remotely operated environments, where conventional room-level systems are often impractical.
By End Use
- The IT & Telecom Segment to Hold the Largest Share
- The IT and telecom segment is expected to account for the largest share of the global data center fire suppression systems market.
- This segment includes hyperscale cloud providers, telecommunications carriers, colocation operators, and IT infrastructure companies, collectively representing the largest buyers of fire suppression systems.
- These organizations deploy advanced detection and suppression technologies to safeguard high-value IT assets and ensure compliance with strict service level agreements.
- However, the healthcare segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing adoption of AI-enabled clinical applications that require dedicated on-premises data center infrastructure.
- In addition, stringent fire safety regulations in healthcare facilities are driving the adoption of high-specification fire suppression systems that exceed standard commercial data center requirements
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global data center fire suppression systems market. This dominant position is attributed to the highest global density of hyperscale data center deployments, which generate the largest fire‑suppression procurement volumes; a highly stringent regulatory framework under NFPA 75 and NFPA 76; and a mature ecosystem of fire‑suppression manufacturers and specialist data center fire‑protection integrators.
Asia-Pacific
Fastest growthHowever, Asia Pacific is expected to register the fastest growth rate during the forecast period. China leads the regional growth, with the highest CAGR projected from 2026 to 2036, driven by large‑scale investments in hyperscale and AI‑optimized data centers and the tightening of Chinese fire‑safety standards for critical IT infrastructure. India follows, with data center capacity expected to grow substantially over the coming years, each megawatt of power‑densified capacity requiring compliant fire‑suppression systems for data halls, UPS rooms, and support spaces. Japan, Singapore, and South Korea are also contributing to regional growth through sustained data center investment anchored to national digital‑infrastructure strategies and increasingly stringent fire‑safety compliance requirements.
Competitive landscape
- Honeywell International Inc. (U.S.)
- Johnson Controls International plc · Ireland
- Siemens AG · Germany
- Carrier Global Corporation (U.S.)
- Eaton Corporation plc · Ireland
- Fike Corporation (U.S.)
- Robert Bosch GmbH · Germany
- Minimax Viking Group · Germany
- ORR Protection Systems (U.S.)
- Halma plc (U.K.)
- Hochiki Corporation · Japan
- Nohmi Bosai Ltd. · Japan
- Kidde Fire Systems (U.S.)
- SEM‑SAFE · Denmark
- Securiton AG · Switzerland
Frequently asked questions
The global data center fire suppression systems market is expected to reach USD 3.83 billion by 2036 from an estimated USD 1.76 billion in 2026, at a CAGR of 8.1% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Data Center Fire Suppression Systems Market - Global Opportunity Analysis And Industry Forecast (2026-2036) (Report No. MR-1861). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/data-center-fire-suppression-systems-market-6544