Patient Warming Systems Market (2026-2036)
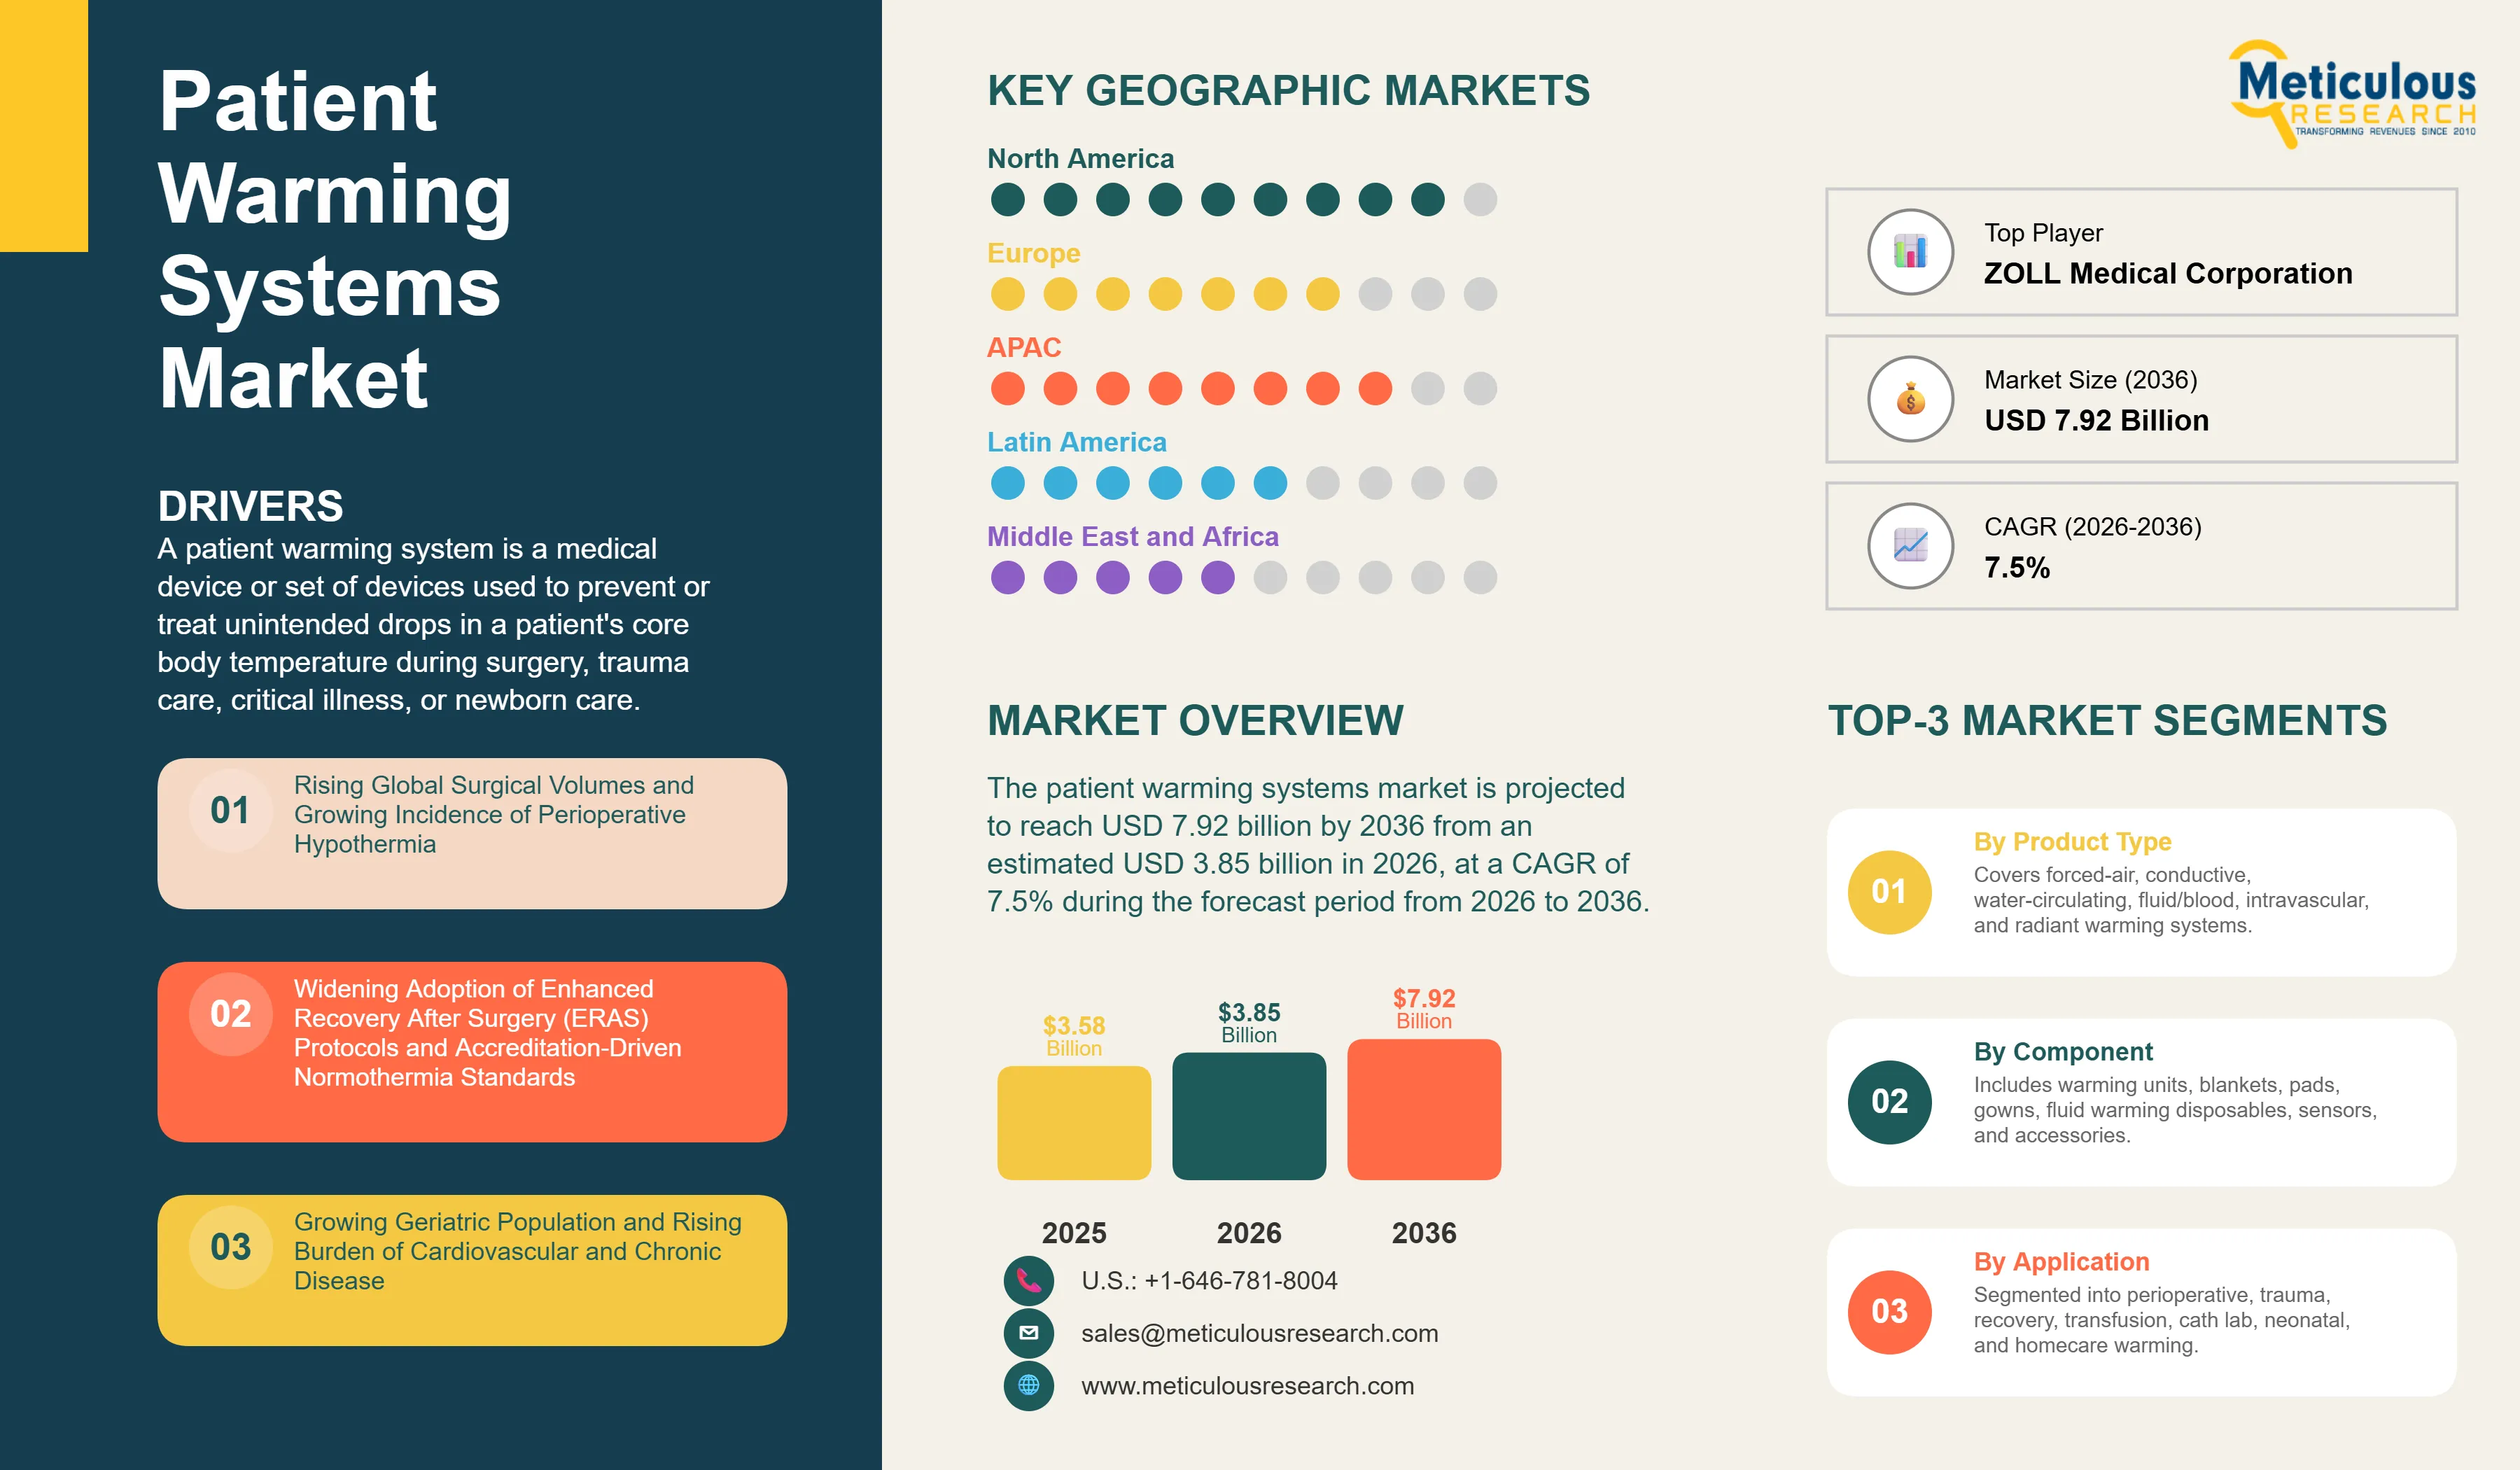
The global patient warming systems market is projected to reach USD 7.92 billion by 2036 from an estimated USD 3.85 billion in 2026, at a CAGR of 7.5% during the forecast period from 2026 to 2036.
- Published
- Jul 2026
- Pages
- 327
- Format
- PDF + Excel
- Report ID
- MR-2100
- Base year
- 2025
- 2026 · ESTIMATED
- $3.85B
- 2036
- $7.92B
- CAGR 2026–2036
- 7.5%
2025 baseline · 2026–2036 forecast at 7.5% CAGR · hover a bar for the value
Key highlights
The global patient warming systems market is projected to reach USD 7.92 billion by 2036, growing at a CAGR of 7.5% during 2026 to 2036.
Rising surgical volumes and the well-documented risk of unintended perioperative hypothermia continue to anchor demand for active warming across operating rooms and recovery units.
Hospitals are formalizing normothermia protocols as part of enhanced recovery after surgery (ERAS) pathways, pushing warming from an optional comfort measure to a standardized part of surgical care.
A growing and aging surgical population is raising the number of patients who are physiologically more vulnerable to heat loss during anesthesia.
The forced-air (convective) warming systems segment holds the largest share in 2026, while intravascular and fluid/blood warming systems are expected to grow the fastest.
The blankets, pads and mattresses segment leads by component in 2026, given their status as high-frequency, single-use consumables tied to every warming episode.
The perioperative/surgical warming application holds the largest share in 2026, as maintaining normothermia during anesthesia remains the primary clinical use case.
The hospitals segment holds the largest share in 2026, while ambulatory surgical centers are expected to register the fastest growth.
North America accounts for the largest share of the global market in 2026, supported by early adoption of active warming protocols and established reimbursement pathways.
Asia-Pacific is expected to witness the fastest growth over the forecast period, driven by rising surgical volumes and hospital modernization.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026 to 2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 7.5% |
| Format | PDF, Excel & Cloud Portal · 327 pages |
| Market Size (Value) in 2026 | USD 3.85 Billion |
| Market Size (Value) in 2036 | USD 7.92 Billion |
| Segments Covered | By Product Type - Forced-Air (Convective) Warming Systems - Conductive/Resistive Warming Systems - Water-Circulating Warming Systems - Fluid and Blood Warming Systems - Intravascular Temperature Management Systems - Radiant Warming Systems By Component - Warming Units/Consoles - Blankets, Pads and Mattresses - Warming Gowns - Fluid Warming Sets and Disposables - Temperature Sensors and Accessories By Application - Perioperative/Surgical Warming - Critical Care and Trauma Warming - Post-Anesthesia Care and Recovery - Fluid and Blood Transfusion Warming - Interventional and Cath Lab Procedures - Newborn and Pediatric Warming - Home and Outpatient Care By End User - Hospitals - Ambulatory Surgical Centers - Trauma and Emergency Care Centers - Maternity and Neonatal Care Units - Homecare and Rehabilitation Settings |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, and Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Australia, and Rest of Asia-Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), and the Middle East & Africa (Saudi Arabia, UAE, South Africa, and Rest of Middle East & Africa) |
| Key Companies | Solventum Corporation (U.S.), ICU Medical, Inc. (U.S.), Gentherm Incorporated (U.S.), Medtronic plc (Ireland), ZOLL Medical Corporation (U.S.), Belmont Medical Technologies, Inc. (U.S.), Stryker Corporation (U.S.), Barkey GmbH & Co. KG (Germany), Dräger (Germany), GE HealthCare Technologies Inc. (U.S.), Atom Medical Corporation (Japan), Inspiration Healthcare Group plc (U.K.), Geratherm Medical AG (Germany), Stihler Electronic GmbH (Germany), Cincinnati Sub-Zero (U.S.) |
Report overview
Segments covered: product type, component, application, end user. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
A patient warming system is a medical device or set of devices used to prevent or treat unintended drops in a patient's core body temperature during surgery, trauma care, critical illness, or newborn care. The category spans forced-air (convective) warming units and disposable blankets, conductive and resistive warming mattresses, water-circulating warming pads, fluid and blood warmers, intravascular temperature management catheters, and radiant warmers, all built around a shared clinical goal: keeping core body temperature within the normothermic range of roughly 36.0°C to 37.5°C throughout a procedure or period of care.
Demand for these systems is closely tied to the volume and complexity of surgical care worldwide. More than 313 million surgical procedures are performed globally each year, and every one of these cases carries some risk of anesthesia-induced heat loss. Clinical literature reviewed in connection with European perioperative care guidelines indicates that between roughly 25% and 90% of patients undergoing elective surgery experience inadvertent postoperative hypothermia, a complication associated with a higher rate of wound infections, more frequent cardiac complications, and increased need for blood transfusion compared with normothermic patients. Guidance from the UK's National Institute for Health and Care Excellence recommends prewarming patients for at least 30 minutes before anesthesia induction and actively warming any procedure expected to last longer than half an hour, which has helped push forced-air and conductive warming from a niche comfort measure into a standard part of surgical protocol across many health systems.
The population most exposed to surgery is also getting older. The number of people aged 60 years or older stood at 1.1 billion in 2023 and is projected to nearly double to 2.1 billion by 2050, and this age group carries a disproportionate share of both surgical volume and thermoregulatory vulnerability, since older patients lose heat faster under anesthesia and tolerate hypothermia less well. As hospitals in developed and emerging markets alike expand operating room capacity to serve this population, they are building normothermia management, including dedicated warming units, disposable blankets, and fluid warmers, into standard surgical purchasing rather than treating it as an add-on.
Report infographic
Market dynamics
5 factors across 2 forcesRising Global Surgical Volumes and Growing Incidence of Perioperative Hypothermia
The single largest driver of demand is the sheer scale of surgical activity worldwide. Globally, over 313 million patients undergo surgical procedures annually, and every general or regional anesthetic carries a risk of impaired thermoregulation. Research synthesized for European perioperative hypothermia guidelines found that patients who become hypothermic during elective surgery face substantially higher relative risk of wound infection, cardiac complications, and blood transfusion compared with patients who remain normothermic, which has made active warming a recognized lever for reducing postoperative complications and length of stay. A French multicenter study of perioperative practice found that the prevalence of hypothermia on admission to the recovery room remained at 53.5% even though a warming device had been used for over 90% of patients studied, underscoring that the clinical problem persists even where warming equipment is already in use, and that hospitals continue to invest in better-performing systems rather than treating existing equipment as sufficient.
Widening Adoption of ERAS Protocols and Accreditation-Driven Normothermia Standards
A second driver is the formalization of temperature management within structured surgical care pathways. Enhanced recovery after surgery (ERAS) protocols, now used across a growing share of elective procedures, treat maintenance of normothermia as one of several evidence-based steps that together shorten recovery and reduce complications. Clinical guidance recommends warming all surgical patients undergoing procedures longer than 30 minutes, with prewarming for at least 30 minutes before induction of anesthesia recommended as best practice. As accreditation bodies and hospital quality programs increasingly audit compliance with these standards, facilities are standardizing warming equipment across every operating room and recovery bay rather than deploying it selectively, which supports steady replacement and expansion demand for manufacturers.
Growing Geriatric Population and Rising Burden of Cardiovascular and Chronic Disease
The third major driver is the rapid growth of the global elderly population. According to the World Health Organization (WHO), the number of people aged 60 years and older is projected to double from approximately 1 billion in 2020 to 2.1 billion by 2050, while the population aged 80 years and older is expected to triple during the same period, reaching 426 million. Older adults undergo surgical procedures more frequently for cardiovascular, orthopedic, oncologic, and other chronic conditions and are at greater risk of perioperative hypothermia due to age-related declines in thermoregulatory function. Consequently, the increasing volume of complex surgeries among elderly patients is driving greater adoption of patient warming systems to maintain normothermia, reduce perioperative complications, and improve clinical outcomes. Healthcare providers are therefore increasingly incorporating advanced warming technologies into routine perioperative care, particularly for lengthy and high-risk procedures.
Table of contents
12 chapters · 120 sections · 327 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Product Type | Forced-Air Warming Systems | — |
| By Component | Blankets, Pads and Mattresses | Fluid warming sets and disposables |
| By Application | Perioperative/Surgical Warming | Critical care and trauma warming |
| By End User | Hospitals | Ambulatory surgical centers |
By Product Type
- Forced-Air Warming Systems Lead the Market in 2026
- Forced-air warming systems are expected to account for the largest share of the market in 2026, reflecting their established position as the default active warming modality across operating rooms, supported by a wide base of installed warming units and a recurring disposable blanket and gown business.
- Intravascular temperature management systems and fluid and blood warming systems are projected to register the fastest growth during the forecast period, supported by expanding use in cardiac surgery, targeted temperature management following cardiac arrest, and trauma resuscitation protocols that call for rapid, high-volume warming of transfused fluids and blood products.
By Component
- Blankets, pads and mattresses hold the largest share in 2026, since these single-use consumables are replaced with every patient episode, unlike the reusable warming console that anchors the system.
- Fluid warming sets and disposables are expected to grow the fastest, tracking the broader shift toward disposable, single-patient-use administration sets across blood and fluid warming applications for infection control reasons.
By Application
- Perioperative/surgical warming holds the largest share in 2026, as maintaining normothermia from prewarming through recovery remains the core, highest-volume use case for these systems.
- Critical care and trauma warming is expected to grow the fastest, as emergency departments, ICUs, and trauma centers increasingly formalize temperature management protocols for resuscitation and post-cardiac-arrest care.
By End User
- Hospitals Lead the Market in 2026
- Hospitals hold the largest share in 2026, reflecting their high surgical volumes, broad procedural mix, and established capital budgets for perioperative equipment.
- Ambulatory surgical centers are expected to grow the fastest, as more moderate-complexity procedures shift to outpatient settings that must independently equip operating suites with warming systems.
Geographic analysis
North America
Largest shareNorth America holds the largest share in 2026, underpinned by early adoption of formal normothermia protocols, a dense base of leading manufacturers headquartered in the region, and established hospital purchasing infrastructure for perioperative equipment. North America Leads the Market in 2026
Asia-Pacific
Fastest growthAsia-Pacific is expected to record the fastest growth over the forecast period. Rapid hospital construction, rising surgical volumes tied to an aging population that is projected to represent around one in five people globally by 2050, and growing government investment in surgical care access across China, India, and Southeast Asia are driving adoption of warming systems as new operating rooms come online.
Europe
Europe remains an established market, supported by national clinical guidelines on perioperative hypothermia prevention in countries such as the UK and Germany that have formalized warming into standard surgical protocol.
Competitive landscape
Leading companies in the market have grown through new product launches, portfolio expansion, distribution partnerships, and targeted acquisitions. Broadening disposable product lines, extending into portable and battery-powered formats, and deepening distribution reach in emerging markets have been the most common ways players strengthen their position.
- July 2025
Medline launched the ComfortTemp® Patient Warming System, featuring disposable warming blankets and gowns integrated with a blower, lock-in hose mechanism, and rotating elbow connector to improve perioperative patient temperature management.
- June 2025
Gentherm expanded its strategic partnership with DUOMED into France, extending distribution of its patient temperature management portfolio—including the Astopad® resistive warming system and Vytil-branded convective warming system—across France and the Benelux region.
- June 2025
3T Medical Systems completed the acquisition of the Altrix™ Precision Temperature Management System business from Stryker, strengthening its portfolio of patient temperature management solutions and expanding its global customer base.
- Solventum Corporation (U.S.)
- ICU Medical, Inc. (U.S.)
- Stryker Corporation (U.S.)
- Medtronic plc · Ireland
- GE HealthCare Technologies Inc. (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Gentherm Incorporated (U.S.)
- ZOLL Medical Corporation (U.S.)
- Belmont Medical Technologies, Inc. (U.S.)
- Inspiration Healthcare Group plc (U.K.)
- Geratherm Medical AG · Germany
- Stihler Electronic GmbH · Germany
- Barkey GmbH & Co. KG · Germany
- Atom Medical Corporation · Japan
- Encompass Group, LLC (U.S.)
Expert perspectives
“Normothermia management has moved from a perioperative nicety to a quality metric that hospitals are held accountable for. Purchasing decisions now weigh workflow integration and disposable cost per case as heavily as raw warming performance.”
“We are seeing steady replacement demand as older forced-air units reach end of life, alongside genuinely new demand from ambulatory surgical centers that are adding warming protocols for the first time as they take on more complex caseloads.”
“Fluid and blood warming is the quieter half of this market, but it's just as critical in trauma and obstetric hemorrhage response. Facilities that once treated it as optional equipment are now building it into mandatory trauma bay and OR checklists.”
Frequently asked questions
The global patient warming systems market size is estimated at USD 3.85 billion in 2026.
Cite this report
Meticulous Research. (2026). Patient Warming Systems Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-2100). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/patient-warming-systems-market-6783