Off-Highway Plastics Market (2026-2036)
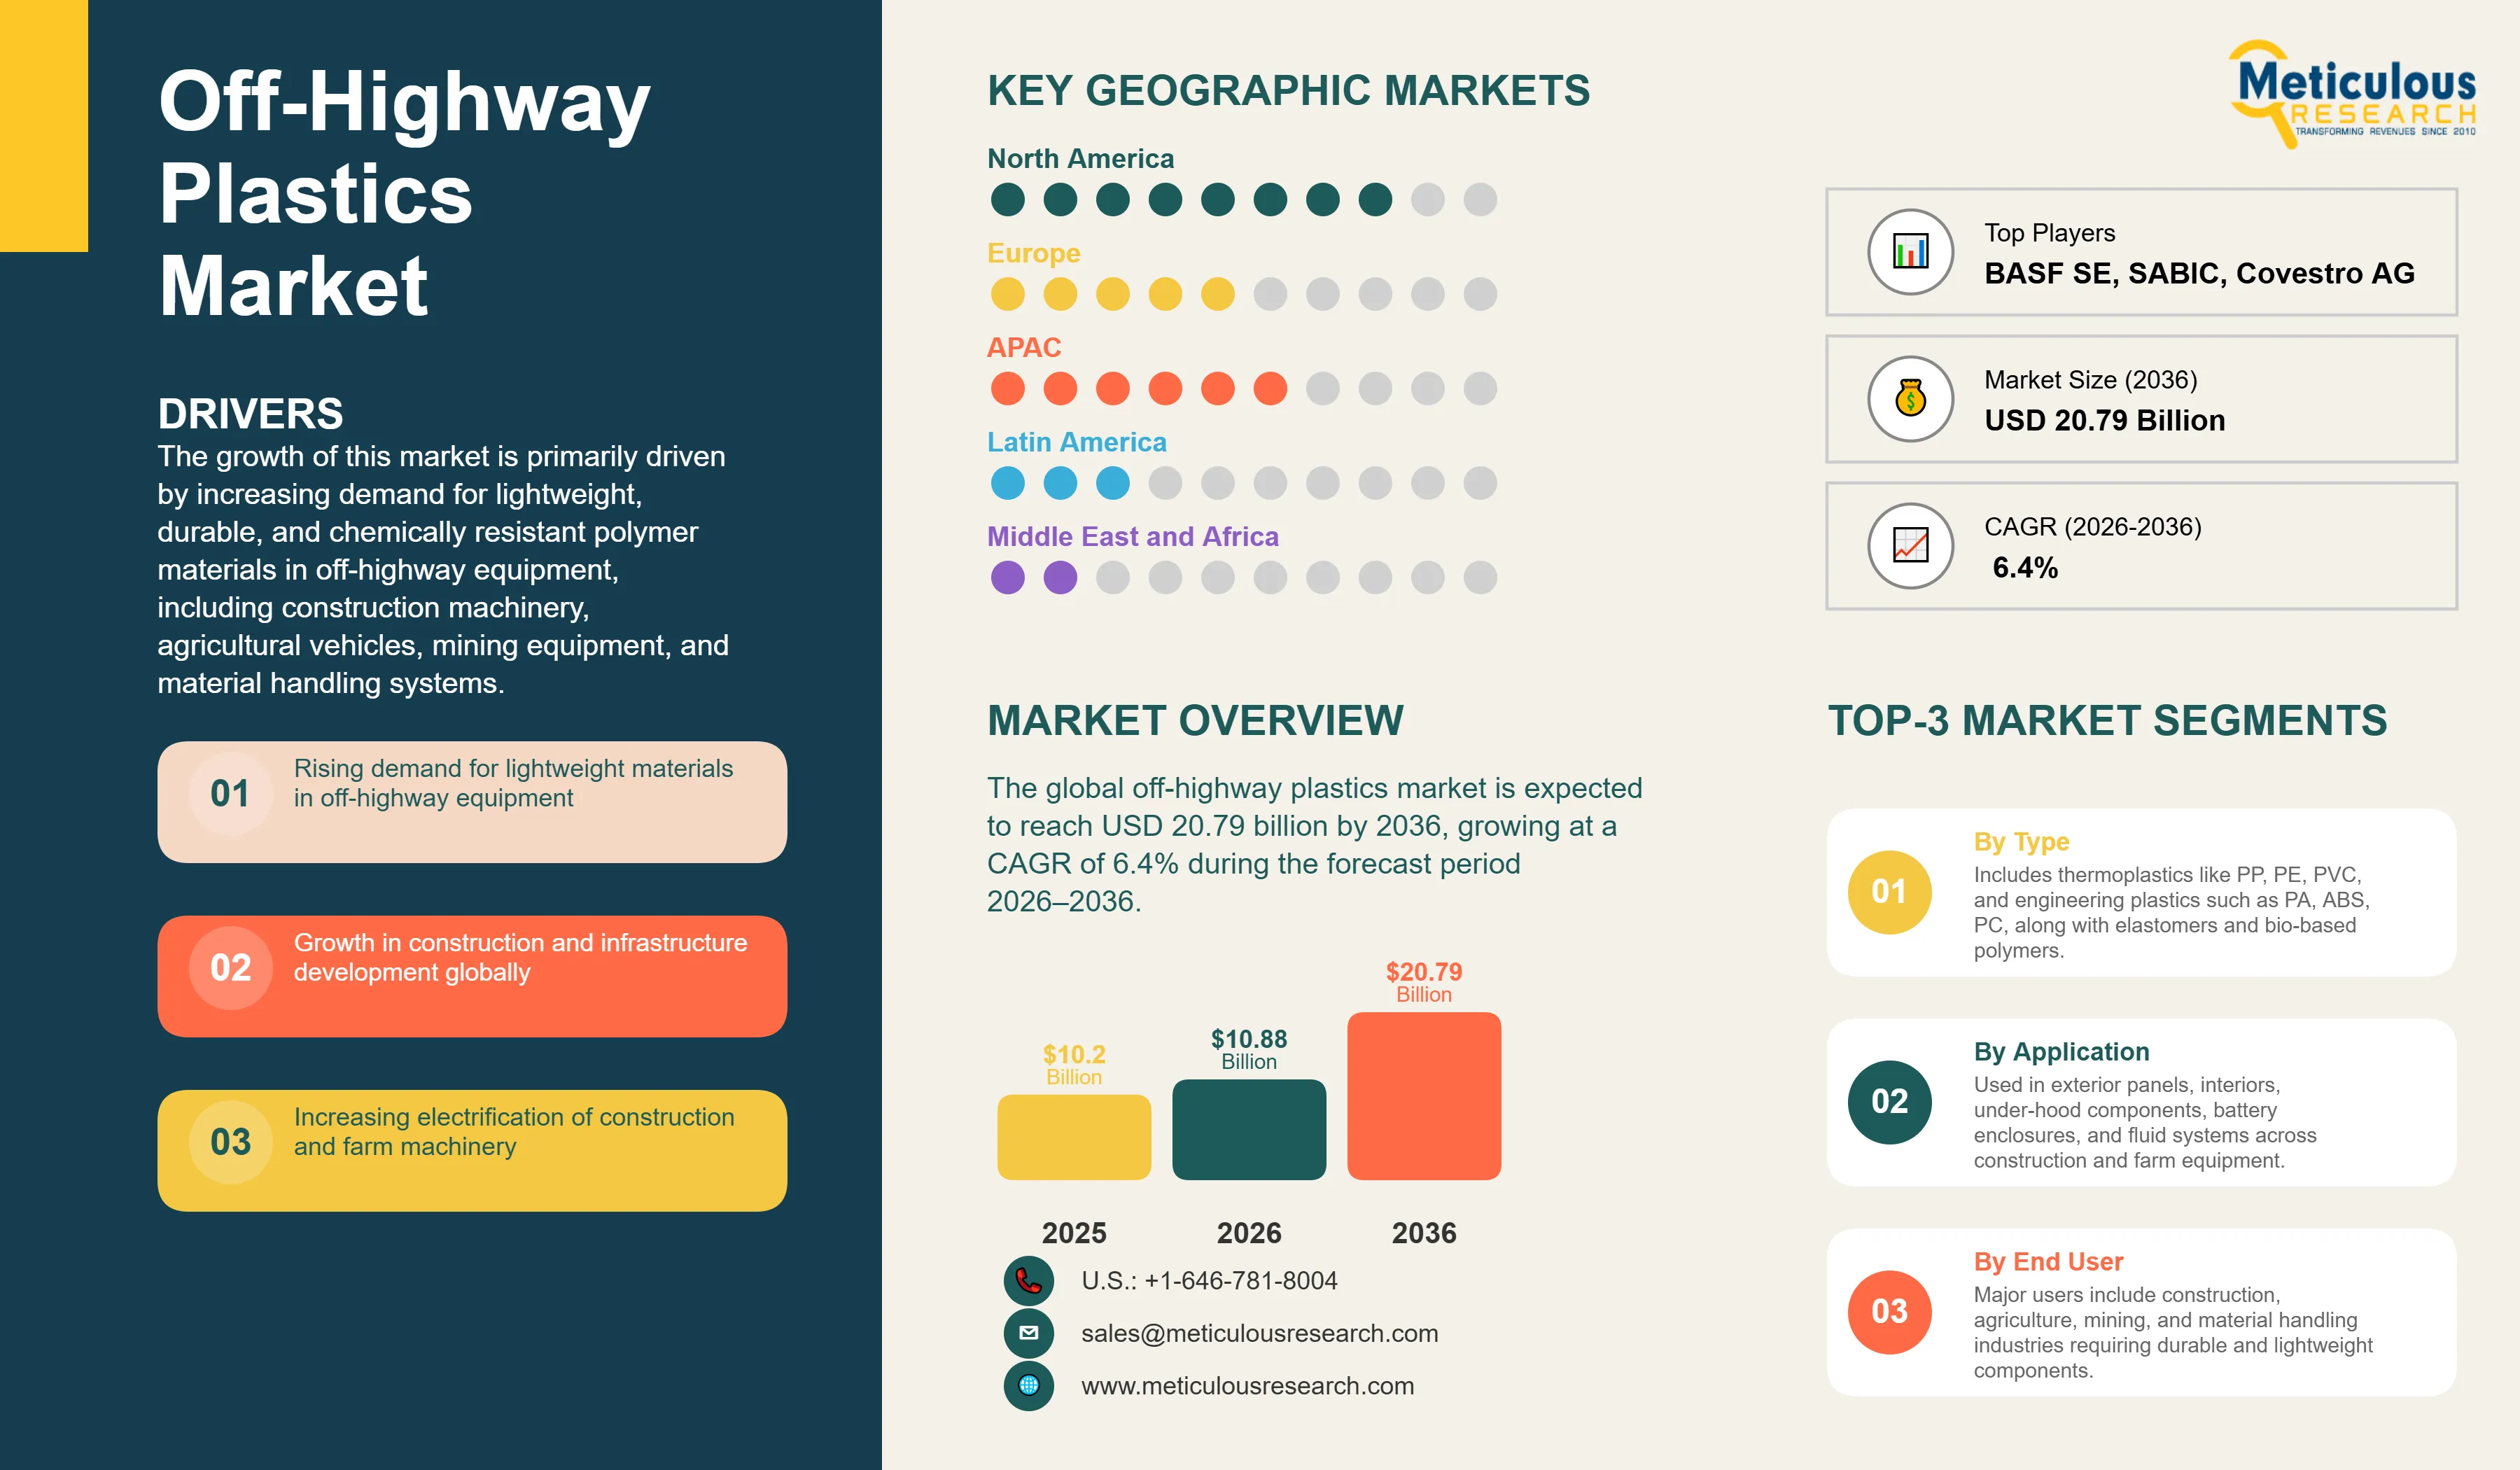
The global off-highway plastics market was valued at USD 10.2 billion in 2025. This market is expected to reach USD 20.79 billion by 2036 from an estimated USD 10.88 billion in 2026, growing at a CAGR of 6.4% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 291
- Format
- PDF + Excel
- Report ID
- MR-1867
- Base year
- 2025
- 2025 · BASELINE
- $10.20B
- 2036
- $20.79B
- CAGR 2026–2036
- 6.4%
2025 baseline · 2026–2036 forecast at 6.4% CAGR · hover a bar for the value
Key highlights
The global off-highway plastics market is projected to reach USD 20.79 billion by 2036.
The market is expected to grow at a CAGR of 6.4% during the forecast period 2026–2036.
The global off-highway plastics market was valued at USD 10.2 billion in 2025 and is estimated to reach USD 10.88 billion in 2026.
North America is expected to dominate the global off-highway plastics market with the largest market share in 2026, driven by robust construction sector activity, the presence of leading off-highway OEMs including Caterpillar, John Deere, CNH Industrial, and Komatsu North America, and substantial investment in infrastructure modernization under the U.S. Infrastructure Investment and Jobs Act.
Asia Pacific is expected to witness the fastest growth during the forecast period, driven by massive infrastructure development programs in China, India, and Southeast Asia, rapid expansion of agricultural mechanization across emerging economies, and the region's established role as the world's primary manufacturing hub for off-highway equipment and polymer components.
By material type, polypropylene (PP) is expected to hold the largest market share in 2026, owing to its superior balance of mechanical performance, chemical resistance, processability, lightweight properties, and cost-effectiveness across all off-highway end-use applications including dashboards, fenders, engine covers, fluid reservoirs, and interior trim.
By material type, bio-based plastics are expected to register the highest CAGR during the forecast period, driven by accelerating OEM sustainability commitments, tightening regulatory requirements for recycled and renewable content in industrial equipment, and the improving price competitiveness of bio-based polyamides, bio-PE, and bio-PP grades from BASF, Arkema, and Evonik.
By process type, injection molding is expected to hold the largest market share in 2026, reflecting its dominance in high-volume production of complex precision plastic components, including dashboards, fenders, engine covers, and structural housings, with tight dimensional tolerances and excellent surface finish for off-highway equipment.
By process type, additive manufacturing (3D printing) is expected to register the fastest growth during the forecast period, driven by rapid adoption for tooling, prototyping, and small-volume custom replacement part production across construction, agricultural, and mining equipment maintenance operations.
By end user, the construction segment is expected to hold the largest market share in 2026, while the agriculture segment is projected to grow at the fastest CAGR from 2026 to 2036, driven by the growing adoption of precision agriculture technology and the electrification of agricultural equipment platforms.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 20.79 Billion |
| Market Size in 2026 | USD 10.88 Billion |
| Market Size in 2025 | USD 10.2 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 6.4% |
| Format | PDF, Excel & Cloud Portal · 291 pages |
| Dominating Material Type | Polypropylene (PP) |
| Fastest Growing Material Type | Bio-based Plastics |
| Dominating Process Type | Injection Molding |
| Fastest Growing Process Type | Additive Manufacturing / 3D Printing |
| Dominating End User | Construction |
| Fastest Growing End User | Agriculture |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: material, process, end user.
The growth of this market is primarily driven by increasing demand for lightweight, durable, and chemically resistant polymer materials in off-highway equipment, including construction machinery, agricultural vehicles, mining equipment, and material handling systems. Plastics are increasingly replacing conventional metals to reduce equipment weight, enhance fuel efficiency, lower lifecycle maintenance costs, and support compliance with evolving emissions and sustainability regulations.
The global off-highway plastics market comprises a wide range of polymer materials, such as commodity thermoplastics such as polypropylene (PP), polyethylene (PE), and polyvinyl chloride (PVC); engineering thermoplastics such as polyamide (PA), polycarbonate (PC), acrylonitrile butadiene styrene (ABS), and polyoxymethylene (POM); thermoplastic elastomers (TPE); and bio-based polymers. These materials are processed through injection molding, extrusion, blow molding, compression molding, and additive manufacturing to produce structural and functional components for off-highway vehicles.
Off-highway equipment includes construction machinery (e.g., excavators, wheel loaders, bulldozers, motor graders, and concrete mixers), agricultural machinery (e.g., tractors, combine harvesters, sprayers, and seeding equipment), mining equipment (e.g., haul trucks, drilling systems, and continuous miners), and material handling equipment (e.g., forklifts, reach stackers, telehandlers, and automated guided vehicles).
Within these applications, plastics perform critical roles across exterior components (fenders, hoods, and side panels), interior cabin systems (dashboards, instrument panels, door trims, and seating structures), under-hood applications (fluid reservoirs, cooling system components, air intake ducts, and cable management systems), and semi-structural housings (including battery enclosures in electric equipment, hydraulic system components, and gearbox covers).
The increasing electrification of off-highway equipment is a major growth driver, as battery-electric and hybrid machinery require higher volumes of high-performance plastics for applications such as battery enclosures, high-voltage cable insulation and conduits, thermal management systems, and select structural components compared to internal combustion engine (ICE)-based platforms.
In addition, the expanding global infrastructure investment pipeline, mainly across Asia-Pacific, the Middle East, and North America, is driving demand for construction equipment, while the growing emphasis on food security and precision agriculture is driving the expansion of agricultural equipment fleets and increasing plastic content per machine in advanced farming systems.
However, market growth is restrained by volatility in petrochemical feedstock prices, which impacts polymer production costs, and increasing regulatory pressure around plastic waste management, recycling, and end-of-life disposal in industrial applications.
Key opportunities include the rising adoption of bio-based and recycled-content engineering plastics aligned with OEM sustainability commitments and regulatory frameworks such as the European End-of-Life Vehicles Directive; the increasing use of additive manufacturing (3D printing) for rapid prototyping and low-volume, customized components; and advancements in glass fiber- and carbon fiber-reinforced polymer composites enabling partial substitution of metals in semi-structural and structural applications.
Furthermore, the ongoing transition from conventional diesel-powered equipment toward battery-electric and, to a lesser extent, hydrogen fuel cell-based platforms is a major trend driving material selection and design requirements across the global off-highway plastics market.
Report infographic
Market dynamics
3 factors across 1 forceElectrification of Off-Highway Equipment Driving Fundamental Material Specification Shift
The increasing electrification of construction, agricultural, and material handling equipment is a key trend transforming material requirements across the off-highway plastics market. Battery-electric platforms necessitate advanced engineering plastics with performance characteristics beyond those required in conventional internal combustion engine (ICE) equipment. These include high-temperature polyamide and specialty polycarbonate grades for battery enclosures and thermal management systems, capable of maintaining structural integrity at elevated operating temperatures (typically ~80–150°C) while ensuring electrical insulation for high-voltage applications.
In addition, glass fiber-reinforced polypropylene and polyamide are increasingly utilized in lightweight structural components and battery support structures, enabling partial substitution of metal parts with significant weight reduction benefits. Thermoplastic elastomers are also gaining traction in high-voltage cable insulation and sealing applications, where durability, flexibility, and compliance with stringent electrical safety standards are critical.
Leading OEM initiatives, including electric equipment programs from Volvo Construction Equipment, Caterpillar, and CNH Industrial, are driving the adoption of these advanced materials at scale. Furthermore, stringent emissions regulations, such as the European Union Stage V standards and comparable frameworks in North America and Japan, are strengthening the transition toward electrified and low-emission powertrains, thereby driving demand for high-performance polymer materials in off-highway applications.
Metal Replacement and Weight Reduction Driving Engineering Polymer Adoption
The ongoing shift toward metal-to-plastic substitution in off-highway equipment, driven by the dual imperatives of weight reduction for improved fuel efficiency and emissions compliance, and cost optimization through part consolidation and design flexibility, is driving the addressable market for engineering polymers across structural and semi-structural applications traditionally dominated by steel and aluminum.
Glass fiber-reinforced polypropylene (typically ~20–40% GF content in commercial applications) is increasingly displacing metals in medium load-bearing components such as brackets, seat structures, and access panels, enabling weight reductions in the range of ~15–30% while maintaining required mechanical performance. Long glass fiber-reinforced thermoplastics (LGF-PP and LGF-PA) are gaining traction in semi-structural applications, including cab floor modules and underbody shielding systems, due to their enhanced stiffness-to-weight ratio and impact resistance.
Polyoxymethylene (POM/acetal) is widely used as a substitute for machined metals in precision components such as gears, bearing cages, and valve systems, where high dimensional stability, low friction, and wear resistance are critical. Additionally, polyamide materials, mainly PA66 and high-temperature variants, are increasingly replacing metals in fluid handling and under-hood applications, such as oil pans, coolant reservoirs, and hydraulic system components operating under elevated temperatures and chemically demanding conditions.
Bio-based and Recycled-Content Plastics Responding to OEM Sustainability Mandates
The increasing adoption of bio-based and recycled-content engineering plastics in off-highway equipment is driven by OEM sustainability commitments, including alignment with Science Based Targets initiative (SBTi) frameworks, Scope 3 emissions reduction programs, and circular economy principles, alongside tightening regulatory expectations around material sustainability in Europe and North America.
Bio-based polyamides are gaining traction in applications such as fluid handling systems, cable management, and select housings, where they offer comparable performance to fossil-based counterparts while enabling measurable reductions in product carbon footprint. Materials such as castor oil-derived polyamides and bio-attributed engineering plastics are increasingly incorporated into OEM material specifications, mainly in applications where lifecycle emissions are a key procurement criterion.
In parallel, post-consumer recycled (PCR) and post-industrial recycled (PIR) polypropylene and polyethylene are witnessing growing adoption in non-structural and semi-structural components, including exterior panels, flooring systems, and interior cabin elements. Advancements in compounding technologies are enabling higher recycled content (typically ~20–50%) while maintaining the required mechanical and durability performance for industrial applications.
Regulatory developments act as an important catalyst, although current frameworks such as the European End-of-Life Vehicles (ELV) Directive primarily apply to passenger vehicles and light-duty commercial vehicles, with limited direct applicability to off-highway equipment. However, ongoing policy discussions and broader EU sustainability initiatives, such as circular economy action plans and construction-related material regulations, are expected to indirectly influence material selection in off-highway applications.
As a result, bio-based and recycled-content plastics are emerging as key drivers of OEM sustainability strategies, supporting both regulatory alignment and voluntary carbon reduction targets across the off-highway equipment value chain.
Table of contents
11 chapters · 144 sections · 291 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Material | Polypropylene | Bio-based plastics |
| By Process Type | Injection Molding | Off-highway plastics market for additive manufacturing/3D printing |
| By End User | Construction | Off-highway plastics market for the agriculture |
By Material
- Polypropylene to Dominate the Global Off-Highway Plastics Market
- Polypropylene is expected to account for the largest market share.
- This dominance is attributed to its well-balanced property profile, making it suitable for a wide range of off-highway applications.
- It offers strong impact resistance, fatigue performance, and chemical resistance, enabling reliable operation under exposure to fuels, lubricants, moisture, dust, and variable temperature conditions typical of construction, agricultural, and mining environments.
- Its low density supports weight reduction compared to metal alternatives, while its excellent processability enables the production of complex and large components such as exterior panels, fenders, engine covers, battery housings, and interior trims.
- Additionally, polypropylene can be reinforced with glass fibers, mineral fillers, and elastomers to enhance mechanical strength and stiffness for semi-structural applications.
- Polypropylene also provides adequate electrical insulation properties for cable management and battery-related applications in electrified equipment.
- Furthermore, its cost competitiveness and well-established global supply chain support widespread adoption across OEM tiers.
- However, the bio-based plastics market is poised to grow at the fastest CAGR during the forecast period.
- This growth is driven by increasing OEM focus on sustainability, rising incorporation of bio-based or bio-attributed materials in component specifications, improving cost dynamics with scale, and the expanding availability of high-performance bio-based engineering polymers that meet the mechanical and thermal requirements of off-highway applications.
By Process Type
- Injection Molding to Hold the Largest Share
- The global off-highway plastics market is segmented by process type into injection molding, extrusion, compression molding, blow molding, additive manufacturing/3D printing, and others.
- Injection molding is projected to command the largest share due to its established dominance in high-volume manufacturing of intricate precision components such as dashboards, fenders, engine covers, structural housings, and cab interiors for off-highway equipment.
- This process excels in delivering tight tolerances, superior surface finishes, design versatility for complex geometries with integrated features, and compatibility with high-performance engineering polymers and reinforced compounds essential for rugged applications.
- Recent innovations like multi-cavity tooling, gas-assisted injection, and automated systems have boosted production speeds and material efficiency, enabling manufacturers to meet demanding mechanical, thermal, and chemical resistance requirements in harsh off-highway environments.
- These capabilities solidify injection molding's position for structural and functional parts where reliability under extreme conditions is non-negotiable.
- Meanwhile, the off-highway plastics market for additive manufacturing/3D printing is poised for the highest CAGR over the 2026–2036 forecast period.
- Its rapid growth stems from expanding roles in tooling, fixtures, and low-volume custom replacements for legacy equipment, leveraging processes like selective laser sintering (SLS) and fused deposition modeling (FDM) with advanced filaments such as PA12, PEEK, and PETG.
By End User
- Construction to Hold the Largest Share
- The global off-highway plastics market is segmented by end user into construction, agriculture, mining, and material handling.
- The construction segment is expected to account for the largest market share, driven by the extensive global fleet of equipment, including excavators, wheel loaders, motor graders, concrete mixers, and earthmoving machinery, driven by ongoing infrastructure investments across major economies.
- Plastics are widely utilized across construction equipment in operator cabins (dashboards, instrument panels, door trims), exterior components (engine covers, hoods, and side panels), hydraulic systems (reservoirs, hoses, and manifolds), and increasingly in electrified subsystems such as battery enclosures and cable management.
- Large-scale infrastructure initiatives, such as public investment programs in North America, Asia-Pacific, and the Middle East, continue to support high equipment production volumes, thereby driving consistent demand for polymer components that enable durability, corrosion resistance, and weight reduction.
- However, the off-highway plastics market for the agriculture segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the increasing adoption of precision agriculture technologies, including GPS-guided systems, autonomous machinery, and sensor-based crop monitoring, all of which require advanced plastic housings and enclosures for electronic components.
- Additionally, rising global food demand, expanding farm mechanization in emerging markets, and the gradual electrification of agricultural equipment are contributing to higher plastic content per machine, driving the transition toward lighter, more efficient, and technologically advanced farming systems.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share, primarily driven by the U.S., which is one of the largest national markets for off-highway equipment across construction, agriculture, and mining. The growth of the off-highway plastics market in North America is further supported by the strong presence of leading OEMs, including Caterpillar, John Deere, CNH Industrial, and Komatsu, which drive consistent demand for high-performance polymer components. Additionally, large-scale infrastructure investments, mainly under the U.S. Infrastructure Investment and Jobs Act, are supporting equipment demand for applications such as transportation, utilities, and logistics. Stringent emissions regulations for non-road diesel engines are also driving the transition toward electrified and low-emission equipment platforms, thereby increasing demand for advanced plastics in battery systems, electrical insulation, and lightweight structural components.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific off-highway plastics market is poised to grow at the highest CAGR during the forecast period. This growth is driven by China’s position as the largest market for construction equipment and a key global manufacturing hub, along with significant infrastructure development initiatives across India, Southeast Asia, and other emerging economies. Programs focused on transportation infrastructure, urban development, energy, and agricultural modernization are fueling demand for construction and agricultural machinery. Furthermore, rapid urbanization, population growth, and increasing mechanization in agriculture are contributing to rising demand for off-highway equipment across the region. This, in turn, is driving the adoption of lightweight, durable, and cost-effective plastic components to enhance equipment efficiency, performance, and lifecycle durability.
Competitive landscape
- BASF SE
- SABIC
- Covestro AG
- LyondellBasell Industries N.V.
- Dow Inc.
- Evonik Industries AG
- DuPont de Nemours, Inc.
- Borealis AG
- Arkema S.A.
- LANXESS AG
- Solvay
- DSM Engineering Materials
- Celanese Corporation
- Mitsubishi Chemical Corporation
- ExxonMobil Corporation
Frequently asked questions
The global off-highway plastics market is expected to reach USD 20.79 billion by 2036 from an estimated USD 10.88 billion in 2026, at a CAGR of 6.4% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Off-Highway Plastics Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1867). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/off-highway-plastics-market-6550