3D Printing Plastics Market (2025-2032)
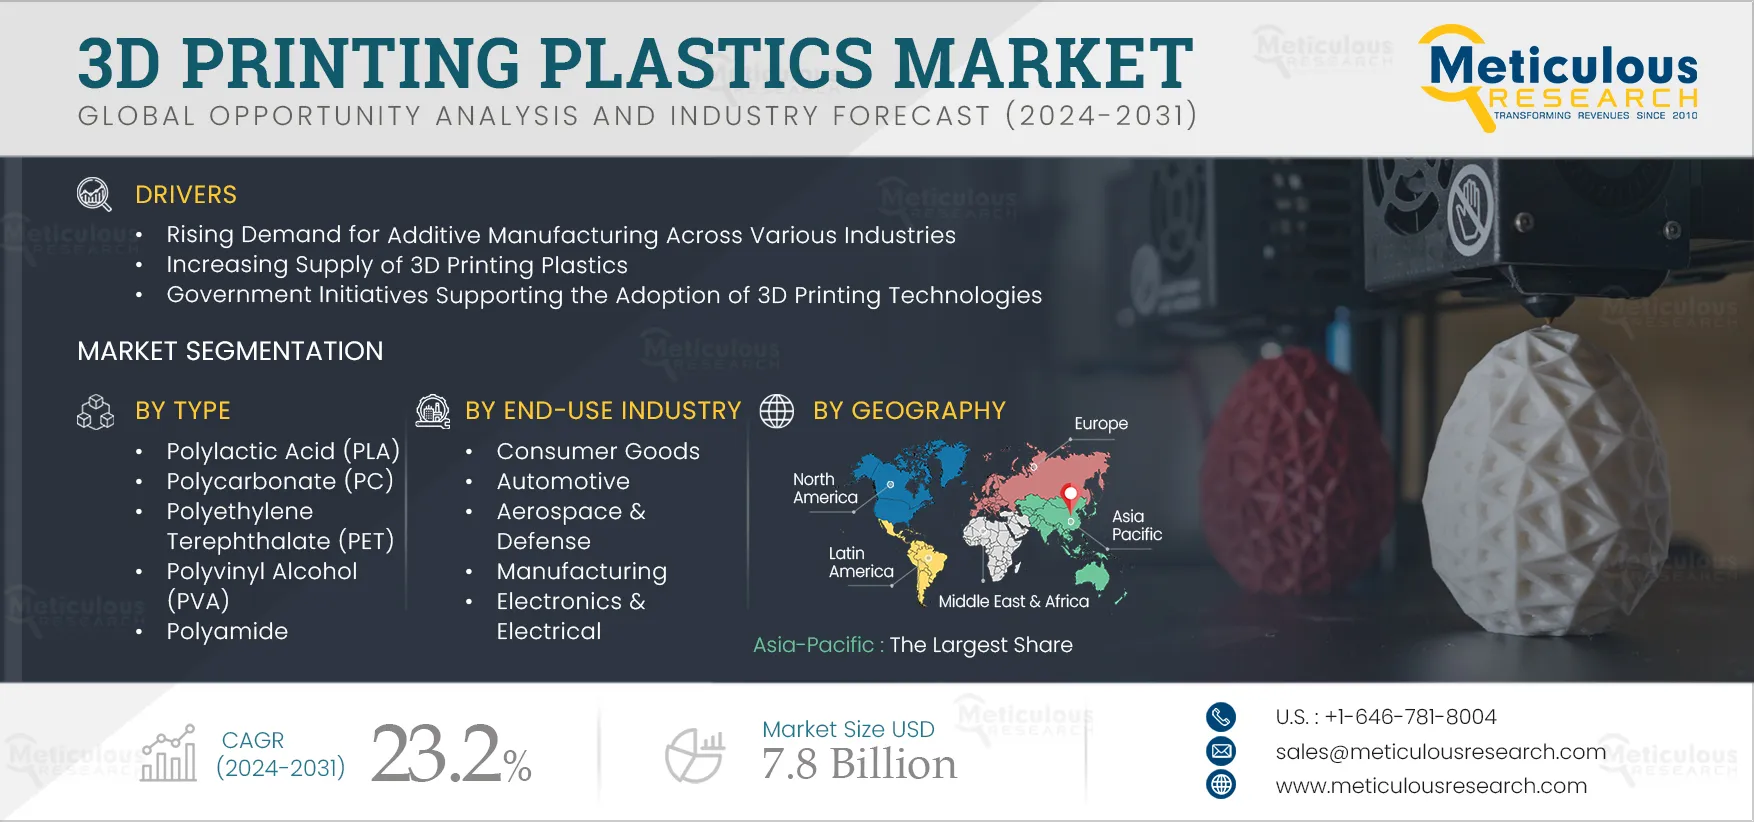
The 3D Printing Plastics Market is expected to reach $7.8 billion by 2032, at a CAGR of 23.2% from 2025 to 2032.
- Published
- Jan 2024
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRCHM - 1041267
- Base year
- 2024
- 2032 · FORECAST
- $7.80B
- 2032
- $7.80B
- CAGR 2025–2032
- 23.2%
2024 baseline · 2025–2032 forecast at 23.2% CAGR · hover a bar for the value
Key highlights
The 3D Printing Plastics Market is expected to reach $7.8 billion by 2032, at a CAGR of 23.2% from 2025 to 2032.
The 3D printing plastics market is segmented into Acrylonitrile Butadiene Styrene (ABS), Polylactic Acid (PLA), Polycarbonate (PC), Polyethylene Terephthalate (PET), Polyvinyl Alcohol (PVA), polyamide, and other 3D printing plastics.
In 2025, Asia-Pacific is expected to account for the largest share of over 42% of the 3D printing plastics market.
Report summary
| Particulars | Details |
|---|---|
| Number of Pages | 250 |
| Format | |
| Forecast Period | 2025–2032 |
| Base Year | 2024 |
| CAGR (Value) | 23.2% |
| Market Size (Value) | $7.8 Billion by 2032 |
| Segments Covered | By Type · Acrylonitrile Butadiene Styrene (ABS) · Polylactic Acid (PLA) · Polycarbonate (PC) · Polyethylene Terephthalate (PET) · Polyvinyl Alcohol (PVA) · Polyamide · Other 3D Printing Plastics · By Form · Filament · Pellets · Powder · Liquid · By Technology · Fused Deposition Modeling (FDM) · Stereolithography (SLA) · Selective Laser Sintering (SLS) · Other Technologies · By End-use Industry · Consumer Goods · Automotive · Aerospace & Defense · Manufacturing · Electronics & Electrical · Healthcare · Energy · Other End-use Industries |
| Countries Covered | North America (U.S., Canada), Europe (Germany, U.K., France, Italy, Spain, Russia, Rest of Europe), Asia-Pacific (Japan, China, India, South Korea, Rest of Asia-Pacific), Latin America (Mexico, Brazil, Rest of Latin America), and the Middle East & Africa (UAE, Israel, Rest of Middle East & Africa) |
| Key Companies Profiled | 3D Systems Corporation (U.S.), Evonik Industries AG (Germany), Arkema (France), SABIC (Saudi Arabia), Stratasys Ltd. (U.S.), Materialise nv (Belgium), CRP TECHNOLOGY S.r.l. (Italy), Formlabs Inc. (U.S.), HP Development Company, L.P. (U.S.), Dassault Systemes (France), Proto Labs, Inc. (U.S.), EOS GmbH (Germany), Avient Corporation (U.S.), Henkel AG & Co. KGaA (Germany), and Huntsman International LLC (U.S.) |
Report overview
Segments covered: type, form, technology, end-use industry. Regions: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa.
The growth of the 3D printing plastics market is primarily driven by the rising demand for additive manufacturing across various industries, the increasing supply of 3D printing plastics, and government initiatives supporting the adoption of 3D printing technologies. Moreover, advancements in 3D printing technologies and the rising demand for bio-based plastics are expected to generate growth opportunities for the players operating in this market.
Report infographic
Market dynamics
4 factors across 2 forcesRising Demand for Additive Manufacturing Across Various Industries Driving Market Growth
The growing demand for additive manufacturing in the production of functional end-use parts is driving the 3D printing plastics market. Additive manufacturing capabilities for producing functional end-use parts have expanded across various industries, including aerospace, automotive, healthcare, and consumer goods. Governments are undertaking initiatives to promote additive manufacturing across industries to enable manufacturers to produce parts that meet stringent performance requirements. In May 2022, the U.S. government launched the Additive Manufacturing Forward (AM Forward) initiative to help smaller U.S.-based businesses produce and sell higher-performing parts, shorten lead firms’ wait times for needed parts, and expand consumers’ access to better products through the use of additive manufacturing.
Also, the development of new materials suitable for 3D printing has been pivotal in enabling the production of functional end-use parts. These materials include plastics that offer a balance of properties such as strength, durability, heat resistance, and chemical resistance, making them suitable for a broad range of applications. As material science continues to evolve, further improvements in the performance and suitability of plastic for end-use parts can be expected. By eliminating the need for tooling, reducing material waste, and streamlining production processes, companies can increase efficiency and reduce production costs. These benefits are increasing the use of additive manufacturing across industries, driving the demand for 3D printing plastics.
Government Initiatives Supporting the Adoption of 3D Printing Technologies Driving the Demand for 3D Printing Plastics
Governments around the world have recognized the potential of 3D printing technologies and are launching various initiatives to support their adoption. China has witnessed a significant rise in the availability and adoption of 3D printing services. Chinese companies are now turning to 3D printing to create prototypes, customized products, and medical implants. The Chinese government has implemented a series of measures to promote the development of the 3D printing industry in the country. Also, additive manufacturing has gained significant acceptance in the Japanese market, with Japanese companies relying on 3D-printed replacement parts for older models of household appliances and classic cars. In addition, Japan is facing a labor shortage and, therefore, is focused on training its next generation of employees. Hence, the Japanese government is promoting 3D printing technologies among manufacturing companies to overcome mass production and workforce challenges.
Some of the recent government initiatives in the 3D printing space are as follows:
- In June 2024, the U.K. government invested $14.67 million (€13.7 million) in innovative U.K.-based 3D printing companies to enable them to make manufacturing more efficient and create 3D-printed products from recycled materials.
- In August 2024, the Government of Canada invested $20.8 million in seven Burnaby-based businesses and organizations to provide them with access to 3D printing technology, helping them scale up operations and create jobs.
Thus, increasing government initiatives supporting the adoption of additive manufacturing are driving the 3D printing plastics market.
Table of contents
12 chapters · 115 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2025) | Fastest growth (2025–2032) |
|---|---|---|
| By Type | Polylactic acid (PLA) | Polyamide |
| By Form | Filament | — |
| By Technology | Fused deposition modeling (FDM) | — |
| By End-use Industry | Manufacturing | Healthcare |
By Type
- The 3D printing plastics market is segmented into Acrylonitrile Butadiene Styrene (ABS), Polylactic Acid (PLA), Polycarbonate (PC), Polyethylene Terephthalate (PET), Polyvinyl Alcohol (PVA), polyamide, and other 3D printing plastics.
- The polylactic acid (PLA) segment is expected to account for the largest share of over 33% of the 3D printing plastics market.
- The large market share of this segment is attributed to the rising demand for bioplastics, favorable government initiatives, the performance benefits of PLA, and the rising adoption of PLA in the healthcare sector.
- In April 2025, Filamentive Limited (U.K.) launched a PLA 3D Printing waste recycling service to combat plastic pollution caused due to FDM 3D printing.
- However, the polyamide segment is projected to register the highest CAGR during the forecast period.
- The segment's growth is driven by the increasing use of polyamide in the automotive and aerospace sectors due to its high strength, the growing focus on eco-friendly manufacturing solutions, and the increasing use of polyamide in consumer goods manufacturing.
By Form
- The 3D printing plastics market is segmented into filament, pellets, powder, and liquid.
- The filament segment is expected to account for the largest share of over 71% of the 3D printing plastics market.
- The large market share of this segment is attributed to the growing use of 3D printing filaments for manufacturing commercial and military aircraft and the increasing use of filament materials in prototyping applications.
- Moreover, several key players are focusing on the development of materials in filament form for the 3D printing of medical implants.
- For instance, in October 2024, Evonik Industries AG (Germany) launched the 'world's first' carbon-fiber-reinforced PEEK filament for use in 3D-printed long-term medical implants.
- Moreover, this segment is also projected to register the highest CAGR during the period.
By Technology
- The 3D printing plastics market is segmented into Fused Deposition Modeling (FDM), Stereolithography (SLA), Selective Laser Sintering (SLS), and other technologies.
- The fused deposition modeling (FDM) segment is expected to account for the largest share of the 3D printing plastics market.
- The large market share of this segment is attributed to the increasing use of FDM for small-batch and customized parts production, the increasing use of FDM by educational institutes, and the better affordability and user-friendliness of FDM compared to other technologies.
- Moreover, this segment is also projected to register the highest CAGR during the period.
By End-use Industry
- The 3D printing plastics market is segmented into consumer goods, automotive, aerospace & defense, manufacturing, electronics & electrical, healthcare, energy, and other end-use industries.
- The manufacturing segment is expected to account for the largest share of over 26% of the 3D printing plastics market.
- The large market share of this segment is attributed to the growing use of 3D printing for mass production in industrial manufacturing, the increasing focus of manufacturers on reducing costs and lead times, and the increasing use of 3D-printed composite materials in manufacturing applications.
- In November 2024, Velo3D, Inc. (U.S.) announced that Atomic Industries (U.S.) purchased a fully integrated metal additive manufacturing solution to provide its customers with 3D-printed tooling and dies.
- However, the healthcare segment is projected to register the highest CAGR during the period.
- The segment's growth is driven by the increasing use of 3D printing plastics for creating personalized medical devices, advancements in 3D printing materials, and the increasing development of biocompatible plastics for 3D printing of implants, scaffolds for tissue regeneration, and custom-made drugs.
Geographic analysis
Asia-Pacific
Largest shareIn 2025, Asia-Pacific is expected to account for the largest share of over 42% of the 3D printing plastics market. Asia-Pacific’s large market share is attributed to increased R&D funding, the growing adoption of Industry 4.0, the growing utilization of 3D printing technologies in the healthcare, construction, and education sectors, and increasing government-led strategies & policies supporting the adoption of 3D printing technologies. Moreover, this region is also projected to record the highest CAGR of over 25% during the forecast period. In May 2021, Farsoon Technologies Co., Ltd (China) partnered with Japan 3D Printer Co., Ltd. (Japan) to expand its business in Japan. The company installed Farsoon’s high-temperature HT403P 3D printer at Japan 3D Printer’s Demo Center to offer industrial SLS technology.
Competitive landscape
- June 2024
Procter & Gamble (Hong Kong) and Watsons (Hong Kong) partnered with MakerBay Foundation Limited (Hong Kong) to repurpose and transform plastics into 3D printing materials suitable for use in general primary and secondary schools.
- June 2022
3D Systems, Inc. (U.S.) signed a Memorandum of Understanding (MoU) with AIPMA (India) to promote the use of additive manufacturing in the plastics industry.
- 3D Systems Corporation (U.S.)
- Evonik Industries AG · Germany
- Arkema · France
- SABIC · Saudi Arabia
- Stratasys Ltd. (U.S.)
- Materialise nv · Belgium
- CRP TECHNOLOGY S.r.l · Italy
- Formlabs Inc. (U.S.)
- HP Development Company
- L.P. (U.S.)
- Dassault Systemes · France
- Proto Labs, Inc. (U.S.)
- EOS GmbH · Germany
- Avient Corporation (U.S.)
- Henkel AG & Co. KGaA · Germany
- Huntsman International LLC (U.S.)
Frequently asked questions
The 3D printing plastics market study focuses on market assessment and opportunity analysis based on the sales of 3D printing plastics across different regions, countries, and market segments. This study also includes a competitive analysis based on an extensive assessment of the leading players’ product portfolios, geographic presence, and key growth strategies adopted in the last 3 to 4 years.
Cite this report
Meticulous Research. (2024). 3D Printing Plastics Market - Global Opportunity Analysis and Industry Forecast (2025-2032) (Report No. MRCHM - 1041267). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/3d-printing-plastics-market-5950