Electric Aviation Market (2026-2036)
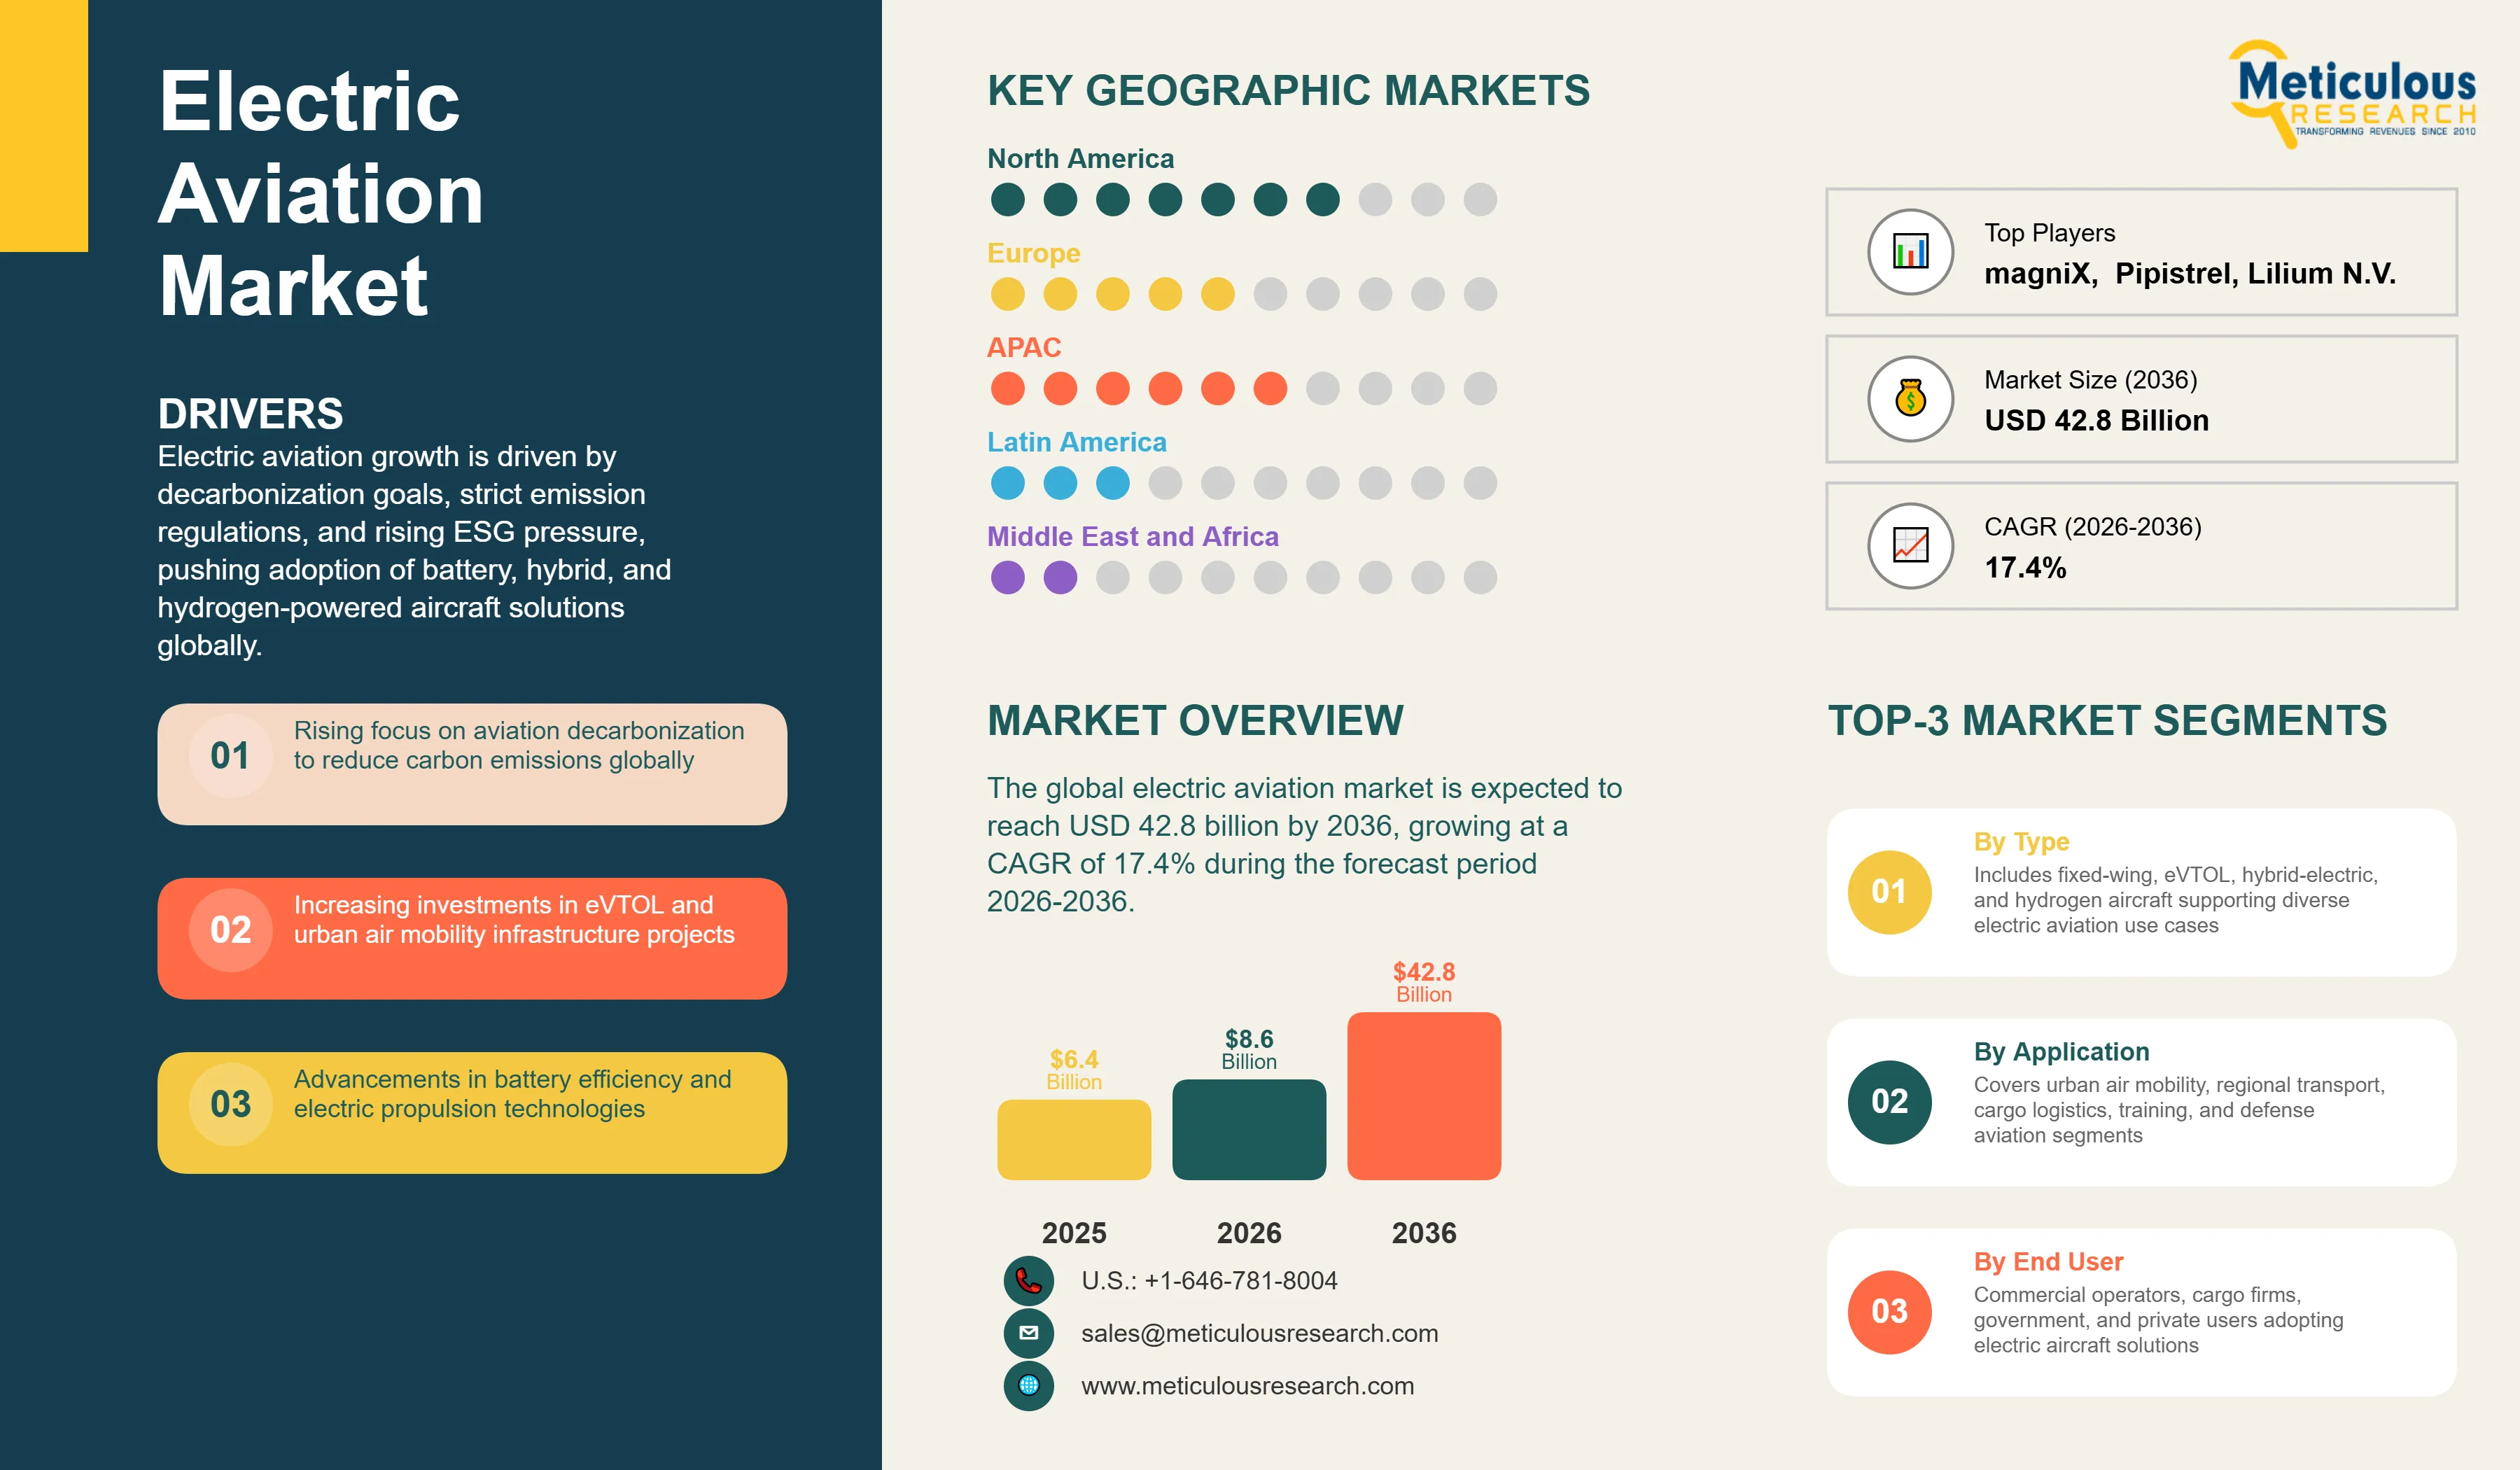
The global electric aviation market was valued at USD 6.4 billion in 2025. This market is expected to reach USD 42.8 billion by 2036 from an estimated USD 8.6 billion in 2026, growing at a CAGR of 17.4% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 265
- Format
- PDF + Excel
- Report ID
- MR-1898
- Base year
- 2025
- 2025 · BASELINE
- $6.40B
- 2036
- $42.80B
- CAGR 2026–2036
- 17.4%
2025 baseline · 2026–2036 forecast at 17.4% CAGR · hover a bar for the value
Key highlights
The global electric aviation market is projected to reach USD 42.8 billion by 2036.
The market is expected to grow at a CAGR of 17.4% during the forecast period 2026-2036.
The global electric aviation market was valued at USD 6.4 billion in 2025 and is estimated to reach USD 8.6 billion in 2026.
North America is expected to dominate the global electric aviation market with the largest market share in 2026, while Asia-Pacific is projected to register the highest CAGR during the forecast period.
By aircraft type, the fixed-wing electric aircraft segment is expected to hold the largest share of the global market in 2026, while the rotary-wing electric aircraft (eVTOL) segment is projected to register the highest CAGR during the forecast period.
By propulsion type, the fully electric propulsion segment is expected to hold the largest share in 2026, while the hydrogen-electric propulsion segment is projected to register the highest CAGR during the forecast period.
By range, the short range segment is expected to hold the largest share in 2026, while the medium range segment is projected to register the highest CAGR during the forecast period.
By application, the urban air mobility segment is expected to hold the largest share in 2026, while the cargo and logistics segment is projected to register the highest CAGR during the forecast period.
By end user, the commercial operators segment is expected to hold the largest share in 2026, while the cargo operators segment is projected to register the highest CAGR during the forecast period.
By seating capacity, the 1-2 passengers segment is expected to hold the largest share in 2026, while the 7-10 passengers segment is projected to register the highest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 42.8 Billion |
| Market Size in 2026 | USD 8.6 Billion |
| Market Size in 2025 | USD 6.4 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 17.4% |
| Format | PDF, Excel & Cloud Portal · 265 pages |
| Dominating Aircraft Type | Fixed-Wing Electric Aircraft |
| Fastest Growing Aircraft Type | Rotary-Wing Electric Aircraft (eVTOL) |
| Dominating Propulsion Type | Fully Electric Propulsion |
| Fastest Growing Propulsion Type | Hydrogen-Electric Propulsion |
| Dominating Range | Short Range (<100 km) |
| Fastest Growing Range | Medium Range (100-500 km) |
| Dominating Application | Urban Air Mobility (Air Taxis) |
| Fastest Growing Application | Cargo & Logistics |
| Dominating End User | Commercial Operators |
| Fastest Growing End User | Cargo Operators |
| Dominating Seating Capacity | 1-2 Passengers |
| Fastest Growing Seating Capacity | 7-10 Passengers |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: aircraft type, propulsion type, end user.
The global electric aviation market covers the design, development, manufacturing, certification, and commercial operation of aircraft powered wholly or substantially by electric propulsion systems, including fully battery-electric fixed-wing aircraft and eVTOL platforms, hybrid-electric aircraft combining battery-electric and conventional propulsion for extended range, and hydrogen-electric aircraft utilizing fuel cell or direct hydrogen combustion propulsion. The market encompasses the aircraft platforms themselves together with the electric propulsion systems, battery packs, power electronics, charging infrastructure, and vertiport ground infrastructure that constitute the complete electric aviation ecosystem from component supply through commercial operation.
The growth of the global electric aviation market is primarily driven by the aviation industry's urgent decarbonization imperative in the face of growing regulatory pressure and investor ESG expectations, as aviation accounts for approximately 2.5% of global CO2 emissions and faces the most technically challenging decarbonization pathway of any major transport sector. The FAA and EASA certification progress on eVTOL aircraft, with Joby Aviation, Archer Aviation, and Vertical Aerospace advancing through the certification process toward anticipated type certificate issuance in the 2025 to 2027 timeframe, is translating the electric aviation technology pipeline into near-term commercial product launches that are creating the first significant revenue generation phase of the market. The extraordinary level of venture capital and strategic investment in eVTOL and electric aircraft developers, with cumulative investment exceeding USD 10 billion across the sector, is funding the technology development and certification programs required to bring commercial electric aviation products to market at scale.
Two significant opportunities are shaping the market's long-term trajectory. The development of hybrid-electric aircraft for regional travel, combining battery-electric power for takeoff and initial climb with conventional engine power for cruise, represents the most commercially actionable near-term pathway for extending electric aviation beyond the short-range and urban air mobility applications addressable with current battery technology, enabling the development of competitive regional air transport products in the 100 to 500 kilometer range that represent the largest commercial opportunity in the electric aviation market. The expansion of dedicated electric cargo and logistics aircraft, addressing the exploding last-mile and middle-mile air cargo demand generated by e-commerce growth with zero-emission electric aircraft optimized for freight transport rather than passenger comfort, represents a commercially compelling application where the operating economics of electric propulsion and the logistics industry's decarbonization commitments are creating strong operator demand ahead of passenger air taxi certification timelines.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Focus on Sustainable Aviation and Decarbonization
The primary driver of the global electric aviation market is the aviation industry's urgent and growing pressure to decarbonize its operations in response to climate policy commitments, regulatory requirements, and the increasing cost of carbon under emissions trading systems that are making the environmental and financial case for electric aviation transition increasingly compelling for operators and investors. Aviation's contribution to global warming encompasses not only its approximately 2.5% share of global CO2 emissions but also additional non-CO2 climate effects from high-altitude contrail cirrus formation that potentially doubles its effective climate impact, making aviation one of the most consequential sectors for decarbonization despite its relatively modest CO2 share. The International Civil Aviation Organization's Long-Term Aspirational Goals framework targeting net-zero carbon aviation by 2050, the EU Emissions Trading System's inclusion of intra-EU aviation, and national net-zero commitments with aviation sector decarbonization plans in the UK, France, Netherlands, and Scandinavia are creating the regulatory and policy environment that is incentivizing airlines, aircraft manufacturers, and investors to accelerate electric aviation development and adoption.
Rising Investment in Urban Air Mobility (UAM)
The extraordinary level of investment flowing into the urban air mobility sector, with eVTOL and electric aircraft developers collectively raising over USD 10 billion in venture capital, strategic investment, and public market capital through 2024, is the primary commercial development driver of the electric aviation market, funding the technology development, flight test programs, and certification activities required to bring commercial eVTOL products to market. Infrastructure investment in vertiport networks from companies including Skyports, Urban-Air Port, and Ferrovial, and committed airline and air taxi operator customer agreements from United Airlines, American Airlines, Delta Air Lines, American Airlines, and Virgin Atlantic for eVTOL aircraft from Joby, Archer, Vertical Aerospace, and Lilium collectively demonstrate that the commercial ecosystem required for urban air mobility service launch is being assembled in parallel with aircraft development programs. The UAM market is projected to develop first in high-density urban markets where road congestion creates the time-saving value proposition that justifies premium air taxi pricing, including Los Angeles, San Francisco, New York, London, Singapore, and Dubai, with each market representing a defined near-term commercial launch opportunity for leading eVTOL operators.
Table of contents
14 chapters · 173 sections · 265 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Aircraft Type | Fixed-Wing Electric Aircraft | Rotary-wing electric aircraft segment including eVTOL platforms |
| By Propulsion Type | Fully Electric Propulsion | Hydrogen-electric propulsion |
| By Range | Short Range | Medium range segment (100 |
| By Application | Urban Air Mobility | Cargo and logistics |
| By End User | Commercial Operators | Cargo operators |
| By Seating Capacity | 1-2 Passengers | 7-10 passengers |
By Aircraft Type
- Fixed-Wing Electric Aircraft to Dominate
- The fixed-wing electric aircraft segment is expected to account for the largest share of the global electric aviation market.
- The large share of this segment is attributed to fixed-wing electric aircraft representing the most commercially mature and operationally deployed category of electric aviation, with aircraft including the Pipistrel Velis Electro receiving the first EASA type certificate for a fully electric aircraft in 2020, Eviation's Alice entering flight testing, and a large installed base of electric light sport aircraft in training and recreational applications that represents established revenue generation.
- The fixed-wing format's superior aerodynamic efficiency relative to rotary-wing designs enables the longest range achievable with current battery technology, making fixed-wing platforms the most commercially deployable category for the near-term flight training and light cargo operations that represent the initial commercial market.
- However, the rotary-wing electric aircraft segment including eVTOL platforms is poised to register the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the approaching type certification and commercial service launch of leading eVTOL platforms including Joby Aviation, Archer Aviation, and Vertical Aerospace, the extraordinary level of investment and commercial partnership activity generating strong demand signal for urban air mobility services, and the large and rapidly growing commercial market represented by urban air taxi operations in high-density cities where eVTOL's vertical takeoff capability enables operations from urban vertiports without conventional airport infrastructure.
By Propulsion Type
- Fully Electric Propulsion to Hold the Largest Share
- The fully electric propulsion segment is expected to account for the largest share of the global electric aviation market.
- The dominance of fully electric propulsion reflects the concentration of both the current installed base of electric aircraft, comprising the large population of battery-electric light sport and flight training aircraft, and the near-term commercial pipeline, comprising the eVTOL platforms approaching certification, in the fully electric propulsion category.
- The design simplicity, zero direct emission operation, and lower maintenance complexity of fully electric propulsion systems relative to hybrid alternatives make them the preferred architecture for short-range applications where battery range limitations are not operationally constraining.
- However, the hydrogen-electric propulsion segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the significant investment by Airbus in its ZEROe hydrogen aircraft programs targeting commercial service entry in the mid-2030s, the development of hydrogen fuel cell propulsion systems by ZeroAvia and Universal Hydrogen for retrofit and new aircraft applications, and the aviation industry's recognition that hydrogen is the most credible pathway for decarbonizing medium and long-range aviation beyond the range limitations that battery-electric technology imposes.
By Range
- Short Range to Hold the Largest Share
- The short range segment is expected to account for the largest share of the global electric aviation market.
- Short-range operations below 100 kilometers represent the primary application domain for current-generation battery-electric aircraft, encompassing urban air mobility routes between city-center vertiports and airports, inter-island and coastal short-hop routes, flight training operations, and aerial survey and inspection missions where the energy storage capacity of current lithium-ion battery technology provides adequate range without requiring hybrid propulsion augmentation.
- The entire eVTOL commercial launch pipeline is focused on this range segment, reinforcing its near-term market dominance.
- However, the medium range segment (100 to 500 km) is projected to register the highest CAGR during the forecast period.
- This growth is driven by the advancing development of hybrid-electric regional aircraft specifically targeting the 100 to 500 kilometer regional air transport market, the improving energy density of next-generation lithium-ion and solid-state battery technology progressively extending the fully electric range envelope toward 200 to 300 kilometers, and the very large commercial opportunity represented by regional aviation routes in this distance band that are underserved by current aircraft economics.
By Application
- Urban Air Mobility to Hold the Largest Share
- The urban air mobility segment is expected to account for the largest share of the global electric aviation market.
- UAM represents the highest-investment and most commercially active application category in electric aviation, driven by the concentration of eVTOL developer activity and commercial partner commitments around air taxi services in major urban markets, the advanced state of certification programs for UAM-configured eVTOL platforms, and the large projected addressable market for air taxi services in congested urban environments where time savings justify premium pricing.
- Joby Aviation's partnership with Delta Air Lines for airport connection services, Archer's partnership with United Airlines and Alaska Airlines, and Vertical Aerospace's orders from American Airlines and Virgin Atlantic collectively represent the commercial foundation of the near-term UAM market.
- However, the cargo and logistics segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by confirmed electric aircraft orders from major logistics operators including UPS's commitment to Beta Technologies aircraft and DHL's acquisition of Eviation Alice cargo aircraft, the favorable operating economics of electric propulsion for the predictable short-haul cargo routes that define hub-to-spoke logistics operations, and the strong corporate sustainability commitments of global logistics companies that are creating non-discretionary demand for zero-emission air freight solutions as airline operators face increasing carbon cost exposure on their aviation operations.
By End User
- Commercial Operators to Hold the Largest Share
- The commercial operators segment is expected to account for the largest share of the global electric aviation market.
- Commercial aviation operators including the airline and air taxi companies that will operate eVTOL urban air mobility services, commuter airline operators deploying electric aircraft on short-haul scheduled routes, and charter and air tour operators using electric aircraft for scenic and short-hop services represent the primary revenue-generating customer base for electric aircraft manufacturers.
- The very large pre-order books that eVTOL developers have accumulated from airline partners, including Joby's Delta partnership, Archer's United and Alaska orders, and Vertical Aerospace's American Airlines and Virgin Atlantic commitments, demonstrate the commercial operator segment's leading role in driving the market's commercial development.
- However, the cargo operators segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the confirmed aircraft purchase commitments from UPS, DHL, and Amazon Air as they invest in electric cargo aircraft to reduce the carbon footprint of their air freight operations, the favorable certification pathway for cargo aircraft compared with passenger-carrying platforms, and the strong economic incentive for logistics operators to reduce fuel cost exposure on short-haul cargo routes through electrification.
By Seating Capacity
- 1-2 Passengers to Hold the Largest Share
- The 1 to 2 passengers segment is expected to account for the largest share of the global electric aviation market.
- The dominance of the 1 to 2 passenger category reflects the large installed base of single and dual-seat electric light sport and flight training aircraft including the Pipistrel Velis Electro and equivalent platforms from PC-Aero, Bye Aerospace, and Aero Electric Aircraft Corporation that have established the earliest commercial deployments of electric aviation technology in the flight training and recreational flying markets.
- Single-seat and dual-seat electric aircraft are commercially deployed today in substantially larger numbers than any other seating category and represent the most commercially established revenue base in the market.
- However, the 7 to 10 passengers segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the commercial focus of the most capital-intensive and commercially advanced eVTOL programs on configurations in the 4 to 6 passenger range that most closely correspond to the 7 to 10 passenger category boundary, the development of electric commuter aircraft targeting the regional shuttle market, and the emerging electric helicopter market addressing offshore energy support, medical evacuation, and premium business transport applications that typically require 6 to 8 passenger capacity.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global electric aviation market. The largest share of this region is mainly due to the United States' position as the home of the majority of the world's leading eVTOL and electric aircraft developers, including Joby Aviation, Archer Aviation, Beta Technologies, Eviation Aircraft, Wisk Aero, Overair, and magniX, whose development programs, flight test activities, and certification engagements with the FAA generate the majority of current market revenue in the form of aircraft development spending, component procurement, and early aircraft deliveries. The FAA's development of the Powered-Lift Special Federal Aviation Regulation providing the certification pathway for eVTOL aircraft, combined with the large and congested metropolitan aviation markets of Los Angeles, San Francisco, New York, and Miami that represent the primary near-term commercial launch environments for urban air mobility services, positions the United States as the primary initial commercial deployment market for electric aviation. The substantial venture capital ecosystem of Silicon Valley and the broader U.S. technology investment community, which has provided the majority of the USD 10 billion-plus cumulative investment in the electric aviation sector, further reinforces North America's market leadership position.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific electric aviation market is expected to grow at the fastest CAGR during the forecast period. The region's rapid growth is driven by China's national electric aviation development programs supporting domestic eVTOL and electric aircraft companies including EHang, AutoFlight, and Aerofugia, with EHang's EH216 having received type certification from the Civil Aviation Administration of China in 2023 as the world's first eVTOL to achieve national type certification for commercial passenger operations. Japan's Society of Automotive Engineers of Japan eVTOL certification program and the Japanese government's ambitious UAM roadmap targeting commercial air taxi services launch by 2025 are driving significant private and public investment in domestic eVTOL development and infrastructure. Singapore's Civil Aviation Authority has established an advanced air mobility development framework and the city-state's compact geography and severe road congestion make it a natural early adopter market for urban air mobility services. India's nascent electric aviation market is supported by growing investor interest in air mobility solutions for its congested megacities and the Civil Aviation Ministry's Digi Yatra digital aviation platform that provides the digital infrastructure layer for future urban air mobility integration.
Europe
Europe represents a highly active electric aviation development market, anchored by Vertical Aerospace in the UK, Lilium in Germany, Volocopter in Germany, and the electric aviation programs of Airbus including E-Fan X hybrid-electric research and the ZEROe hydrogen aircraft concept program. The European Union's Green Deal aviation provisions, the UK's Jet Zero Strategy, and the advanced air mobility programs of multiple European aviation authorities are creating a favorable regulatory and policy environment for electric aviation development and early commercial operations.
Middle East & Africa
The Middle East and Africa market is experiencing growing interest in electric aviation, with Dubai's RTA and civil aviation authority establishing an air mobility regulatory framework and Abu Dhabi's demonstration of eVTOL trial flights, positioning the UAE as a leading Middle East electric aviation adoption market motivated by its smart city development ambitions and aviation technology leadership aspirations.
Competitive landscape
- Joby Aviation Inc. (U.S.)
- Lilium N.V. · Germany
- Archer Aviation Inc. (U.S.)
- Eviation Aircraft Ltd. (Israel/U.S.)
- Vertical Aerospace Ltd. (U.K.)
- Beta Technologies (U.S.)
- Airbus SE · Netherlands
- Boeing Company (U.S.)
- Embraer S.A./Eve Air Mobility · Brazil
- Pipistrel d.o.o · Slovenia
- Rolls-Royce Holdings plc (U.K.)
- Honeywell International Inc. (U.S.)
- Wright Electric Inc. (U.S.)
- VoltAero S.A.S · France
Frequently asked questions
The global electric aviation market is expected to reach USD 42.8 billion by 2036 from an estimated USD 8.6 billion in 2026, at a CAGR of 17.4% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Electric Aviation Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1898). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/electric-aviation-market-6581