Electric Powertrain Market (2026-2036)
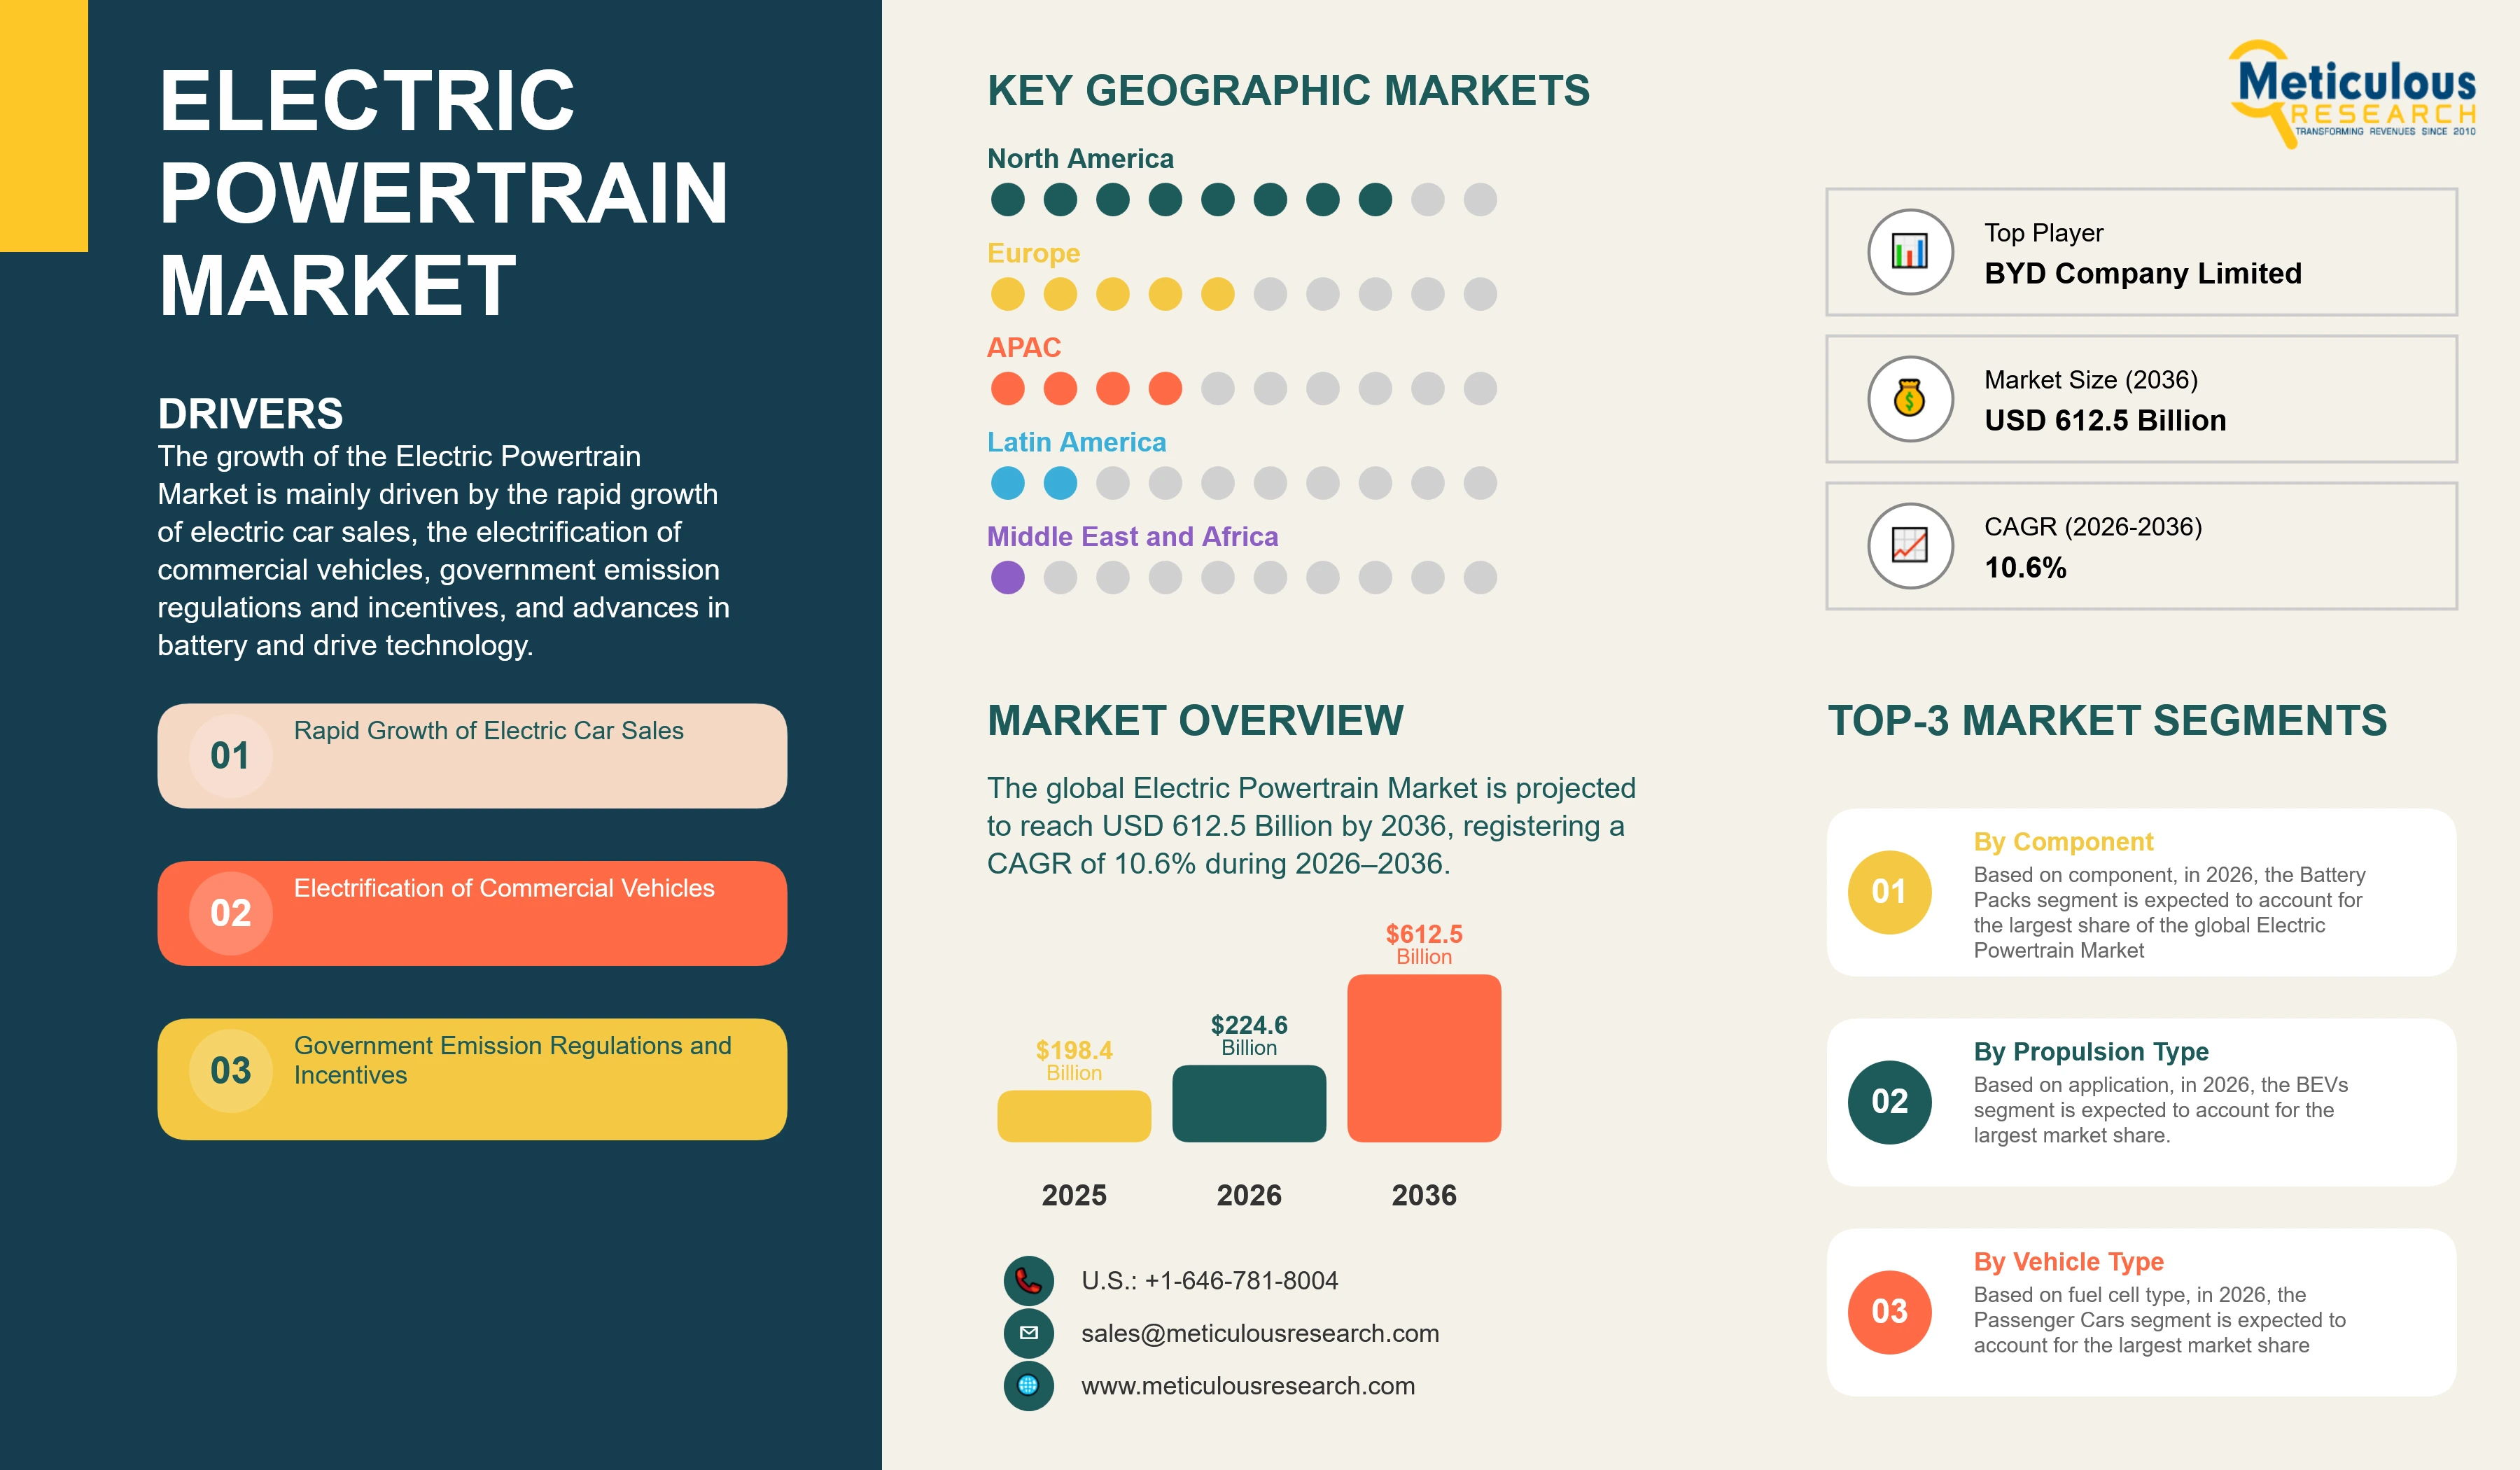
The global Electric Powertrain Market was valued at USD 198.4 billion in 2025. This market is expected to reach USD 612.5 billion by 2036 from an estimated USD 224.6 billion in 2026, registering a CAGR of 10.6% during the forecast period (2026-2036).
- Published
- Oct 2026
- Pages
- 250
- Format
- PDF + Excel
- Report ID
- MRAUTO - 1041167
- Base year
- 2025
- 2025 · BASELINE
- $198.4B
- 2036
- $612.5B
- CAGR 2026–2036
- 10.6%
2025 baseline · 2026–2036 forecast at 10.6% CAGR · hover a bar for the value
Key highlights
The global Electric Powertrain Market is projected to reach USD 612.5 billion by 2036, driven by electric car adoption, commercial vehicle electrification, emission regulations, and advances in drive and battery technology.
Asia-Pacific is expected to account for the largest market share in 2026, while Europe is projected to register the fastest growth during the forecast period. China sold more than 13 million electric cars in 2025, nearly 55% of new car sales, Europe sold 4.2 million, or 28% of new car sales, and the U.S. sold around 1.5 million, or roughly 10% of new car sales, according to the IEA.
By component, Battery Packs are expected to account for the largest market share in 2026, whereas Integrated e-Axles & Electric Drive Units are projected to witness the fastest growth through 2036. In September 2026, Bosch unveiled a rigid eAxle for heavy commercial vehicles of 18 to 49 tonnes, paired with silicon carbide inverters with up to 99% efficiency.
Commercial vehicles are electrifying rapidly. According to the IEA, electric truck sales roughly doubled to more than 400,000 in 2025, reaching 9% of all truck sales, electric bus sales rose 12% to almost 70,000, electric van sales rose 45% to more than 430,000, and electric two- and three-wheeler sales reached around 11 million.
Hybrid powertrains are gaining importance alongside BEVs. Schaeffler reported 2025 E-Mobility division revenue of EUR 5,015 million, up 7.0% at constant currency, and E-Mobility order intake of about EUR 15.5 billion, including EUR 2.0 billion for battery-electric drives and EUR 8.8 billion for hybrid drives.
Report summary
| Particulars | Details |
|---|---|
| Forecast Period | 2026-2036 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| CAGR (Value) | 10.6% |
| Format | PDF, Excel & Cloud Portal · 250 pages |
| Market Size (Value) in 2026 | USD 224.6 Billion |
| Market Size (Value) in 2036 | USD 612.5 Billion |
| Segments Covered | By Component: Battery Packs, Electric Motors & Generators, Power Electronics (Inverters & Power Control Units), DC-DC Converters, On-Board Chargers, Battery Management Systems, Transmissions & Reduction Gears, Integrated e-Axles & Electric Drive Units, Fuel Cell Stacks & Systems, Other Components. By Propulsion Type: Battery Electric Vehicles (BEVs), Plug-In Hybrid & Range-Extended Electric Vehicles (PHEVs & EREVs), Hybrid Electric Vehicles (HEVs), Fuel Cell Electric Vehicles (FCEVs). By Vehicle Type: Passenger Cars, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles, Buses, Two- & Three-Wheelers. By Voltage Architecture: Below 400 V (including 48 V), 400 V, 800 V & Above. |
| Countries Covered | Asia-Pacific: China, Japan, India, South Korea, Australia, Thailand, Indonesia, Rest of Asia-Pacific. Europe: Germany, France, U.K., Italy, Spain, Netherlands, Norway, Sweden, Poland, Rest of Europe. North America: U.S., Canada. Latin America: Brazil, Mexico, Rest of Latin America. Middle East & Africa: UAE, Saudi Arabia, Israel, Rest of Middle East & Africa. |
| Key Companies | Robert Bosch GmbH, BYD Company Limited, Contemporary Amperex Technology Co., Limited (CATL), ZF Friedrichshafen AG, BorgWarner Inc., Schaeffler AG, DENSO Corporation, Aisin Corporation, Astemo, Ltd., Magna International Inc., Valeo SE, Hyundai Mobis Co., Ltd., Mitsubishi Electric Mobility Corporation, Shenzhen Inovance Technology Co., Ltd. (Inovance Automotive), and LG Energy Solution, Ltd. |
Report overview
Segments covered: component, propulsion, vehicle type, voltage.
The growth of this market is mainly driven by the rapid growth of electric car sales, the electrification of trucks, buses, vans, and two- and three-wheelers, government emission regulations and incentives, and the expansion of charging infrastructure. In addition, the adoption of integrated electric drive units and e-axles, the shift to 800-volt architectures and silicon carbide (SiC) power electronics, the growth of plug-in hybrid and range-extended vehicles, and the expansion of electric vehicle production in emerging markets are further supporting the growth of this market.
The Electric Powertrain Market, also referred to as the EV powertrain, electric drivetrain, or electrified powertrain market, comprises the systems that store, convert, and deliver electrical energy to propel electric and hybrid vehicles. The market includes battery packs; traction motors and generators; power electronics, including inverters and power control units; DC-DC converters; on-board chargers; battery management systems; transmissions and reduction gears; integrated e-axles and electric drive units that combine the motor, inverter, and transmission; and fuel cell stacks and related systems for fuel cell electric vehicles. These systems are used in battery electric, plug-in hybrid, hybrid, and fuel cell electric passenger cars, commercial vehicles, buses, and two- and three-wheelers. The market ecosystem extends from raw material, cell, and semiconductor suppliers to component and system manufacturers, vehicle manufacturers, and fleet operators.
The electric powertrain is the core of every electric vehicle and accounts for a large share of vehicle cost and performance. The battery pack determines range and cost, the motor and inverter determine efficiency and power, and the on-board charger and power electronics determine charging speed. As electric vehicle sales grow and technology advances, the electric powertrain is becoming one of the largest segments of the automotive supply industry.
Electric vehicle sales continue to grow. According to the International Energy Agency (IEA), global electric car sales exceeded 20 million in 2025, up 20%, accounting for 25% of new car sales, with battery electric vehicles (BEVs) representing 65% of electric car sales, and are forecast to reach 23 million, or 28% of car sales, in 2026. China sold more than 13 million electric cars in 2025, nearly 55% of new car sales, Europe sold 4.2 million, or 28% of new car sales, and the U.S. sold around 1.5 million, or roughly 10% of new car sales, according to the IEA. The IEA estimates that China had around 44 million electric cars on the road, about 13% of its car fleet, and that around 5% of the global car stock is now electrified.
Commercial vehicle electrification is accelerating. According to the IEA, electric truck sales roughly doubled to more than 400,000 in 2025, reaching 9% of all truck sales, electric bus sales rose 12% to almost 70,000, electric van sales rose 45% to more than 430,000, and electric two- and three-wheeler sales reached around 11 million. China accounted for more than 90% of global electric truck sales, with about one in four trucks sold in China being electric, and heavy freight truck sales rose to around 230,000 units from around 84,000 in 2024. Electric commercial vehicles require larger battery packs and more powerful drive systems than passenger cars, increasing powertrain value per vehicle.
Chinese manufacturers are leading in scale. BYD sold about 4.6 million new energy vehicles in 2025, including about 2.26 million BEVs, with overseas sales of more than 1.04 million units, and targets overseas sales of 1.3 million units in 2026. Chinese automakers and suppliers are expanding vehicle and powertrain production in Europe, Southeast Asia, Latin America, and other regions, increasing competition for established suppliers.
Hybrid and range-extended powertrains are gaining importance as transition technologies. Schaeffler reported 2025 E-Mobility division revenue of EUR 5,015 million, up 7.0% at constant currency, and E-Mobility order intake of about EUR 15.5 billion, including EUR 2.0 billion for battery-electric drives and EUR 8.8 billion for hybrid drives. BorgWarner reported that light vehicle eProducts sales grew about 23% in 2025 and has won awards for integrated drive modules for range-extended electric trucks, large-frame SUVs, and hybrid range-extended powertrains, with production starting in 2029.
The pace of electrification varies by region, creating challenges for some suppliers. ZF reported a one-time charge of about EUR 1.6 billion in 2025, mainly for restructuring its Electrified Powertrain Technology division and terminating several customer projects early due to a slower-than-expected ramp-up of electric mobility, and called for policy adjustments, particularly regarding plug-in hybrids. U.S. electric car sales in Q4 2025 were about 45% lower than in Q4 2024, according to the IEA.
Technology is advancing rapidly. Automakers and suppliers are adopting integrated e-axles that combine the motor, inverter, and gearbox in a single unit, 800-volt architectures that enable faster charging, silicon carbide inverters that improve efficiency, and new battery chemistries such as lithium iron phosphate (LFP) and sodium-ion. In September 2026, Bosch unveiled a rigid eAxle for heavy commercial vehicles paired with SiC inverters with up to 99% efficiency, reflecting the extension of integrated drives to trucks.
Two- and three-wheelers are a large segment of electrification in Asia. According to the IEA, electric two-wheeler sales reached almost 10 million in 2025, with China accounting for more than 7 million, and electric three-wheeler sales exceeded 1.2 million, with India accounting for around 800,000, or almost 70% of three-wheeler sales in the country. These vehicles use smaller batteries and motors but represent large volumes for powertrain suppliers.
The supply side of the market includes several groups. Vertically integrated automakers, such as BYD, produce their own batteries, motors, and power electronics; battery manufacturers, such as CATL and LG Energy Solution, supply cells and packs to automakers worldwide; large Tier-1 suppliers, such as Bosch, ZF, Schaeffler, BorgWarner, DENSO, Aisin, Astemo, Magna, Valeo, Hyundai Mobis, and Mitsubishi Electric Mobility, supply motors, inverters, e-axles, and complete drive systems; and Chinese electric drive specialists, such as Inovance Automotive, supply motor controllers and drive assemblies to new energy vehicle makers. Competition is increasingly based on cost, integration, and global production footprint.
The value of the electric powertrain varies widely by vehicle type. A two-wheeler uses a small battery and motor, a passenger car uses a battery pack of typically tens of kilowatt-hours and one or two motors, and a heavy electric truck uses battery packs of several hundred kilowatt-hours and high-power e-axles. As electrification extends from cars to trucks and buses, the average powertrain value per vehicle is expected to increase, even as component costs decline.
Battery suppliers reflect the scale of the market. CATL, the largest battery manufacturer, reported 2025 revenue of CNY 423.7 billion, up 17.0%, with power battery revenue of CNY 316.5 billion, up 25.1%, and total battery sales of 661 GWh, including 541 GWh of power batteries. LG Energy Solution reported 2025 revenue of KRW 23.7 trillion, down 7.6%, due to slower EV sales at major customers, mainly in North America, and plans to begin mass production of LFP and high-voltage mid-nickel batteries for mid- to low-end EVs in 2026 while reallocating part of its North American capacity to energy storage.
The supplier landscape is being reshaped by restructuring and new partnerships. In May 2026, Nidec announced plans to withdraw from the e-axle business, which its CEO described as a "red ocean," after its e-axle unit recorded a loss of JPY 87.7 billion in the first half of the fiscal year, and to dissolve its e-axle joint ventures with GAC in China and Stellantis in Europe. In October 2026, Mitsubishi Electric agreed to transfer 50% of Mitsubishi Electric Mobility to an investment company of Hon Hai (Foxconn) for JPY 115.0 billion, forming a joint venture that will develop EV platforms including e-powertrains, with closing scheduled for October 2027. In December 2025, Honda announced that it would increase its stake in Astemo, formerly Hitachi Astemo, to 61%.
Report infographic
Market dynamics
15 factors across 5 forcesRapid Growth of Electric Car Sales
The rapid growth of electric car sales is a major factor driving the Electric Powertrain Market. According to the International Energy Agency (IEA), global electric car sales exceeded 20 million in 2025, up 20%, accounting for 25% of new car sales, with battery electric vehicles (BEVs) representing 65% of electric car sales, and are forecast to reach 23 million, or 28% of car sales, in 2026. Each electric car requires a battery pack, one or more traction motors, an inverter, an on-board charger, a DC-DC converter, and a battery management system, making electric car production the largest source of demand for electric powertrain components.
Growth is strongest in China and Europe. China sold more than 13 million electric cars in 2025, nearly 55% of new car sales, Europe sold 4.2 million, or 28% of new car sales, and the U.S. sold around 1.5 million, or roughly 10% of new car sales, according to the IEA. In Europe, electric car sales rose more than 30% in 2025 and are expected to grow about 20% in 2026, with one in three cars sold expected to be electric. This growth is expected to support strong demand for electric powertrains through the forecast period.
Electrification of Commercial Vehicles
Trucks, buses, and vans are electrifying rapidly. According to the IEA, electric truck sales roughly doubled to more than 400,000 in 2025, reaching 9% of all truck sales, electric bus sales rose 12% to almost 70,000, electric van sales rose 45% to more than 430,000, and electric two- and three-wheeler sales reached around 11 million. Electric heavy freight truck sales rose to around 230,000 units in 2025 from around 84,000 in 2024, and electric van sales in Europe rose about 70% to almost 200,000.
Commercial vehicles require much larger battery packs and more powerful motors and inverters than passenger cars, so their electrification increases powertrain value significantly. Suppliers are developing dedicated commercial vehicle drives, such as the Bosch rigid eAxle for 18- to 49-tonne trucks unveiled in September 2026.
Government Emission Regulations and Incentives
Governments are using emission standards, zero-emission vehicle mandates, and incentives to encourage electrification. The EU has CO2 standards for cars, vans, and trucks, China has new energy vehicle policies and incentives, and many countries offer purchase incentives, tax benefits, and support for charging infrastructure. These policies are key drivers of electric vehicle adoption and powertrain demand.
Policy changes can also slow demand in some markets, as reflected in the decline in U.S. electric car sales in Q4 2025, but overall regulatory pressure to reduce transport emissions is expected to support continued growth of electric powertrains through 2036.
Advances in Battery and Drive Technology
Advances in battery chemistry, motor design, and power electronics are improving range, performance, and cost. LFP batteries have reduced battery costs, integrated e-axles have reduced the size and weight of drive systems, and SiC inverters have improved efficiency. These improvements are making electric vehicles more affordable and attractive, supporting adoption.
Software and electronic integration are also becoming more important, as powertrain control, thermal management, and battery management software affect efficiency, range, and charging performance, and automakers increasingly seek suppliers that can deliver integrated hardware and software.
Table of contents
12 chapters · 155 sections · 250 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Component | Battery Packs | Integrated e-Axles & Electric Drive Units |
| By Propulsion Type | BEVs | FCEVs |
| By Vehicle Type | Passenger Cars | Medium & Heavy Commercial Vehicles |
| By Voltage Architecture | 400 V | 800 V & Above |
By Component
- Electric Powertrain Market Analysis by Component
- The Battery Packs segment is expected to account for the largest share of the global Electric Powertrain Market.
- The large share of this segment is mainly due to the high cost of battery packs relative to other powertrain components and the large volumes of electric cars, commercial vehicles, and two-wheelers produced.
- However, the Integrated e-Axles & Electric Drive Units segment is projected to register the highest CAGR during the forecast period.
- The rapid growth of this segment is attributed to the adoption of integrated drive units by automakers to reduce cost, size, and weight, and the extension of e-axles to commercial vehicles, as reflected in the Bosch rigid eAxle for heavy trucks unveiled in September 2026.
- Power electronics are expected to record strong growth, supported by the shift to 800-volt architectures and SiC inverters, while electric motors and on-board chargers are supported by rising electric vehicle production.
- Battery management systems and DC-DC converters are expected to record steady growth, supported by rising vehicle volumes, while fuel cell stacks and systems are expected to grow from a small base in commercial vehicle applications.
By Propulsion Type
- Electric Powertrain Market Analysis by Propulsion Type
- The BEVs segment is expected to account for the largest market share, as BEVs represented 65% of global electric car sales in 2025, according to the IEA, and require the largest battery packs and most powerful drive systems.
- However, the FCEVs segment is projected to register the highest CAGR during the forecast period, from a small base, driven by fuel cell trucks, buses, and commercial vehicles, while PHEVs and EREVs are expected to record strong growth as transition technologies.
By Vehicle Type
- Electric Powertrain Market Analysis by Vehicle Type
- The Passenger Cars segment is expected to account for the largest market share, due to electric car sales of more than 20 million in 2025.
- However, the Medium & Heavy Commercial Vehicles segment is projected to register the highest CAGR during the forecast period, driven by the rapid growth of electric trucks, with heavy freight truck sales rising to around 230,000 in 2025 from around 84,000 in 2024, according to the IEA.
- Two- and three-wheelers are expected to account for a significant share by volume, with around 11 million sales in 2025, while light commercial vehicles and buses are supported by fleet electrification and urban emission regulations.
By Voltage Architecture
- Electric Powertrain Market Analysis by Voltage Architecture
- The 400 V segment is expected to account for the largest market share, as most electric cars use 400-volt architectures.
- However, the 800 V & Above segment is projected to register the highest CAGR during the forecast period, driven by the adoption of 800-volt platforms for faster charging and higher efficiency and their use in commercial vehicles.
- Low-voltage electrified drives are also expanding, as reflected in the commercial launch of a 48-volt two-speed eAxle by Valeo in June 2026, selected by Dacia.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global Electric Powertrain Market. The large share of this region is mainly attributed to the scale of electric vehicle production and sales in China, which sold more than 13 million electric cars in 2025, nearly 55% of new car sales, and accounted for more than 90% of global electric truck sales and more than 7 million electric two-wheeler sales, according to the IEA. China also produced more than 80% of battery cells in 2025. China is home to leading electric vehicle and powertrain manufacturers, such as BYD, which sold about 4.6 million new energy vehicles in 2025, and CATL, the largest battery manufacturer. India is a large and fast-growing market for electric two- and three-wheelers, with around 800,000 electric three-wheeler sales in 2025, and Japan and South Korea are home to leading powertrain and battery suppliers, such as DENSO, Aisin, Astemo, Mitsubishi Electric Mobility, Hyundai Mobis, and LG Energy Solution. Southeast Asia is expanding electric vehicle production with investment from Chinese automakers. Within Asia-Pacific, China is expected to remain the largest country market through 2036, supported by its scale of electric vehicle production, battery manufacturing, and exports. India is expected to record strong growth, supported by two- and three-wheelers, buses, and a growing electric car market, while Thailand and Indonesia are expected to benefit from investment in electric vehicle and battery production. Overall, Asia-Pacific is expected to remain the largest market through 2036, given the scale of electric vehicle production in China and the growth of two- and three-wheelers in India and Southeast Asia, while Europe is expected to gain share due to CO2 regulations and rising electric car and commercial vehicle adoption.
Europe
Fastest growthHowever, Europe is projected to register the highest CAGR during the forecast period. According to the IEA, European electric car sales rose more than 30% to 4.2 million in 2025, or 28% of new car sales, with BEVs accounting for nearly 70% of electric car sales, and are expected to grow about 20% in 2026, with one in three cars sold expected to be electric. European electric van sales rose about 70% to almost 200,000, and Europe sold more than 12,000 electric buses. EU CO2 standards for cars, vans, and trucks are expected to drive further electrification, and Europe is home to leading powertrain suppliers, such as Bosch, ZF, Schaeffler, and Valeo. Schaeffler reported that its E-Mobility revenue grew 7.0% at constant currency in 2025, and Chinese automakers, including BYD, are expanding sales and production in Europe.
North America
North America is expected to record moderate growth. The U.S. sold around 1.5 million electric cars in 2025, roughly 10% of new car sales, but Q4 2025 sales were about 45% lower than in Q4 2024 following policy changes, according to the IEA. Growth is expected to be supported by electric pickup trucks, SUVs, and commercial vehicles, range-extended and hybrid powertrains, and the localization of battery and component production, and North America is home to suppliers such as BorgWarner and Magna.
Latin America
Latin America and the Middle East & Africa are expected to record strong growth from a small base, supported by imports and local production of Chinese electric vehicles, electric bus programs in Latin American cities, with more than 3,000 electric bus sales in Latin America in 2025, and electrification policies in the Gulf states.
Competitive landscape
The global Electric Powertrain Market is moderately consolidated, with large automotive suppliers, battery manufacturers, and vertically integrated automakers competing alongside specialized motor, inverter, and charger suppliers. Market participants compete primarily on cost, efficiency and power density, battery performance, integration capability, production scale, quality and reliability, and relationships with automakers.
Leading companies are investing in integrated e-axles, 800-volt and SiC power electronics, new battery chemistries, hybrid and range-extended drives, and commercial vehicle powertrains, and are restructuring and localizing production to match regional demand. Recent examples include the Bosch rigid eAxle for heavy trucks, the BorgWarner awards for integrated drive modules, the hybrid drive orders of Schaeffler, and the restructuring of the ZF Electrified Powertrain Technology division.
The report provides a comprehensive competitive assessment of the leading companies operating in the global Electric Powertrain Market. The key players profiled in the report include Robert Bosch GmbH (Germany), BYD Company Limited (China), Contemporary Amperex Technology Co., Limited (CATL) (China), ZF Friedrichshafen AG (Germany), BorgWarner Inc. (U.S.), Schaeffler AG (Germany), DENSO Corporation (Japan), Aisin Corporation (Japan), Astemo, Ltd. (Japan), Magna International Inc. (Canada), Valeo SE (France), Hyundai Mobis Co., Ltd. (South Korea), Mitsubishi Electric Mobility Corporation (Japan), Shenzhen Inovance Technology Co., Ltd. (Inovance Automotive) (China), and LG Energy Solution, Ltd. (South Korea).
Chinese electric drive specialists are also gaining scale. Inovance, a leading supplier of electric motor controllers and drive assemblies to Chinese new energy vehicle makers, reported revenue of about CNY 14.8 billion from its new energy vehicle and rail transit businesses in the first nine months of 2025, up about 38%.
- Robert Bosch GmbH
- BYD Company Limited
- Contemporary Amperex Technology Co., Limited (CATL)
- ZF Friedrichshafen AG
- BorgWarner Inc.
- Schaeffler AG
- DENSO Corporation
- Aisin Corporation
- Astemo, Ltd.
- Magna International Inc.
- Valeo SE
- Hyundai Mobis Co., Ltd.
- Mitsubishi Electric Mobility Corporation
- Shenzhen Inovance Technology Co., Ltd. · Inovance Automotive
- LG Energy Solution, Ltd
Expert perspectives
The Electric Powertrain Market is entering a period of sustained growth, driven by electric car adoption in China and Europe, the rapid electrification of commercial vehicles, and continued advances in battery and drive technology. IEA data showing more than 20 million electric car sales in 2025 and a doubling of electric truck sales provide strong demand visibility through the forecast period.
Three structural changes are expected to shape competitive positions through 2036. First, integrated e-axles and drive units are replacing separate components, favoring suppliers with system integration capabilities. Second, commercial vehicles are becoming a major source of powertrain value. Third, Chinese manufacturers are expanding internationally, increasing price competition and changing the supplier landscape.
For companies planning entry or expansion, the most defensible positions over the forecast period are likely to be found in integrated drive units, 800-volt and SiC power electronics, commercial vehicle powertrains, and hybrid and range-extended systems. For established suppliers, the principal risks are uneven regional adoption, policy uncertainty, price competition, and overcapacity.
Overall, the market is expected to grow strongly, with battery packs and passenger cars providing the base of demand and integrated drives, commercial vehicles, and 800-volt systems providing the fastest growth.
The pace of growth will depend on electric vehicle adoption in each region, policy decisions on emission standards and incentives, battery costs, and the speed of commercial vehicle electrification. Suppliers that combine cost-competitive components, system integration, and a global production footprint are expected to strengthen their positions over the forecast period.
Customer perspectives
Insights gathered during primary interviews with powertrain engineers, procurement managers, and fleet operators operating in this market highlight where procurement priorities are shifting. The following perspectives reflect recurring themes raised across these discussions.
“This reflects the importance of cost and integration in powertrain sourcing.”
“This indicates that efficiency and integration are key requirements for electric trucks.”
“This points to the growing role of electric commercial vehicles in urban logistics.”
Frequently asked questions
The global Electric Powertrain Market is estimated at USD 224.6 billion in 2026.
Cite this report
Meticulous Research. (2026). Electric Powertrain Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MRAUTO - 1041167). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/electric-powertrain-market-5850