Battery Manufacturing Equipment Market (2026-2036)
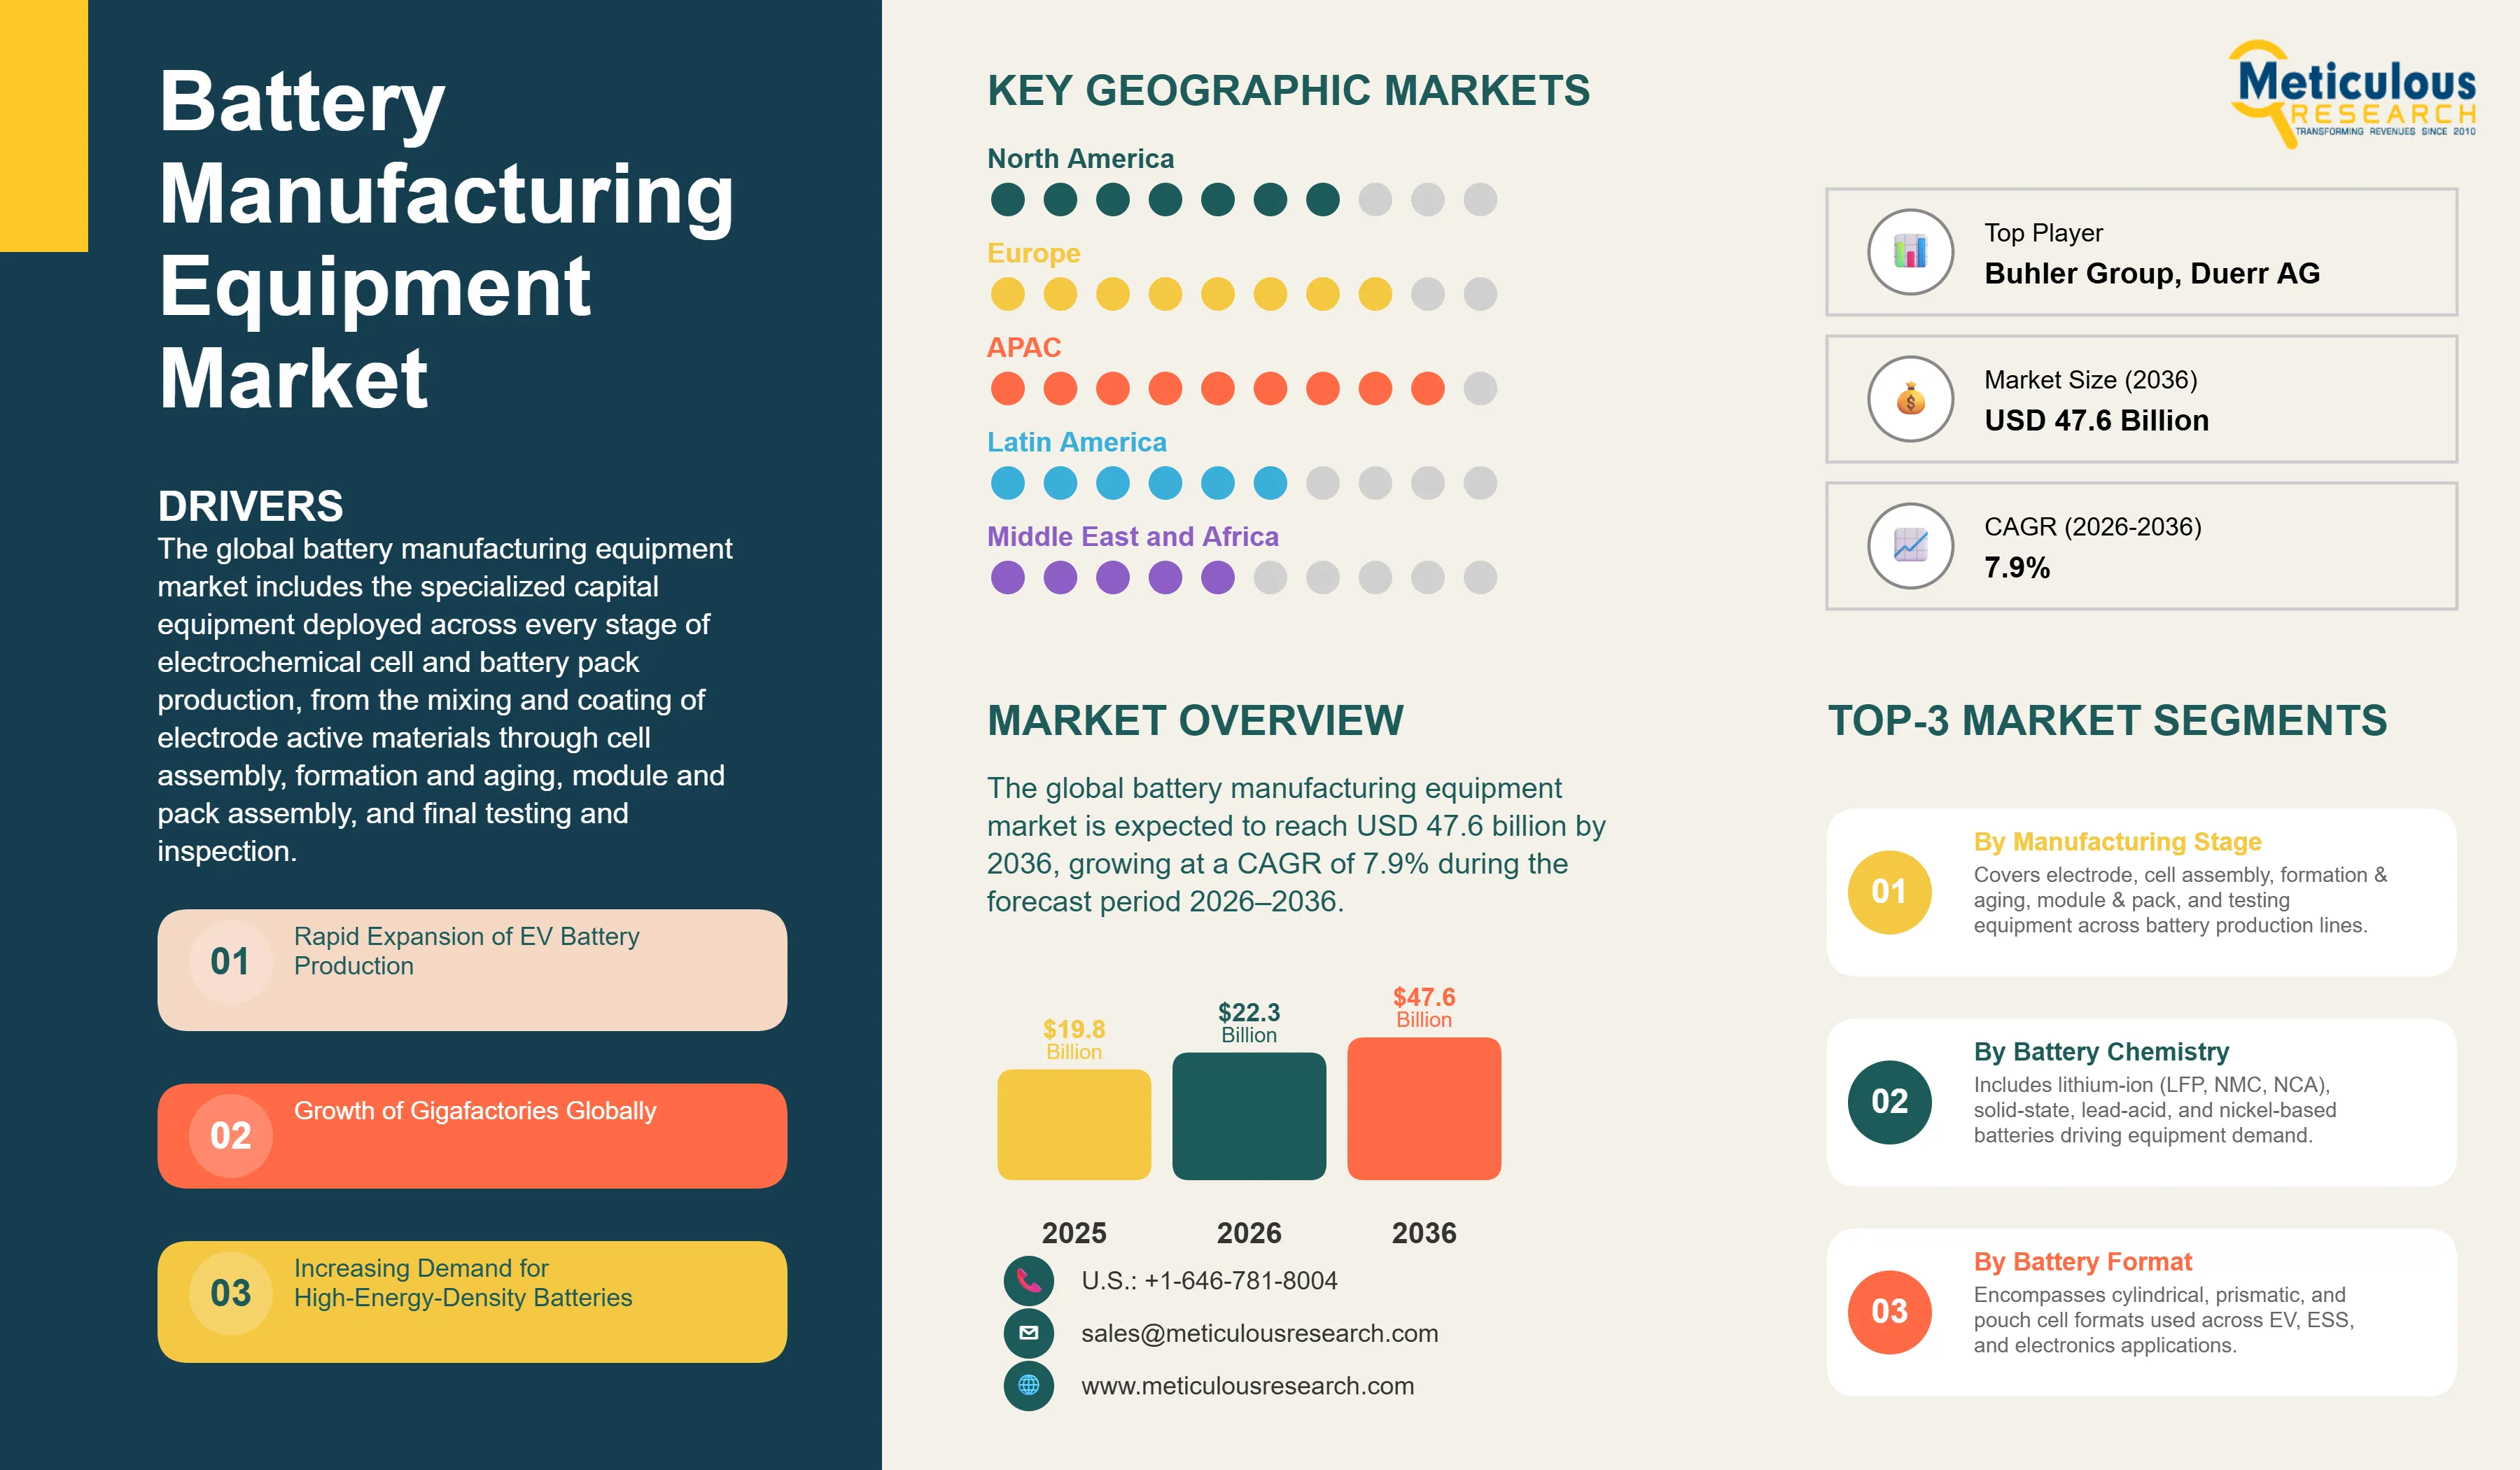
The global battery manufacturing equipment market was valued at USD 19.8 billion in 2025. This market is expected to reach USD 47.6 billion by 2036 from an estimated USD 22.3 billion in 2026, growing at a CAGR of 7.9% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 298
- Format
- PDF + Excel
- Report ID
- MR-1901
- Base year
- 2025
- 2025 · BASELINE
- $19.80B
- 2036
- $47.60B
- CAGR 2026–2036
- 7.9%
2025 baseline · 2026–2036 forecast at 7.9% CAGR · hover a bar for the value
Key highlights
The global battery manufacturing equipment market is projected to reach USD 47.6 billion by 2036.
The market is expected to grow at a CAGR of 7.9% during the forecast period 2026–2036.
The global battery manufacturing equipment market was valued at USD 19.8 billion in 2025 and is estimated to reach USD 22.3 billion in 2026.
Asia-Pacific is expected to dominate the global battery manufacturing equipment market with the largest market share in 2026, driven by China's unrivaled position as the world's largest battery manufacturing ecosystem encompassing the production facilities of CATL, BYD, CALB, and EVE Energy that collectively account for the majority of global lithium-ion cell production capacity, the dominant concentration of battery equipment manufacturers in China and South Korea supplying both domestic and global gigafactory expansion programs, South Korea's advanced battery equipment and materials technology base supporting the global manufacturing networks of LG Energy Solution, Samsung SDI, and SK On, and Japan's precision equipment manufacturing heritage delivering high-specification electrode coating, calendering, and cell assembly systems to battery manufacturers globally.
Europe is projected to witness the fastest growth during the forecast period, driven by the unprecedented gigafactory investment wave within the European Union encompassing Northvolt's Swedish facility, ACC's plants in France and Germany, AESC's Sunderland expansion, and the European manufacturing programs of CATL, Samsung SDI, SK On, and Volkswagen's PowerCo that collectively represent over 400 GWh of planned production capacity requiring comprehensive battery manufacturing equipment procurement, the EU Battery Regulation's domestic content requirements creating regulatory incentives for European battery production investment, and the strong policy support from EU member state governments providing capital grants and subsidies that are accelerating gigafactory development timelines and associated equipment procurement cycles.
By manufacturing stage, the electrode manufacturing equipment segment is expected to hold the largest share of the global battery manufacturing equipment market in 2026.
By battery chemistry, the lithium-ion batteries segment is expected to hold the largest share in 2026.
By battery format, the prismatic cells segment is expected to hold the largest share in 2026.
By application, the electric vehicles segment is expected to hold the largest share in 2026.
By automation level, the semi-automated equipment segment is expected to hold the largest share in 2026, while fully automated production lines are projected to register the fastest CAGR during the forecast period.
By end user, the battery manufacturers (cell producers) segment is expected to hold the largest share in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 47.6 Billion |
| Market Size in 2026 | USD 22.3 Billion |
| Market Size in 2025 | USD 19.8 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 7.9% |
| Dominating Manufacturing Stage | Electrode Manufacturing Equipment |
| Fastest Growing Manufacturing Stage | Formation & Aging Equipment |
| Dominating Battery Chemistry | Lithium-ion Batteries |
| Fastest Growing Battery Chemistry | Solid-State Batteries |
| Dominating Battery Format | Prismatic Cells |
| Fastest Growing Battery Format | Cylindrical Cells |
| Dominating Application | Electric Vehicles (EVs) |
| Fastest Growing Application | Energy Storage Systems (ESS) |
| Dominating Automation Level | Semi-Automated Equipment |
| Fastest Growing Automation Level | Fully Automated Production Lines |
| Dominating End User | Battery Manufacturers (Cell Producers) |
| Fastest Growing End User | OEMs |
| Dominating Geography | Asia-Pacific |
| Fastest Growing Geography | Europe |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: manufacturing stage, battery chemistry, battery format, application, automation level, end user.
The global battery manufacturing equipment market includes the specialized capital equipment deployed across every stage of electrochemical cell and battery pack production, from the mixing and coating of electrode active materials through cell assembly, formation and aging, module and pack assembly, and final testing and inspection. This market serves the production of lithium-ion batteries in cylindrical, prismatic, and pouch cell formats across the LFP, NMC, and NCA chemistry platforms, as well as the emerging solid-state battery manufacturing segment, lead-acid battery production, and nickel-based battery manufacturing. End users of battery manufacturing equipment include large-scale lithium-ion cell producers operating gigafactories, module and pack assembly specialists, automotive OEMs establishing in-house battery production operations, and research and development laboratories developing next-generation battery technologies and manufacturing processes.
The growth of the global battery manufacturing equipment market is primarily driven by the extraordinary global expansion of battery cell production capacity necessitated by the rapid scaling of electric vehicle manufacturing and the accelerating deployment of grid-scale energy storage systems. Global EV sales exceeded 17 million units in 2024 and are projected to reach 40 to 50 million units annually by the mid-2030s, each vehicle requiring battery packs containing 50 to 100 kilograms of battery cells manufactured on equipment that must achieve micron-level precision across coating, assembly, and formation processes at production throughputs measured in millions of cells per day. The response to this demand—the global gigafactory buildout encompassing over 200 announced or under-construction large-format battery manufacturing facilities representing more than 5,000 GWh of planned production capacity—is generating an equipment procurement wave of extraordinary scale that is the fundamental structural driver of the battery manufacturing equipment market throughout the forecast period.
Two transformative opportunities are defining the market's long-term trajectory. The commercial development of solid-state battery technology requires an entirely new generation of manufacturing equipment adapted to the material properties, processing requirements, and cell architectures of solid-state cell formats, creating a new and high-value equipment market segment as solid-state battery production scales from pilot to commercial volumes over the forecast period. Simultaneously, the progressive automation and digitalization of battery manufacturing—driven by the need to achieve automotive-grade production quality at gigafactory throughput scales while reducing direct labor costs and minimizing material waste—is driving sustained capital investment in advanced robotics, machine vision inspection systems, AI-powered process control platforms, and digital twin simulation tools that are transforming battery manufacturing from a labor-intensive process into a highly automated precision manufacturing discipline.
Report infographic
Market dynamics
7 factors across 3 forcesRapid Expansion of EV Battery Production
The rapid global expansion of electric vehicle adoption is generating battery cell production demand at an extraordinary scale that is the primary structural driver of the battery manufacturing equipment market, as every additional gigawatt-hour of annual battery cell production capacity requires capital investment in electrode manufacturing, cell assembly, formation, and testing equipment that collectively represents several hundred million dollars per GWh of new capacity at current automation levels. Global announced battery production capacity exceeds 5,000 GWh across all planned and under-construction gigafactory projects as of 2025, representing multi-hundred-billion-dollar aggregate equipment procurement requirements that will be executed progressively through the forecast period as gigafactory construction and commissioning timelines are realized. CATL's planned capacity expansion to over 1,000 GWh annually, BYD's vertical integration of cell production for its own EV manufacturing at a scale exceeding 400 GWh, LG Energy Solution's global manufacturing network spanning Asia, North America, and Europe, and the concurrent equipment procurement programs of dozens of additional battery manufacturers collectively constitute the largest sustained capital equipment purchasing program in the history of the global manufacturing equipment industry.
Growth of Gigafactories Globally
The emergence of the gigafactory as the defining production architecture of the battery manufacturing industry—characterized by single-site manufacturing complexes producing 10 GWh or more of battery cells annually in highly automated, vertically integrated production facilities—is creating a structural shift in the scale, specification, and procurement dynamics of the battery manufacturing equipment market that is generating sustained revenue expansion for equipment suppliers capable of serving multi-GWh production line requirements. Gigafactory-scale production is fundamentally different from the smaller-scale battery manufacturing operations that characterized the industry before the EV era, requiring equipment designed for continuous high-throughput operation at precision tolerances across production lines hundreds of meters in length, integrated process control and quality management systems capable of managing the statistical complexity of producing billions of cells per year, and equipment supply chain management at a global scale as battery manufacturers source electrode coating machines, winding systems, formation equipment, and testing lines from multiple specialized suppliers across Asia, Europe, and North America.
Table of contents
14 chapters · 181 sections · 298 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Manufacturing Stage | Electrode Manufacturing Equipment | Formation and aging equipment |
| By Battery Chemistry | Lithium-ion Batteries | Solid-state batteries |
| By Battery Format | Prismatic Cells | Cylindrical cells |
| By Application | Electric Vehicles | Energy storage systems |
| By Automation Level | Semi-Automated Equipment | Fully automated production lines |
| By End User | Battery Manufacturers (Cell Producers) | OEMs |
By Manufacturing Stage
- Electrode Manufacturing Equipment to Dominate
- The electrode manufacturing equipment segment is expected to account for the largest share of the global battery manufacturing equipment market.
- The dominant position of electrode manufacturing equipment reflects the critical technical importance and high capital cost of electrode coating and drying processes in lithium-ion cell manufacturing, where the slot-die coating of cathode and anode slurries onto copper and aluminum current collector foils at uniform thickness tolerances of plus or minus one micrometer across web widths of one meter or more represents the single most precision-demanding and capital-intensive process step in lithium-ion cell production.
- High-throughput electrode coating lines from leading suppliers including Hirano Tecseed, Buhler, and Wuxi Lead are among the highest unit-value individual equipment categories in the battery manufacturing equipment market, and the multiple coating lines required to support gigafactory electrode production volumes generate substantial aggregate equipment revenue.
- The ancillary electrode manufacturing equipment categories of calendering, which compresses coated electrodes to optimize active material density, and slitting, which cuts broad electrode web rolls into narrow strips matched to cell format dimensions, add further capital equipment procurement requirements to the electrode manufacturing stage.
- However, the formation and aging equipment segment is poised to register the highest CAGR during the forecast period.
- Formation systems—which execute the precisely controlled electrochemical charge and discharge cycles that activate newly assembled battery cells by forming the solid electrolyte interphase layer on the anode surface—represent an exceptionally capital-intensive equipment category because every cell produced must individually undergo multi-hour formation protocols, requiring formation chamber capacity scaled to the millions of cells in simultaneous formation at any time across a gigafactory's production output.
- The growth of gigafactory production capacity is generating proportional growth in formation equipment procurement requirements, and the technical advancement of formation protocols toward higher-speed formation processes that reduce the time and equipment capital required per cell is a major R&D focus for both battery manufacturers and formation equipment suppliers that is attracting significant investment.
By Battery Chemistry
- Lithium-ion Batteries to Hold the Largest Share
- The lithium-ion batteries segment is expected to account for the largest share of the global battery manufacturing equipment market.
- Lithium-ion battery manufacturing represents the overwhelming majority of current global battery production capacity investment, with LFP chemistry gaining significant share in EV and energy storage applications due to its compelling combination of low cost, excellent cycle life, and thermal stability, while NMC and NCA chemistries maintain strong positions in premium EV applications where high energy density and driving range justify their cost premium over LFP.
- The equipment requirements across LFP, NMC, and NCA lithium-ion cell production are broadly similar at the electrode coating, cell assembly, and testing stages, with chemistry-specific differences in slurry formulation, calendering pressure requirements, and formation protocol parameters that require equipment parameter adjustments rather than fundamentally different equipment platforms.
- However, the solid-state batteries segment is projected to register the highest CAGR during the forecast period.
- The high growth rate of this segment—from a very low base of pilot production equipment in 2026—reflects the advancing commercial development timelines of solid-state battery programs at Toyota, Samsung SDI, QuantumScape, Solid Power, and multiple Chinese solid-state battery developers, each of which requires specialized solid electrolyte deposition, lithium metal anode processing, and high-pressure cell assembly equipment that represents entirely new equipment procurement categories with no equivalent in current lithium-ion production.
By Battery Format
- Prismatic Cells to Hold the Largest Share
- The prismatic cells segment is expected to account for the largest share of the global battery manufacturing equipment market.
- Prismatic cell format adoption has accelerated significantly driven by CATL's large-format prismatic LFP cell platform, including the CTP (cell-to-pack) and Qilin battery architectures, that has achieved broad OEM adoption across the global EV market, BYD's blade battery prismatic format that has established a strong market position in both its own EV lineup and third-party OEM supply programs, and the broad preference for prismatic format in energy storage system applications where the rigid cell housing facilitates modular pack assembly and thermal management.
- Prismatic cell manufacturing requires stacking equipment for electrode assembly inside the rigid housing, laser welding systems for top-cap sealing, and precisely controlled electrolyte filling systems, each representing significant per-line capital equipment requirements.
- However, the cylindrical cells segment is projected to register the highest CAGR during the forecast period.
- Tesla's strategic commitment to the large-format 4680 cylindrical cell validated the cylindrical format's long-term competitive position in the EV market and stimulated substantial manufacturing equipment investment.
- The 4680 cell format requires new-generation winding equipment capable of handling the wider electrode widths and higher mechanical stresses of the larger format cell, and multiple battery manufacturers beyond Tesla including Panasonic, Samsung SDI, and Chinese producers are establishing 4680 production programs that are generating cylindrical equipment procurement growth.
By Application
- Electric Vehicles to Hold the Largest Share
- The electric vehicles segment is expected to account for the largest share of the global battery manufacturing equipment market.
- EV battery production constitutes the dominant end-use application driving global gigafactory capacity expansion and associated battery manufacturing equipment procurement, as passenger EV battery packs requiring 50 to 100 kWh of cell capacity represent the single largest and fastest-growing demand category for lithium-ion cells globally.
- The global EV market's continued strong growth trajectory, supported by government combustion engine phase-out mandates in the EU and U.K., the U.S. IRA's EV tax credit structure, and the improving price competitiveness of EVs relative to internal combustion vehicles, is translating directly into sustained gigafactory construction and equipment procurement programs by battery manufacturers and automotive OEMs establishing battery production capacity to serve their EV manufacturing operations.
- However, the energy storage systems segment is projected to register the highest CAGR during the forecast period.
- Grid-scale battery energy storage deployment is accelerating globally as renewable energy penetration increases and grid operators require battery storage to provide frequency regulation, peak capacity, and renewable firming services.
- The IEA projects that installed global battery storage capacity needs to grow from approximately 85 GWh in 2024 to over 1,500 GWh by 2030 to support net-zero energy transition pathways, implying battery cell production volume growth for energy storage applications that will generate substantial incremental manufacturing equipment demand across the forecast period.
By Automation Level
- Semi-Automated Equipment to Hold the Largest Share
- The semi-automated equipment segment is expected to account for the largest share of the global battery manufacturing equipment market.
- The large installed base of semi-automated production lines across established battery manufacturing facilities in China, South Korea, and Japan constitutes the majority of current global battery production capacity by line count and represents the equipment configuration of choice for the large number of mid-scale battery manufacturers producing below 5 GWh annually where the capital cost of full automation is not yet justified by production volume.
- Semi-automated lines provide a practical balance of production consistency, flexibility for product mix changes, and capital investment efficiency for battery manufacturers scaling from pilot to initial commercial production volumes.
- However, the fully automated production lines segment is projected to register the highest CAGR during the forecast period.
- The economic imperative of gigafactory-scale production—where direct labor cost reduction, consistent quality across billions of cells, and throughput maximization at 24-hour production schedules drive the business case for full automation—is accelerating the adoption of end-to-end automated production lines that eliminate manual material handling and inspection operations throughout the electrode manufacturing, cell assembly, formation, and pack assembly process.
- Leading battery manufacturers including CATL, LG Energy Solution, and Panasonic are specifying fully automated production lines as the standard configuration for new gigafactory phases, and automotive OEMs establishing in-house battery manufacturing operations are investing in full automation from the outset to achieve the quality and cost targets required for competitive EV battery production.
By End User
- Battery Manufacturers (Cell Producers) to Hold the Largest Share
- The battery manufacturers (cell producers) segment is expected to account for the largest share of the global battery manufacturing equipment market.
- Cell-level battery manufacturers—including the world's largest producers CATL, BYD, LG Energy Solution, Panasonic, Samsung SDI, SK On, CALB, and EVE Energy—represent the primary direct buyers of battery manufacturing equipment across the full production process spectrum from electrode manufacturing through cell assembly, formation, and testing, as cell production encompasses the most capital-intensive and technically demanding process stages of the battery manufacturing value chain.
- These manufacturers' ongoing gigafactory expansion programs generate the majority of global battery manufacturing equipment procurement by both value and volume, with CATL alone estimated to procure several billion dollars of manufacturing equipment annually across its global expansion program.
- However, the OEMs segment is projected to register the highest CAGR during the forecast period.
- Automotive OEMs including Volkswagen Group (through PowerCo), General Motors (through Ultium Cells), Stellantis, and Toyota are establishing in-house battery cell manufacturing capabilities for the first time, driven by strategic imperatives to control battery supply chain costs, secure battery supply for their EV production programs, and develop proprietary battery technology differentiation.
- These OEM-owned or joint venture cell manufacturing operations represent entirely new equipment procurement programs for companies with no prior battery manufacturing equipment purchasing experience, and their ambitious production scale targets—PowerCo targets 240 GWh of annual production capacity by 2030—imply large and rapidly growing equipment investment programs.
Geographic analysis
Asia-Pacific
Largest shareIn 2026, Asia-Pacific is expected to account for the largest share of the global battery manufacturing equipment market. The overwhelming dominance of Asia-Pacific in the global battery manufacturing equipment market reflects China's position as both the world's largest battery cell production center and the home of the world's largest concentration of battery manufacturing equipment manufacturers. China's battery manufacturing equipment industry, anchored by Wuxi Lead Intelligent Equipment, Shenzhen Yinghe Technology, Shenzhen Geesun, and dozens of additional specialized equipment producers, supplies the majority of equipment deployed in Chinese gigafactories and is increasingly competing for international gigafactory equipment contracts in Europe and North America. South Korea's battery equipment industry, supplying precision equipment to LG Energy Solution, Samsung SDI, and SK On's global manufacturing networks, contributes significant advanced equipment technology to the regional market. Japan's battery equipment manufacturing heritage provides precision manufacturing equipment for the Japanese battery industry and selective international customers. However, the European battery manufacturing equipment market is expected to grow at the fastest CAGR during the forecast period.
Europe
Europe's rapid growth is driven directly by the unprecedented gigafactory investment wave that is constructing the European battery manufacturing base to serve the continent's large and rapidly growing EV demand. The pipeline of announced and under-construction European gigafactories encompasses Northvolt's established Vasteras facility and planned expansions in Germany and other EU locations, ACC's facilities in France (Billy-Berclau) and Germany (Kaiserslautern), AESC's Sunderland Gigaplant, and the European manufacturing operations of CATL, Samsung SDI, SK On, and Envision AESC that collectively represent the largest sustained battery manufacturing investment program in European industrial history. Each gigafactory requires hundreds of millions of euros of manufacturing equipment procurement, and the European equipment market is attracting both Asian equipment suppliers establishing European sales and service operations and European industrial equipment companies that are investing in battery manufacturing equipment product lines to serve the growing domestic customer base.
North America
North America is establishing a rapidly expanding battery manufacturing equipment market, driven by the U.S. Inflation Reduction Act's domestic manufacturing requirements that are stimulating unprecedented gigafactory investment across the United States, Canada, and Mexico. The U.S. battery manufacturing capacity pipeline encompasses the Ultium Cells joint venture plants of General Motors and LG Energy Solution, Toyota's battery plant in North Carolina, Panasonic's facilities in Kansas and Nevada, and the battery manufacturing programs of multiple additional cell producers establishing North American production to qualify for IRA domestic content incentives. Canada's battery manufacturing investment includes Volkswagen's PowerCo gigafactory in St. Thomas, Ontario—one of the largest planned battery manufacturing investments in North American history—and Stellantis and LG Energy Solution's NextStar Energy plant in Windsor, Ontario, establishing Canada as a significant and rapidly growing battery equipment procurement market.
Competitive landscape
- Wuxi Lead Intelligent Equipment Co., Ltd.
- Manz AG
- Hitachi High-Tech Corporation
- PNT Co., Ltd.
- Shenzhen Yinghe Technology Co., Ltd.
- CIS Co., Ltd.
- CKD Corporation
- Hirano Tecseed Co., Ltd.
- Komax Holding AG
- KUKA AG
- Duerr AG
- Nordson Corporation
- Hanwha Corporation
Frequently asked questions
The global battery manufacturing equipment market is expected to reach USD 47.6 billion by 2036 from an estimated USD 22.3 billion in 2026, at a CAGR of 7.9% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Battery Manufacturing Equipment Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1901). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/battery-manufacturing-equipment-market-6584