Precision Medical Devices Market (2026-2036)
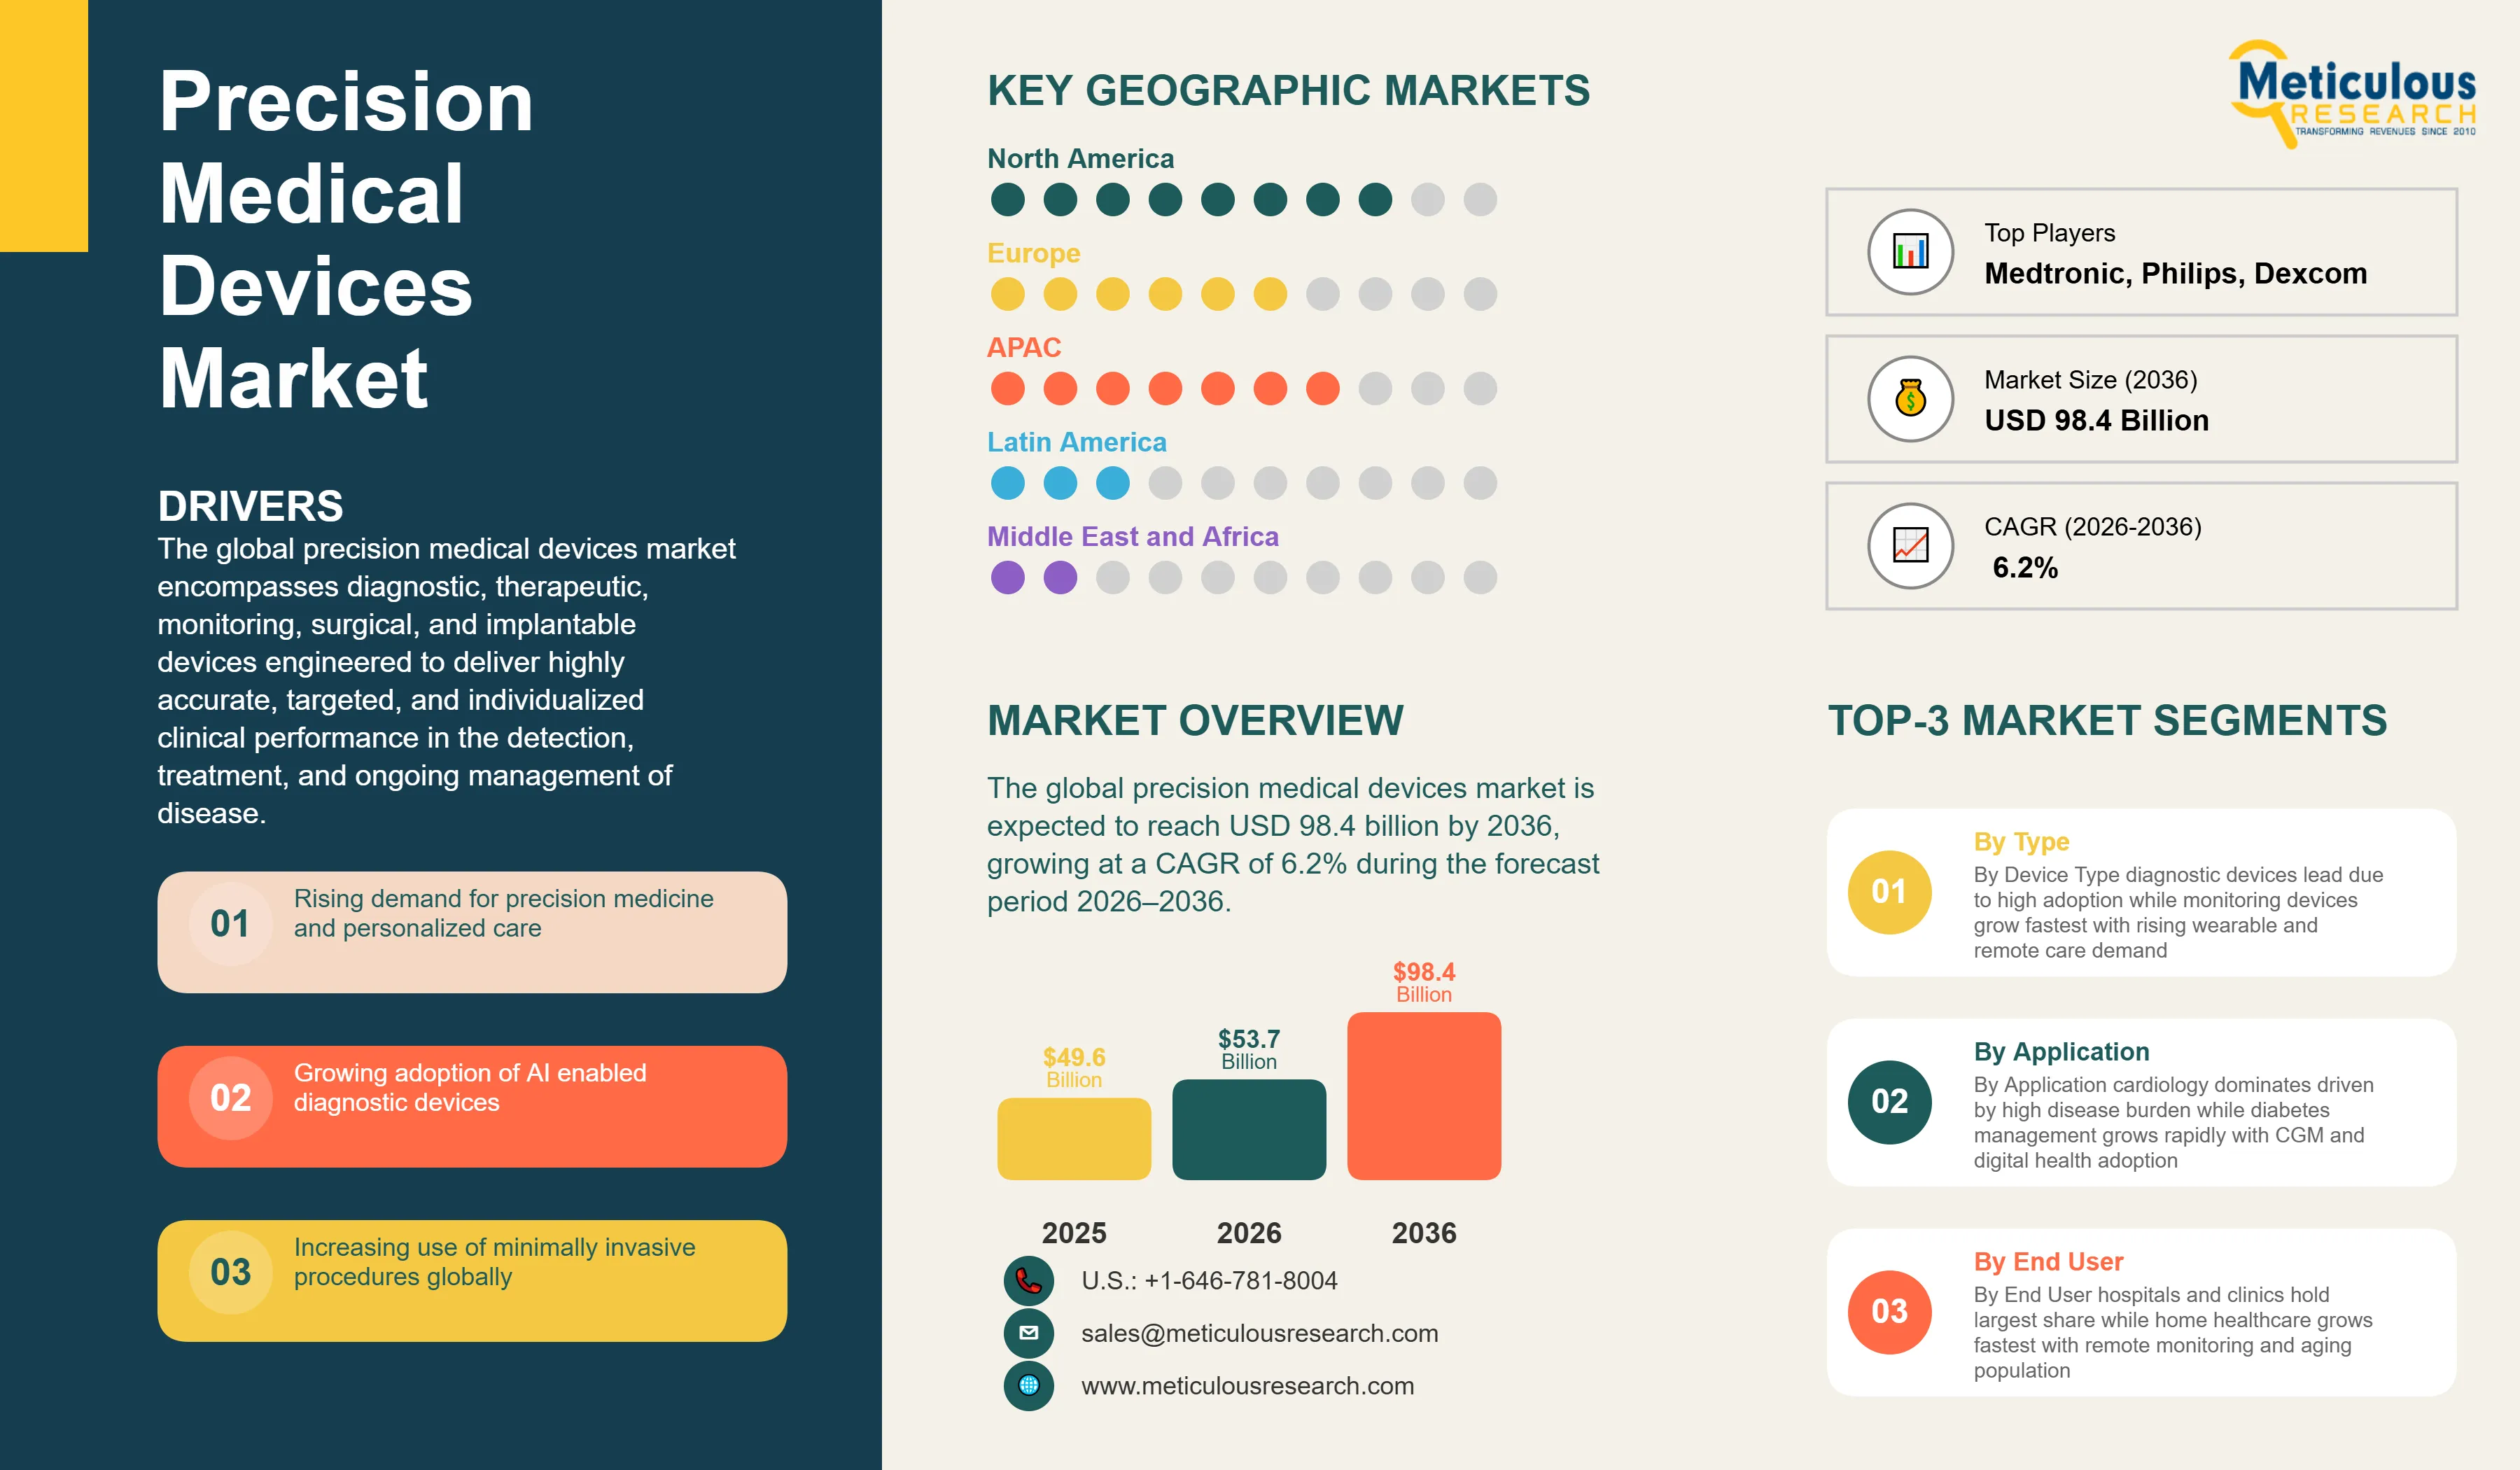
The global precision medical devices market was valued at USD 49.6 billion in 2025. This market is expected to reach USD 98.4 billion by 2036 from an estimated USD 53.7 billion in 2026, growing at a CAGR of 6.2% during the forecast period 2026–2036.
- Published
- Apr 2026
- Pages
- 310
- Format
- PDF + Excel
- Report ID
- MR-1890
- Base year
- 2025
- 2025 · BASELINE
- $49.60B
- 2036
- $98.40B
- CAGR 2026–2036
- 6.2%
2025 baseline · 2026–2036 forecast at 6.2% CAGR · hover a bar for the value
Key highlights
The global precision medical devices market is projected to reach USD 98.4 billion by 2036.
The market is expected to grow at a CAGR of 6.2% during the forecast period 2026–2036.
The global precision medical devices market was valued at USD 49.6 billion in 2025 and is estimated to reach USD 53.7 billion in 2026.
North America is expected to dominate the global precision medical devices market with the largest market share in 2026, driven by the United States' position as the world's largest medical device market supported by the highest per-capita healthcare expenditure globally, the presence of the world's most advanced medical device regulatory ecosystem administered by the FDA that facilitates the commercialization of cutting-edge precision technologies, the concentration of leading global medical device corporations including Medtronic, Abbott, Boston Scientific, Intuitive Surgical, and Dexcom headquartered in the U.S., and the strong reimbursement environment for advanced diagnostic and therapeutic devices provided by Medicare, Medicaid, and commercial insurance payers.
Asia-Pacific is projected to witness the fastest growth during the forecast period, driven by the rapidly expanding healthcare infrastructure investment across China, India, Japan, and South Korea, the rising burden of chronic diseases including cardiovascular conditions, diabetes, and cancer across Asia-Pacific's large and aging populations generating sustained demand for precision diagnostic and monitoring devices, the increasing adoption of AI-enabled medical imaging systems and robotic surgical platforms in major regional healthcare centers, and the growing domestic medical device manufacturing base in China and India supported by government healthcare modernization initiatives.
By device type, the diagnostic devices segment is expected to hold the largest share of the global precision medical devices market in 2026.
By technology, the imaging technologies segment is expected to hold the largest share in 2026.
By application, the cardiology segment is expected to hold the largest share in 2026.
By end user, the hospitals and clinics segment is expected to hold the largest share in 2026.
By connectivity, the standalone devices segment is expected to hold the largest share in 2026, while connected / IoT-enabled devices are projected to register the fastest CAGR during the forecast period.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 98.4 Billion |
| Market Size in 2026 | USD 53.7 Billion |
| Market Size in 2025 | USD 49.6 Billion |
| Revenue Growth Rate (2026–2036) | CAGR of 6.2% |
| Format | PDF, Excel & Cloud Portal · 310 pages |
| Dominating Device Type | Diagnostic Devices |
| Fastest Growing Device Type | Monitoring Devices |
| Dominating Technology | Imaging Technologies |
| Fastest Growing Technology | Artificial Intelligence & Machine Learning |
| Dominating Application | Cardiology |
| Fastest Growing Application | Diabetes Management |
| Dominating End User | Hospitals & Clinics |
| Fastest Growing End User | Home Healthcare Settings |
| Dominating Connectivity | Standalone Devices |
| Fastest Growing Connectivity | Connected / IoT-Enabled Devices |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: device type, technology, application, end user, connectivity.
The global precision medical devices market encompasses diagnostic, therapeutic, monitoring, surgical, and implantable devices engineered to deliver highly accurate, targeted, and individualized clinical performance in the detection, treatment, and ongoing management of disease. Precision medical devices are distinguished from conventional medical equipment by their integration of advanced technologies—including artificial intelligence, robotics, next-generation imaging modalities, biosensors, and additive manufacturing—that enable clinical outcomes defined by sub-millimeter spatial accuracy, real-time physiological data acquisition, patient-specific device customization, and connectivity-enabled clinical decision support. The market serves clinical applications spanning cardiology, oncology, neurology, orthopedics, diabetes management, and respiratory care through end users including hospitals and major medical centers, ambulatory surgical centers, diagnostic laboratories, home healthcare settings, and research institutions.
The growth of the global precision medical devices market is primarily driven by the converging structural forces of the global precision medicine paradigm shift and the accelerating technology integration of artificial intelligence, robotics, and advanced sensors into clinical device platforms. The global adoption of precision medicine—which tailors clinical interventions to individual patient characteristics defined by genomic, proteomic, metabolomic, and physiological data—is fundamentally reshaping requirements for medical devices, demanding diagnostic systems capable of molecular-level disease characterization, monitoring devices providing continuous high-resolution physiological data streams, and therapeutic devices capable of delivering individualized treatment at anatomical precision levels previously unattainable. This clinical imperative is intersecting with technology capabilities—AI algorithms achieving clinical-grade diagnostic accuracy, robotic surgical systems providing sub-millimeter operative precision, and biosensors enabling continuous minimally invasive monitoring—to create a sustained investment wave in precision device development and commercialization.
Two transformative opportunities are defining the market's long-term trajectory. The rapid growth of wearable and remote patient monitoring devices, driven by the post-pandemic expansion of telehealth, the aging of the global population, and the proliferation of smartphone-connected health tracking platforms, is democratizing access to precision physiological monitoring beyond the hospital setting, creating a vast and rapidly expanding consumer and clinical home monitoring market. Simultaneously, the integration of artificial intelligence into diagnostic imaging, pathology, and clinical decision support is creating a new category of AI-enabled precision diagnostic devices that augment clinician accuracy, reduce diagnostic errors, and enable earlier disease detection at a scale and consistency that human interpretation alone cannot achieve, attracting major investment from both established medical device companies and AI-focused healthcare technology entrants.
Report infographic
Market dynamics
7 factors across 3 forcesGrowing Adoption of Precision Medicine and Personalized Healthcare
The global paradigm shift from population-averaged disease management toward precision medicine—which uses genomic sequencing, molecular biomarker profiling, and advanced diagnostics to characterize individual disease biology and select treatments optimized for each patient's specific disease subtype—is the foundational structural driver of the precision medical devices market, as the precision medicine model's clinical effectiveness depends fundamentally on devices capable of molecular-level diagnosis, biomarker-guided therapeutic monitoring, and personalized treatment delivery. The cost of whole-genome sequencing has declined from approximately USD 100 million per genome in 2001 to under USD 200 in 2025, enabling the clinical deployment of genomic diagnostics at population scale and driving demand for advanced molecular diagnostic platforms that can process genomic data into clinically actionable treatment guidance. Precision oncology has become the standard of care across multiple cancer types, generating large and growing demand for next-generation sequencing diagnostic platforms, liquid biopsy devices, and companion diagnostic systems from leading companies including Roche Diagnostics, Illumina, and Foundation Medicine.
Increasing Demand for Minimally Invasive Procedures
The sustained global shift in surgical preference from open procedures to minimally invasive approaches—driven by documented clinical benefits including reduced operative blood loss, shorter hospital stays, faster patient recovery, lower infection risk, and improved cosmetic outcomes—is a primary structural demand driver for the precision surgical and interventional device categories. Minimally invasive surgery requires advanced precision instrumentation, including articulating laparoscopic instruments, high-definition endoscopic visualization systems, and energy-based tissue management devices, that deliver operative capability through small access incisions, directly expanding the addressable market for precision surgical devices that enable clinicians to perform complex procedures through anatomically constrained access geometries. The growth of transcatheter cardiac intervention has demonstrated that catheter-based precision devices can address cardiac conditions previously requiring open chest surgery, generating large market opportunities for device developers with precision guidance, imaging, and deployment technologies enabling transcatheter procedural success.
Table of contents
14 chapters · 174 sections · 310 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Device Type | Diagnostic Devices | Large share of this |
| By Technology | Imaging Technologies | Artificial intelligence and machine learning |
| By Application | Cardiology | Diabetes management |
| By End User | Hospitals & Clinics | Home healthcare settings |
| By Connectivity | Standalone Devices | Connected and IoT-enabled devices |
By Device Type
- Diagnostic Devices to Dominate
- The diagnostic devices segment is expected to account for the largest share of the global precision medical devices market.
- The large share of this segment is attributed to the fundamental clinical primacy of accurate diagnosis as the prerequisite for all subsequent therapeutic decision-making, the broad commercial deployment of advanced diagnostic imaging systems across hospital radiology departments and diagnostic imaging centers globally, the rapid growth of molecular and genomic diagnostic platforms enabling precision oncology and infectious disease characterization, and the very high unit value of large-format diagnostic imaging systems that generates substantial market revenue from the global hospital imaging equipment replacement and upgrade cycle.
- Siemens Healthineers, GE HealthCare, Philips, and Canon Medical represent the leading competitive positions in the advanced diagnostic imaging market.
- However, the monitoring devices segment is poised to register the highest CAGR during the forecast period.
- The high growth of this segment is attributed to the explosive commercial expansion of continuous glucose monitoring into mainstream diabetes care and prevention markets, the rapid growth of wearable cardiac monitoring platforms for atrial fibrillation detection and remote cardiac care, the expanding adoption of remote patient monitoring systems by health systems and insurers supporting post-acute care and chronic disease management programs, and the proliferation of consumer health monitoring wearables with FDA-cleared clinical measurement capabilities that are extending precision physiological monitoring to hundreds of millions of individuals outside the traditional medical device market.
By Technology
- Imaging Technologies to Hold the Largest Share
- The imaging technologies segment is expected to account for the largest share of the global precision medical devices market.
- Advanced medical imaging technology constitutes the largest installed base and highest revenue technology category within precision medical devices, serving as the clinical cornerstone of diagnosis, treatment planning, and therapeutic guidance across all major medical specialties.
- The continuous innovation cycle in imaging technology, including ultra-high-field 7T MRI, photon-counting CT, contrast-enhanced ultrasound, and spectral CT enabling material decomposition beyond conventional Hounsfield unit characterization, is driving sustained capital equipment replacement investment by healthcare institutions seeking to maintain diagnostic capability at the current clinical standard of care.
- However, the artificial intelligence and machine learning segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the accelerating FDA authorization of AI/ML-enabled medical devices across diagnostic imaging, pathology, cardiology, and ophthalmology applications, the integration of AI diagnostic software as a standard feature of new diagnostic imaging platform releases by major manufacturers, the growing clinical evidence base demonstrating AI diagnostic accuracy improvements over conventional analysis across high-volume imaging indications including chest X-ray interpretation, diabetic retinopathy screening, and skin lesion classification, and the commercial deployment of AI-powered clinical decision support systems by major health systems seeking to improve diagnostic consistency and operational efficiency.
By Application
- Cardiology to Hold the Largest Share
- The cardiology segment is expected to account for the largest share of the global precision medical devices market.
- Cardiology represents the broadest and most diverse application of precision medical devices across the full device type spectrum, encompassing precision diagnostic imaging including cardiac MRI and CT angiography, interventional devices including precision coronary stent delivery systems and transcatheter valve replacement platforms, implantable devices including high-resolution electrophysiology mapping systems, pacemakers, and implantable cardioverter defibrillators, and monitoring devices including wearable cardiac event monitors and implantable loop recorders.
- The global cardiovascular disease burden provides an immense clinical demand base for precision cardiac devices, and the innovation pipeline across transcatheter intervention, EP ablation, and remote cardiac monitoring is generating sustained new product-driven market growth.
- However, the diabetes management segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the rapid global expansion of continuous glucose monitoring adoption accelerated by the strong health outcomes evidence supporting CGM over conventional fingerstick monitoring, the advancement of closed-loop automated insulin delivery systems combining CGM with algorithm-controlled insulin pumps into hybrid and fully closed artificial pancreas platforms, the expansion of CGM indications beyond Type 1 diabetes into Type 2 and pre-diabetes monitoring markets that vastly expand the addressable patient population, and the intensifying global diabetes burden projected to reach 783 million people by 2045 according to the International Diabetes Federation.
By End User
- Hospitals & Clinics to Hold the Largest Share
- The hospitals and clinics segment is expected to account for the largest share of the global precision medical devices market.
- Hospitals and major medical centers represent the primary purchasing, deployment, and utilization environment for the highest-value precision medical device categories, including capital-intensive diagnostic imaging systems, robotic surgical platforms, advanced radiation therapy equipment, and complex interventional cardiology and neurology device suites, that collectively constitute the majority of global precision medical device market revenue.
- Large academic medical centers and tertiary referral hospitals are typically the first adopters of next-generation precision technologies, providing clinical validation environments that establish the evidence base supporting broader adoption across the hospital market, and their procurement decisions exert strong downstream influence on technology diffusion across the broader healthcare provider landscape.
- However, the home healthcare settings segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the post-pandemic institutionalization of remote patient monitoring programs by health systems and insurers, the rapid consumer adoption of FDA-cleared wearable health monitoring devices enabling clinical-grade continuous monitoring outside the hospital, the aging global population's preference for home-based care and independent living support enabled by precision monitoring technology, and healthcare system economic incentives favoring lower-cost home monitoring over higher-cost inpatient monitoring for appropriate stable chronic disease patient populations.
By Connectivity
- Standalone Devices to Hold the Largest Share
- The standalone devices segment is expected to account for the largest share of the global precision medical devices market.
- The large installed base of standalone diagnostic imaging systems, laboratory analyzers, surgical instruments, and implantable devices that operate as self-contained clinical platforms without network connectivity or cloud data integration constitutes the majority of the global precision medical devices installed base by both unit count and revenue value, establishing standalone devices as the structurally dominant connectivity category in the near term.
- Many of the highest-value precision device categories are implemented as standalone network-isolated clinical systems in many healthcare environments due to cybersecurity concerns, regulatory requirements, and IT infrastructure limitations that constrain the connectivity expansion of existing capital equipment.
- However, the connected and IoT-enabled devices segment is projected to register the highest CAGR during the forecast period.
- This growth is driven by the new product development strategies of all major precision medical device manufacturers increasingly prioritizing connectivity as a core platform feature, the clinical and operational value of real-time device data integration into electronic health record systems and clinical decision support platforms, the expansion of remote monitoring reimbursement by CMS and commercial payers creating economic incentives for healthcare providers to deploy connected monitoring devices, and the proliferation of consumer health IoT wearables that are establishing patient expectations for continuous connected health monitoring that are influencing clinical device adoption.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global precision medical devices market. The dominant position of North America in the global precision medical devices market reflects the confluence of the world's highest healthcare expenditure at approximately USD 4.5 trillion annually, the most advanced medical device regulatory and reimbursement ecosystem providing robust commercial pathways for innovative precision technologies, the concentration of the world's leading medical device innovation companies and most productive medical device R&D infrastructure, and the highest market penetration of advanced precision device categories including robotic surgical systems, AI-enabled diagnostic platforms, continuous glucose monitors, and implantable cardiac devices. The U.S. Medicare and Medicaid programs' adoption of reimbursement codes for new precision device categories including CGM, remote patient monitoring, and transcatheter cardiac interventions creates structured commercial markets that incentivize both adoption by healthcare providers and continued investment in precision device innovation by manufacturers. Canada contributes to regional growth through its universal healthcare system's investment in advanced diagnostic imaging and surgical technologies and its productive medical device research ecosystem centered around leading academic medical centers.
Asia-Pacific
Fastest growthHowever, the Asia-Pacific precision medical devices market is expected to grow at the fastest CAGR during the forecast period. Asia-Pacific's rapid growth is driven by the massive healthcare infrastructure expansion underway across China, India, and Southeast Asia as these economies invest in elevating their healthcare system capabilities to meet the demands of rapidly aging populations and rising chronic disease burdens. China's healthcare reform programs have allocated hundreds of billions of renminbi to hospital construction, medical equipment procurement, and domestic medical device industry development, generating enormous demand for advanced diagnostic imaging, surgical, and monitoring devices while simultaneously supporting the growth of domestic precision device companies including Mindray, United Imaging Healthcare, and Neusoft Medical. Japan and South Korea contribute advanced precision device demand from their highly developed healthcare systems and contribute precision device innovation from their established technology industries, with companies including Canon Medical, Fujifilm Healthcare, and Samsung Medison offering competitive precision imaging platforms to global markets. The rapidly growing middle-income populations of India, Indonesia, Vietnam, and Thailand are driving healthcare investment that is progressively expanding access to precision medical devices beyond the major metropolitan hospital centers that have historically been the primary regional adoption points.
Europe
Europe maintains a large and sophisticated precision medical devices market anchored by the continent's advanced healthcare systems, the strong tradition of medical device innovation in Germany, Switzerland, the Netherlands, and Sweden, and the regulatory framework provided by the EU Medical Device Regulation that establishes high clinical evidence standards for device performance and safety. The EU MDR's stringent post-market clinical follow-up requirements are increasing the clinical evidence burden for precision medical devices marketed in Europe but are simultaneously strengthening the value proposition of clinically validated precision technologies that meet the regulation's evidence standards. Germany's hospital sector represents the largest European market for advanced surgical and diagnostic precision devices, and the Swiss medical technology cluster centered around companies including Straumann, Ypsomed, and Medartis contributes significant precision device innovation in dental, drug delivery, and orthopedic implant categories.
Competitive landscape
- Medtronic plc · Ireland
- Siemens Healthineers AG · Germany
- GE HealthCare Technologies Inc. (U.S.)
- Philips Healthcare · Netherlands
- Abbott Laboratories (U.S.)
- Boston Scientific Corporation (U.S.)
- Stryker Corporation (U.S.)
- Intuitive Surgical, Inc. (U.S.)
- Johnson & Johnson MedTech (U.S.)
- Becton
- Dickinson and Company (U.S.)
- Roche Diagnostics · Switzerland
- Dexcom, Inc. (U.S.)
- Zimmer Biomet Holdings (U.S.)
- ResMed Inc. (U.S.)
- Masimo Corporation (U.S.)
Frequently asked questions
The global precision medical devices market is expected to reach USD 98.4 billion by 2036 from an estimated USD 53.7 billion in 2026, at a CAGR of 6.2% during the forecast period 2026–2036.
Cite this report
Meticulous Research. (2026). Precision Medical Devices Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1890). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/precision-medical-devices-market-6573