Long-Duration Energy Storage Market (2026-2036)
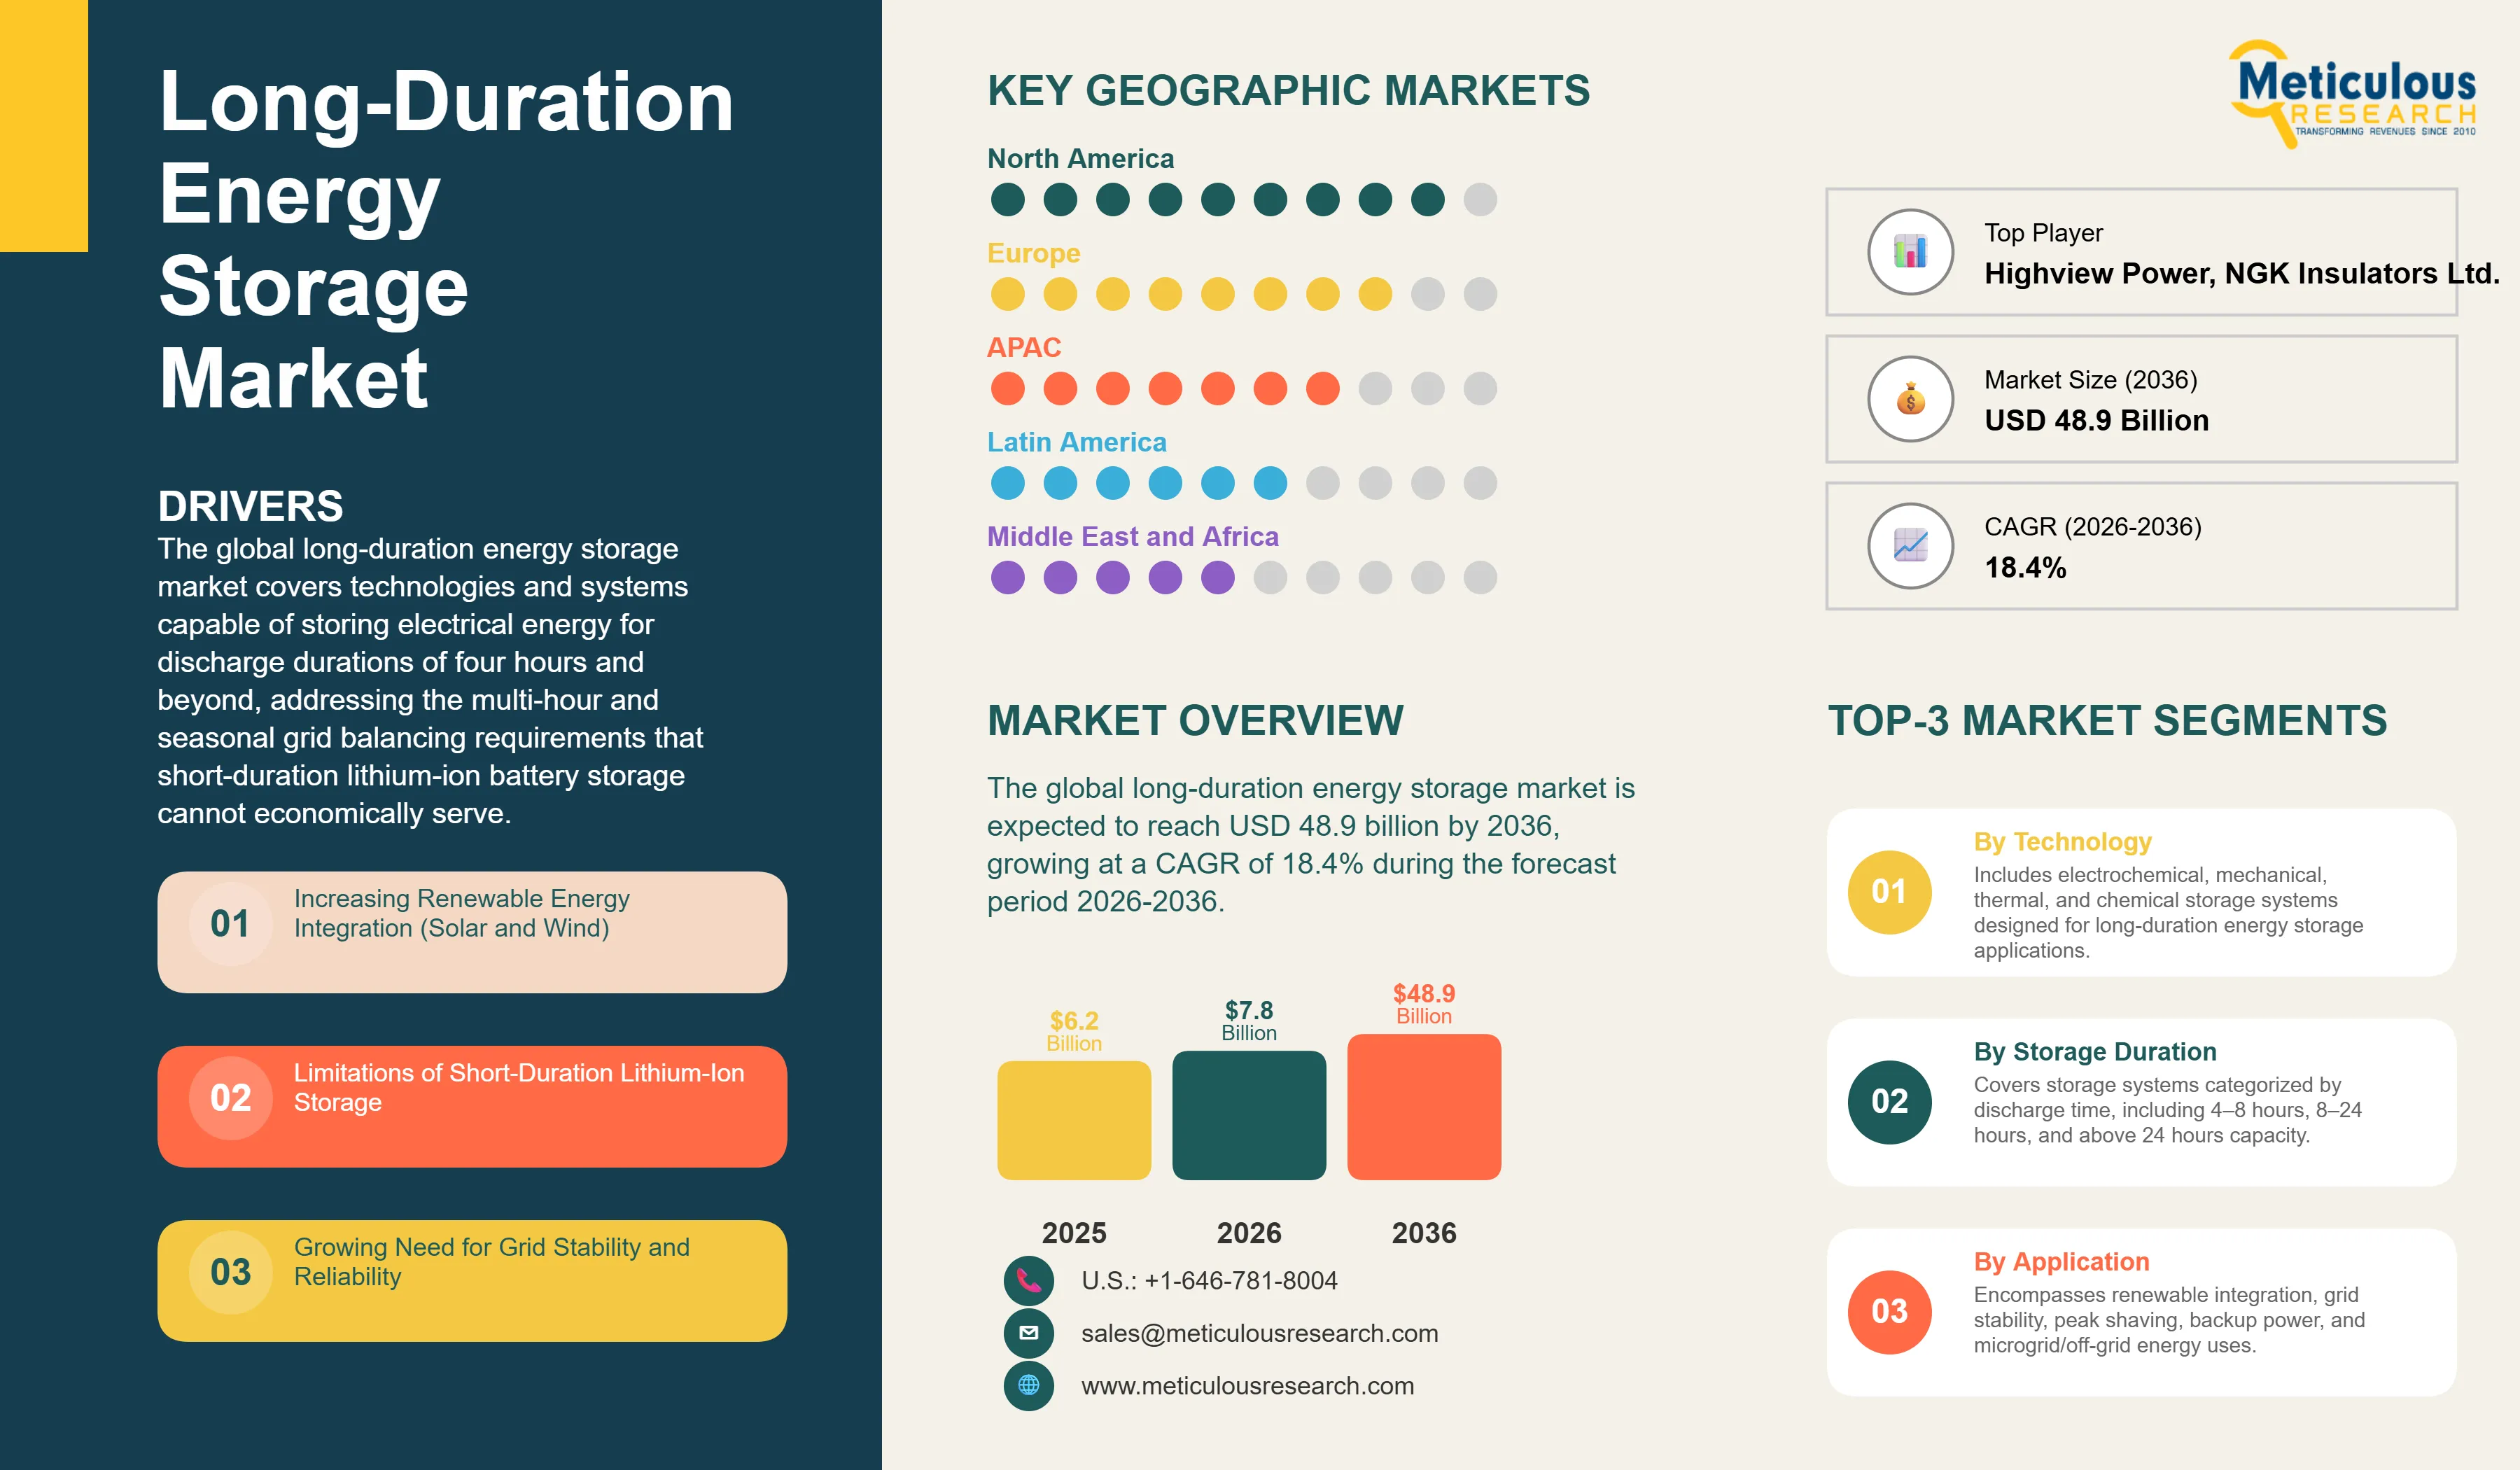
The global long-duration energy storage market was valued at USD 6.2 billion in 2025. This market is expected to reach USD 48.9 billion by 2036 from an estimated USD 7.8 billion in 2026, growing at a CAGR of 18.4% during the forecast period 2026-2036.
- Published
- Apr 2026
- Pages
- 295
- Format
- PDF + Excel
- Report ID
- MR-1900
- Base year
- 2025
- 2025 · BASELINE
- $6.20B
- 2036
- $48.90B
- CAGR 2026–2036
- 18.4%
2025 baseline · 2026–2036 forecast at 18.4% CAGR · hover a bar for the value
Key highlights
The global long-duration energy storage market is projected to reach USD 48.9 billion by 2036.
The market is expected to grow at a CAGR of 18.4% during the forecast period 2026-2036.
The market was valued at USD 6.2 billion in 2025 and is estimated to reach USD 7.8 billion in 2026.
North America is expected to dominate the global long-duration energy storage market with the largest market share in 2026.
By technology, the mechanical storage segment is expected to hold the largest share in 2026.
By storage duration, the 4 to 8 hours segment is expected to hold the largest share in 2026.
By application, the renewable energy integration segment is expected to hold the largest share in 2026.
By end user, the utilities segment is expected to hold the largest share in 2026.
By installation type, the grid-scale storage segment is expected to hold the largest share in 2026.
By energy capacity, the 100 to 500 MWh segment is expected to hold the largest share in 2026.
Report summary
| Particulars | Details |
|---|---|
| Market Size by 2036 | USD 48.9 Billion |
| Market Size in 2026 | USD 7.8 Billion |
| Market Size in 2025 | USD 6.2 Billion |
| Revenue Growth Rate (2026-2036) | CAGR of 18.4% |
| Format | PDF, Excel & Cloud Portal · 295 pages |
| Dominating Technology | Mechanical Storage |
| Fastest Growing Technology | Electrochemical Storage |
| Dominating Storage Duration | 4 to 8 Hours |
| Fastest Growing Storage Duration | Above 24 Hours |
| Dominating Application | Renewable Energy Integration |
| Fastest Growing Application | Microgrids and Off-Grid Systems |
| Dominating End User | Utilities |
| Fastest Growing End User | Independent Power Producers (IPPs) |
| Dominating Installation Type | Grid-Scale Storage |
| Fastest Growing Installation Type | Off-Grid Systems |
| Dominating Energy Capacity | 100 to 500 MWh |
| Fastest Growing Energy Capacity | Above 500 MWh |
| Dominating Geography | North America |
| Fastest Growing Geography | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2036 |
Report overview
Segments covered: technology, storage duration, application, end user, installation type, energy capacity.
The global long-duration energy storage market covers technologies and systems capable of storing electrical energy for discharge durations of four hours and beyond, addressing the multi-hour and seasonal grid balancing requirements that short-duration lithium-ion battery storage cannot economically serve. The market encompasses electrochemical technologies including vanadium redox flow batteries, iron-air batteries, and sodium-sulfur batteries; mechanical technologies including pumped hydro storage, compressed air energy storage, liquid air energy storage, and gravity-based systems; thermal storage including molten salt, solid-state, and cryogenic platforms; and chemical storage encompassing hydrogen-based storage and power-to-gas systems. These technologies collectively serve the grid stability, renewable integration, and energy resilience requirements of utilities, independent power producers, commercial and industrial customers, and off-grid communities.
The market's growth is driven by the accelerating global buildout of variable renewable energy capacity, which is creating multi-hour and multi-day supply-demand imbalances that short-duration storage cannot address. The structural limitation of four-hour lithium-ion systems in managing overnight solar gaps, multi-day wind lulls, and seasonal demand variations is motivating grid operators and policymakers to actively support the commercialization of long-duration alternatives. The U.S. Department of Energy's Long-Duration Storage Shot targeting an 90% reduction in storage costs for systems delivering more than 10 hours of duration, the European Union's battery regulation and grid flexibility frameworks, and national LDES procurement programs in the U.K., Australia, and California are creating the policy and funding environment required to scale nascent LDES technologies toward commercial deployment.
The market faces meaningful structural constraints. The capital cost of most LDES technologies remains substantially higher than short-duration lithium-ion alternatives on a per-kWh basis, and the absence of established revenue frameworks for the multi-hour grid services that LDES uniquely provides creates project financing uncertainty that slows investment decisions. Most electrochemical and novel mechanical LDES technologies are at early commercial stage with limited operational track records, increasing perceived technology risk for utilities and financiers accustomed to the established performance history of pumped hydro and lithium-ion systems.
These constraints are being progressively addressed as early commercial LDES deployments accumulate operational data, as power purchase agreement and capacity market structures evolve to compensate multi-hour storage services, and as technology costs decline through manufacturing scale and materials innovation. Form Energy's iron-air battery deployments with Georgia Power, Highview Power's liquid air energy storage commercial projects in the U.K., and Hydrostor's advanced compressed air energy storage pipeline in North America are building the commercial reference base that will enable broader project finance and utility procurement in the second half of the forecast period.
Report infographic
Market dynamics
7 factors across 3 forcesIncreasing Renewable Energy Integration (Solar and Wind)
The rapid global expansion of solar and wind generation capacity is creating multi-hour energy surplus and deficit periods that fundamentally require long-duration storage to manage. Solar generation produces surplus power during midday hours that exceeds real-time demand and must be stored for evening and overnight consumption, while wind generation variability creates multi-day periods of low output that cannot be bridged by four-hour battery systems. The International Energy Agency projects that achieving net-zero electricity systems will require 10 times the current installed storage capacity globally by 2050, with long-duration systems providing the majority of the incremental capacity needed to firm variable renewable output across daily and seasonal timescales. California's grid operator CAISO, the U.K.'s National Grid ESO, and Germany's Bundesnetzagentur have each identified multi-hour storage procurement as a critical near-term grid investment priority as renewable penetration approaches and exceeds 50% of annual generation in their respective markets.
Limitations of Short-Duration Lithium-Ion Storage
The structural inability of four-hour lithium-ion battery systems to serve multi-hour grid balancing, overnight renewable energy shifting, and seasonal storage applications is creating an addressable market gap for long-duration technologies that complements rather than competes with short-duration storage deployment. Lithium-ion system economics deteriorate sharply for storage durations beyond four to six hours due to the linear scaling of battery cell costs with energy capacity, making eight-hour and longer lithium-ion systems uneconomical relative to LDES technologies whose capital cost structures are partially or fully decoupled from discharge duration. The recognition by grid planners, utilities, and regulators that a storage-only clean electricity grid requires both short-duration and long-duration technologies serving distinct grid service functions is creating parallel procurement frameworks for LDES that are no longer competing against short-duration storage for the same project mandates.
Table of contents
14 chapters · 152 sections · 295 pages · click to expandSegmental analysis
| Segment | Largest share (2026) | Fastest growth (2026–2036) |
|---|---|---|
| By Technology | Mechanical Storage | Electrochemical storage |
| By Application | Renewable Energy Integration | Microgrids and off-grid systems |
| By End User | Utilities | Independent power producers |
| By Installation Type | Grid-Scale Storage | Off-grid systems |
| By Energy Capacity | 100 to 500 MWh | Above 500 MWh |
By Technology
- Mechanical Storage to Dominate
- The mechanical storage segment is expected to account for the largest share of the market, reflecting the overwhelming dominance of pumped hydro storage in the global installed long-duration storage capacity base.
- Pumped hydro represents approximately 90% of total installed LDES capacity globally, with over 170 GW of operational capacity across Asia, Europe, and North America providing multi-hour to multi-day energy shifting services.
- The mature technology status, multi-decade operational lifetimes, and low levelized cost of storage for well-sited pumped hydro projects make it the reference benchmark against which all emerging LDES technologies are assessed.
- Compressed air energy storage projects in development in Canada, the United States, and Australia are adding to the mechanical storage pipeline alongside pumped hydro expansion.
- Electrochemical storage is projected to register the highest CAGR during the forecast period, driven by the commercial scale-up of iron-air, vanadium redox flow, and all-iron flow battery technologies that offer deployment flexibility not available to pumped hydro and compressed air systems, enabling LDES at grid-connected substations and industrial sites without specific geological or hydrological prerequisites.
- 4 to 8 Hours to Hold the Largest Share
- The 4 to 8 hours segment is expected to account for the largest share of the market.
- This segment represents the initial commercial frontier of long-duration storage, covering the discharge duration range immediately beyond the commercial sweet spot of four-hour lithium-ion systems and addressing the overnight solar energy shifting and evening peak demand applications that represent the largest near-term grid service revenue opportunity for LDES.
- The majority of current commercial LDES project procurements in the United States, U.K., and Australia target storage durations in the 6 to 12 hour range where economic value is clearest and technology options are most established.
- The above 24 hours segment is projected to register the highest CAGR during the forecast period, representing the frontier of seasonal and multi-day storage applications that become essential for electricity grids with renewable penetration exceeding 80% of annual generation.
- Hydrogen-based storage, liquid air energy storage, and large-scale pumped hydro with very high reservoir capacity are the primary technology candidates for this duration tier, which will see accelerating deployment in the second half of the forecast period as renewable penetration in leading markets approaches levels requiring multi-day storage support.
By Application
- Renewable Energy Integration to Hold the Largest Share
- The renewable energy integration segment is expected to account for the largest share, reflecting the primary value proposition of LDES as the essential complement to variable renewable generation that enables clean electricity systems to deliver reliable power independent of short-term solar and wind output variations.
- The deployment of LDES for renewable integration is being actively incentivized through capacity auction frameworks, storage mandates, and renewable firming contracts across the United States, United Kingdom, Australia, and Germany.
- Microgrids and off-grid systems is projected to register the highest CAGR during the forecast period.
- Island grids, remote mining operations, military installations, and data centers requiring 24-hour clean power supply without utility grid backup are driving demand for LDES systems capable of providing multiple days of energy autonomy, supporting the deployment of both flow battery and liquid air storage technologies in off-grid applications at premium pricing relative to utility grid-connected installations.
By End User
- Utilities to Hold the Largest Share
- The utilities segment is expected to account for the largest share of the market, reflecting utilities' role as the primary procurers of grid-scale long-duration storage capacity through regulated capital investment programs, competitive storage tenders, and bilateral capacity contracts.
- Utilities in California, Arizona, New York, the U.K., and Germany are advancing LDES procurement frameworks that mandate multi-hour storage procurement alongside renewable energy portfolio targets.
- Independent power producers are projected to register the highest CAGR during the forecast period, driven by the growing developer activity in merchant LDES projects capturing renewable energy arbitrage and capacity market revenues without utility offtake backing, enabled by the increasing depth of LDES-relevant grid services markets and the improving project economics of leading LDES technologies.
By Installation Type
- Grid-Scale Storage to Hold the Largest Share
- The grid-scale segment is expected to account for the largest share, reflecting the concentration of long-duration storage value creation in large transmission-connected systems that provide multi-hour balancing services to bulk electricity markets.
- Grid-scale LDES projects ranging from 50 MW to several hundred MW in capacity connected at the transmission or distribution substation level represent the primary commercial opportunity for the current generation of pumped hydro, compressed air, flow battery, and large-scale thermal storage technologies.
- Off-grid systems is projected to register the highest CAGR during the forecast period, supported by the strong economics of LDES in displacing diesel generation at remote and island locations where the fuel cost of conventional backup generation and the grid extension cost create favorable economics for renewable-plus-LDES systems even at current technology costs.
By Energy Capacity
- 100 to 500 MWh to Hold the Largest Share
- The 100 to 500 MWh segment is expected to account for the largest share, representing the project size range that aligns with current utility procurement tender requirements and the commercial scale of leading LDES technology deployments.
- Projects in this capacity range balance site availability, grid interconnection requirements, and capital commitment levels that are within the investment threshold of utility capital programs and infrastructure fund mandates.
- The above 500 MWh segment is projected to register the highest CAGR during the forecast period, driven by the progression of LDES from initial commercial deployments toward large flagship projects targeting gigawatt-hour scale capacity.
- Multi-gigawatt-hour pumped hydro projects in Australia, compressed air storage projects in Canada, and hydrogen-coupled seasonal storage installations in Northern Europe represent the pipeline of above-500 MWh projects that will define the market's scale trajectory through the late forecast period.
Geographic analysis
North America
Largest shareIn 2026, North America is expected to account for the largest share of the global long-duration energy storage market. The region's leadership is anchored by the United States, where the combination of the Inflation Reduction Act's investment tax credit for standalone storage, the DOE's Long-Duration Storage Shot, and California and New York state-level storage procurement mandates has created the most financially supportive policy environment for LDES commercialization globally. California's CPUC storage mandate, requiring utilities to procure substantial LDES capacity by 2030, is directly driving procurement activity from Pacific Gas and Electric, Southern California Edison, and San Diego Gas and Electric that represents among the largest utility LDES tender pipelines worldwide. The active developer ecosystem including Form Energy, Hydrostor, Highview Power, and Energy Vault with projects in advanced development across the United States and Canada, supported by DOE loan guarantee and grant programs, is building the early commercial reference base for the full range of LDES technology categories.
Europe
Europe represents the second largest regional market, driven by the European Union's ambition to deploy 600 GW of renewable energy by 2030 under the REPowerEU program that creates structural multi-hour storage demand at a scale requiring long-duration solutions beyond the capacity of short-duration lithium-ion systems alone. The U.K.'s Longer Duration Energy Storage Demonstration competition, Germany's hydrogen storage investment programs, Norway's pumped hydro pipeline leveraging exceptional topographical and hydrological resources, and the Nordic region's seasonal storage requirements collectively create a diverse and deep pipeline of LDES projects across technology categories. The EU Innovation Fund's support for large-scale CAES, liquid air, and advanced flow battery projects is advancing commercial demonstrations of multiple LDES technology platforms toward investment-grade operational track records.
Asia-Pacific
Fastest growthHowever, Asia-Pacific is expected to grow at the fastest CAGR during the forecast period. China's massive renewable energy deployment, exceeding 1.2 TW of installed wind and solar capacity in 2025, is creating an urgent and structurally large demand for long-duration balancing capability at a scale that no other region approaches. China's National Development and Reform Commission has designated new energy storage as a strategic industry priority with specific LDES procurement targets embedded in provincial energy transition plans. Australia's ambitious 82% renewable electricity target by 2030 under the Capacity Investment Scheme is driving an exceptional pipeline of pumped hydro, battery, and emerging LDES technology projects across the National Electricity Market. India's renewable energy expansion under its 500 GW non-fossil capacity target and Japan's strategic battery and hydrogen storage programs are further reinforcing the region's position as the fastest-growing LDES market through the forecast period.
Competitive landscape
- Form Energy Inc. (U.S.)
- ESS Tech Inc. (U.S.)
- Fluence Energy Inc. (U.S.)
- Highview Power (U.K.)
- Hydrostor Inc. · Canada
- Siemens Energy AG · Germany
- General Electric Company (U.S.)
- Mitsubishi Power · Japan
- Sumitomo Electric Industries Ltd. · Japan
- NGK Insulators Ltd. · Japan
- Invinity Energy Systems (U.K.)
- Energy Vault Holdings Inc. (U.S.)
- Malta Inc. (U.S.)
- Primus Power Corporation (U.S.)
- Redflow Limited · Australia
Frequently asked questions
The global long-duration energy storage market is expected to reach USD 48.9 billion by 2036 from an estimated USD 7.8 billion in 2026, at a CAGR of 18.4% during the forecast period 2026-2036.
Cite this report
Meticulous Research. (2026). Long-Duration Energy Storage Market - Global Opportunity Analysis and Industry Forecast (2026-2036) (Report No. MR-1900). Meticulous Market Research Pvt. Ltd. https://www.meticulousresearch.com/product/long-duration-energy-storage-market-6583